

 Bank

A crypto bank is a financial institution or platform that offers banking-style services for digital assets alongside, or instead of, traditional money. Customers can hold crypto and fiat in one place, buy and sell assets, send payments, and often spend through a card. Some crypto banks are licensed banks; many are not banks in the legal sense and work under e-money, payment or crypto licenses, or through a licensed partner.
This guide explains how crypto banks work, the main types, how they compare with traditional banks, what makes them safe or risky, and how regulation has changed. If you are planning to launch one, our step-by-step guide on how to build a crypto bank covers the practical side.
What Is a Crypto Bank?
“Crypto bank” is a market term, not a legal category. It describes any provider that combines two things: familiar banking features, such as accounts, cards and transfers, and services for digital assets, such as custody, trading and stablecoin payments.
The key difference from a crypto exchange is the banking layer. An exchange is built for trading. A crypto bank is built for everyday money management: receiving a salary, paying bills, converting between crypto and fiat, and keeping savings in one app.
Crypto Bank vs Digital Bank
A digital bank, or neobank, delivers traditional banking through an app and works with fiat money. A crypto bank adds digital assets to that model. In practice, the line is blurring as more neobanks add crypto features. Olena Petrashchuk from 4IRE explains the difference in this short video.
How Crypto Banks Work
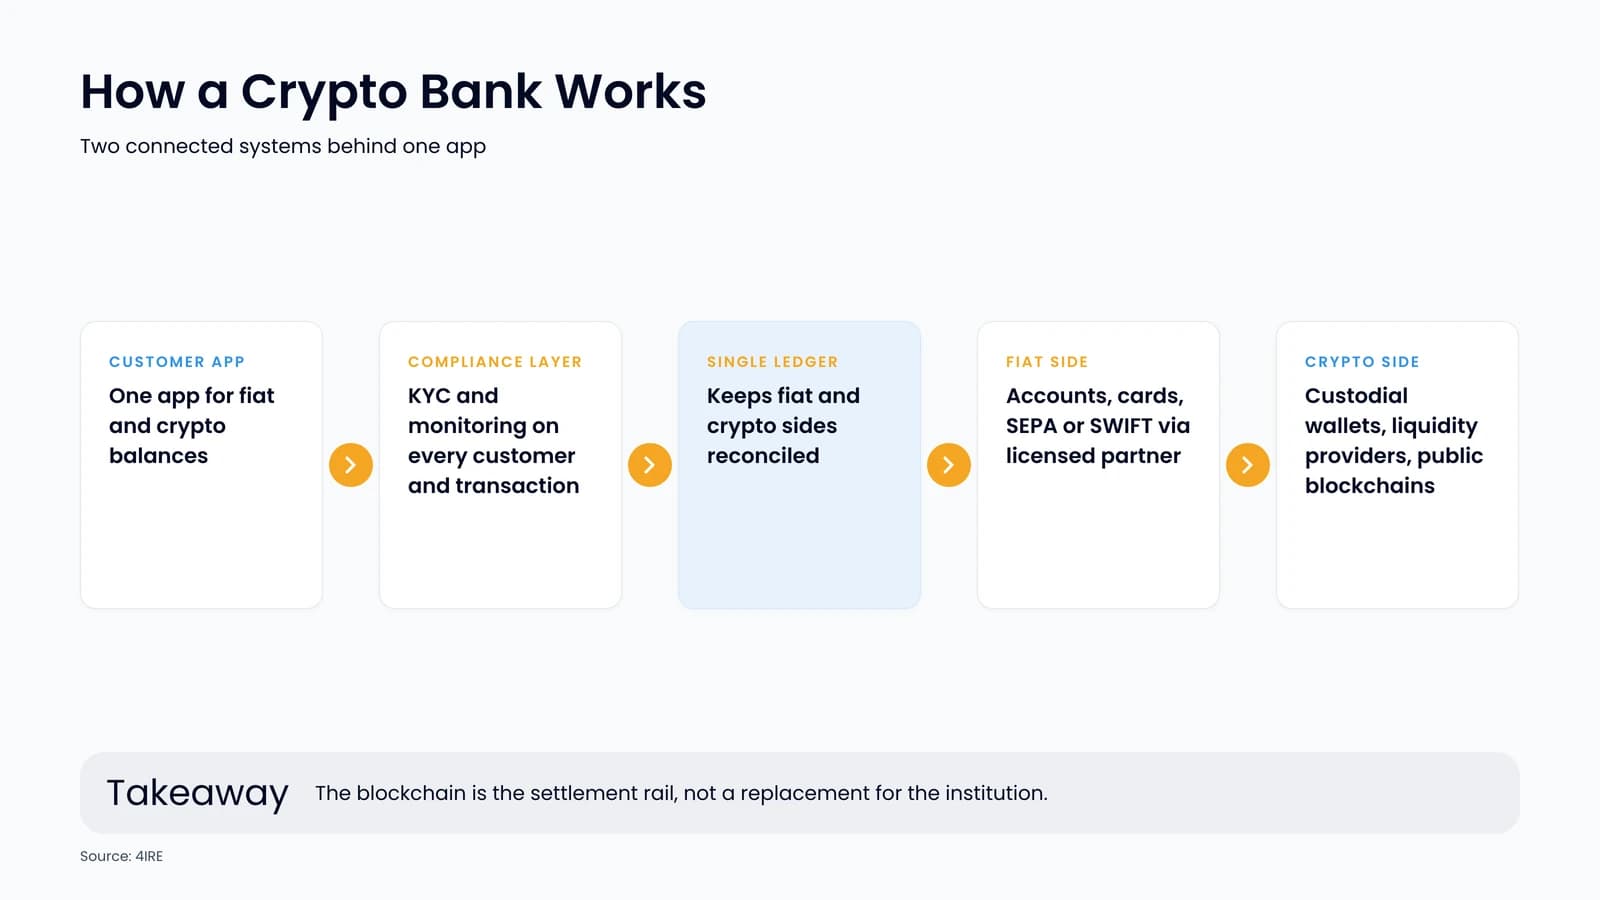
Behind the app, a crypto bank runs two connected systems. The fiat side works like any digital bank: accounts, card issuing and payment rails such as SEPA or SWIFT, usually through a licensed bank or e-money partner. The crypto side holds digital assets in custodial wallets, connects to exchanges or liquidity providers for conversions, and moves assets on public blockchains.
A single ledger keeps both sides reconciled, and a compliance layer checks every customer and transaction. That point matters: despite the old “decentralized bank” marketing, a regulated crypto bank is a custodial, identity-verified service. The blockchain is the settlement rail, not a replacement for the institution.
Types of Crypto Banks
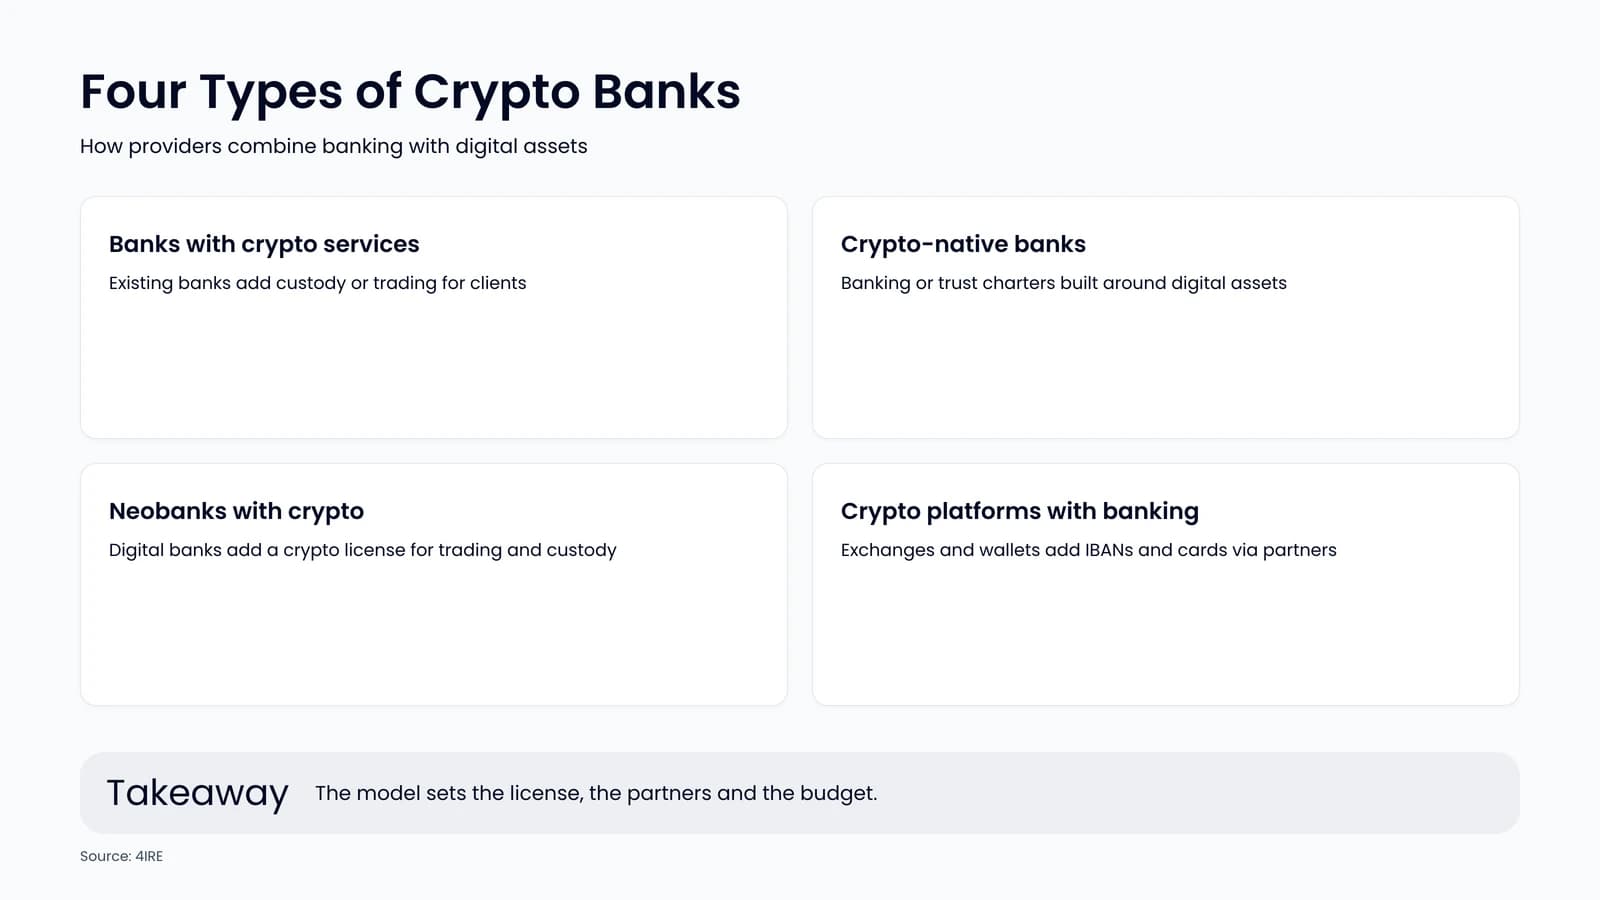
Four models dominate today.
- Traditional banks with crypto services. Established banks add custody or trading for their clients. In December 2025, PNC let PNC Private Bank clients buy and hold bitcoin directly, powered by Coinbase’s infrastructure. Our article on why banks adopt crypto modules covers this trend.
- Crypto-native banks. Companies licensed as banks or trust banks around digital assets. Switzerland’s AMINA Bank, formerly SEBA, received a FINMA banking license in August 2019. In the US, Anchorage Digital received conditional OCC approval to become a national trust bank in January 2021, and in December 2025 the OCC conditionally approved five more national trust bank charters for crypto firms, including Circle, Ripple and Paxos.
- Neobanks with crypto features. Digital banks that add trading and custody. Revolut, for example, received a MiCA license in Cyprus in October 2025 to offer crypto services across the European Economic Area.
- Crypto platforms with banking features. Exchanges and wallets that add IBANs, cards and payments through licensed banking partners.
What Services Do Crypto Banks Offer?
The exact list depends on the license, but a typical crypto bank offers:
- Fiat and crypto accounts in one app, with multi-currency balances.
- Buying, selling and converting crypto and stablecoins.
- Custody of digital assets, from retail wallets to institutional vaults.
- Payments and transfers over bank rails and blockchains.
- Debit or prepaid cards that spend from fiat or converted crypto balances.
- For some providers: staking, crypto-backed loans or tokenized assets, where regulation allows.
Crypto Banks vs Traditional Banks
| Traditional banks | Crypto banks | |
|---|---|---|
| Assets | Fiat money | Fiat plus crypto and stablecoins |
| License | Banking license | Banking, trust, e-money, payment or crypto license, or a licensed partner |
| Deposit protection | Deposits covered by national insurance schemes up to a limit | Crypto holdings are not covered by deposit insurance |
| Settlement | Business days on many rails | Minutes on blockchains, around the clock |
| Lending | Core business | Limited, depends on license |
| Access | Mostly domestic | Often cross-border through one app |
Are Crypto Banks Safe?
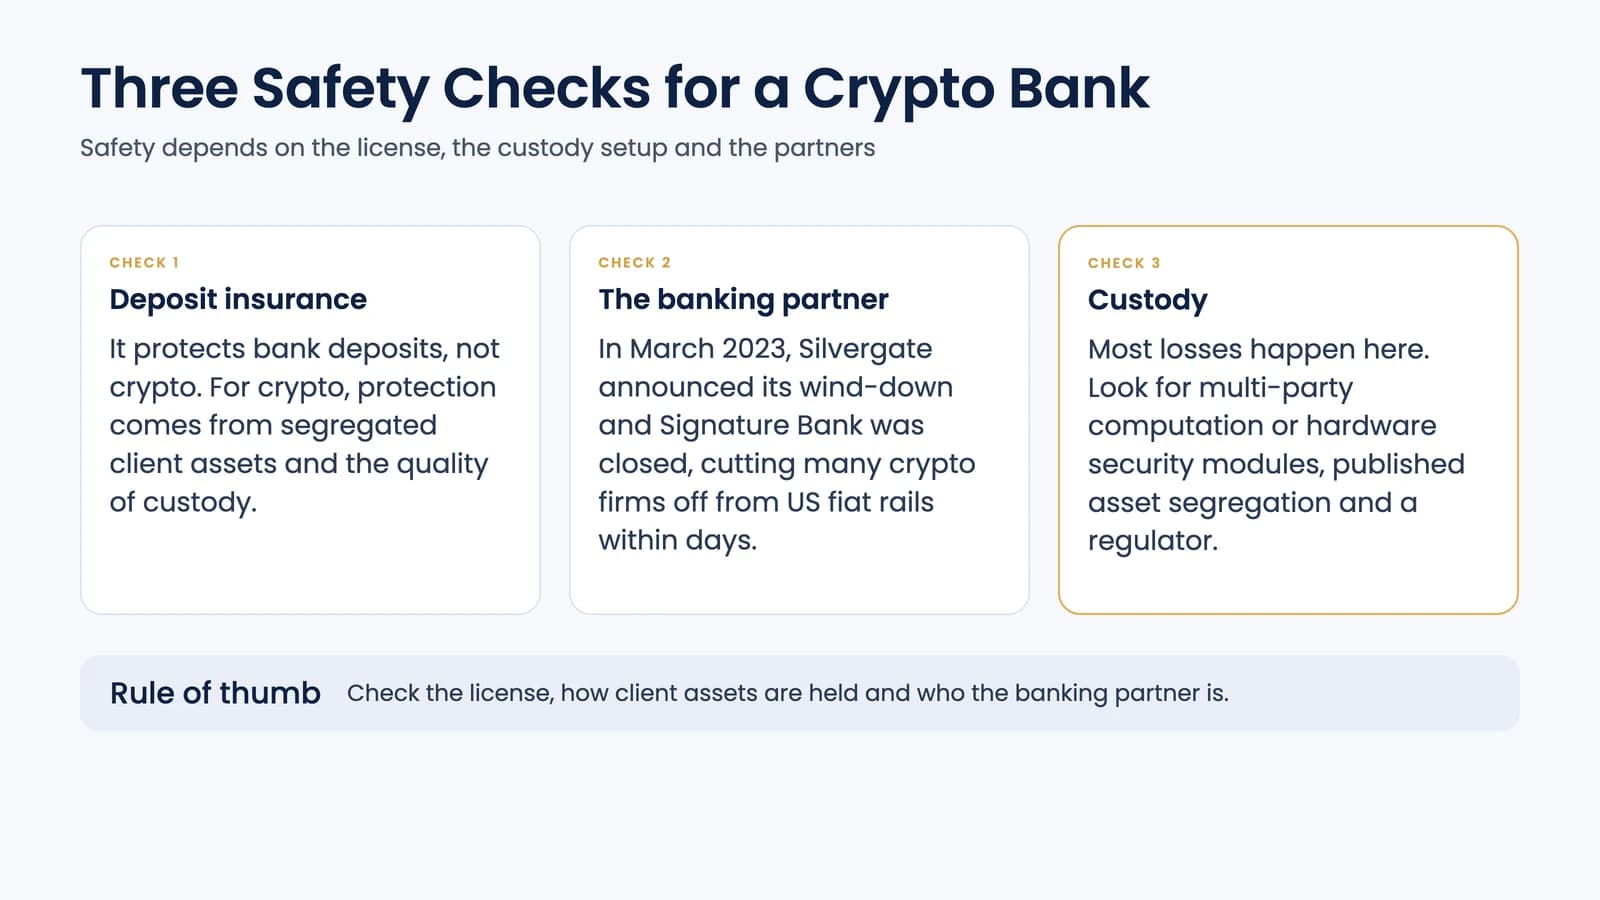
Safety depends on the license, the custody setup and the partners. Three points are worth checking.
First, deposit insurance protects bank deposits, not crypto. If a crypto bank holds customer crypto, the protection comes from segregation of client assets and the quality of its custody, not from a government scheme.
Second, the banking partner matters. In March 2023, Silvergate announced its wind-down and Signature Bank was closed, cutting many crypto firms off from their main US fiat rails within days.
Third, custody is where most losses happen. Look for providers that use multi-party computation or hardware security modules, publish how they segregate assets, and are supervised by a regulator.
How Crypto Banks Are Regulated in 2026
Regulation has moved from uncertainty to detailed rules in the main markets:
- European Union. MiCA has applied in full since 30 December 2024. Crypto service providers need authorization, and transitional periods under old national regimes ended by 1 July 2026 at the latest. Banks can offer crypto services after notifying their regulator.
- United States. Regulators withdrew their restrictive 2022–2023 guidance in 2025, the GENIUS Act created a federal framework for payment stablecoins, and the OCC is granting trust charters to crypto firms.
- United Kingdom. The FCA’s new crypto regime opened for applications on 30 September 2026 (firms should apply by 28 February 2027) and is expected to take effect in October 2027.
Our overview of license types for fintech and crypto explains which license covers which service.
Competitors or Allies?
For years, crypto banks were pitched as a replacement for traditional banks. That has not happened, and it is unlikely. What is happening is convergence. Banks add crypto custody and stablecoin payments; crypto firms apply for bank and trust charters; neobanks sit in between. Customers get one app for both kinds of money.
The same logic applies to new money formats. Banks are testing tokenized deposits while fintechs build on regulated stablecoins; our comparison of stablecoins and deposit tokens explains how the two differ.
Trends to Watch
- Stablecoin payments. Regulated stablecoins are becoming a settlement rail for cross-border payments and business accounts.
- Bank-grade crypto charters. More crypto firms seek bank or trust licenses, and more banks launch crypto services.
- Tokenized assets. Crypto banks are adding access to tokenized funds, bonds and gold, a market covered in our guide to real-world asset tokenization.
- Compliance by design. Travel Rule data, blockchain analytics and proof of segregated assets are now standard requirements, not extras.
Building a Crypto Bank with 4IRE
4IRE builds crypto banking products for fintechs, neobanks and banks. Our white-label crypto banking software provides a ready base with custodial wallets, KYC integrations, cards and an admin panel, and our team handles crypto banking software development for custom features and integrations. If you are exploring the model, we can help you choose the license route and architecture that fit your market.
FAQ on Crypto Banks
Crypto banks are financial institutions or platforms that combine banking features, such as accounts, cards and transfers, with services for digital assets, such as custody, trading and stablecoin payments. Some hold banking licenses; others work under e-money, payment or crypto licenses, or with a licensed partner bank.
Traditional banks work with fiat money, take insured deposits and lend them out. Crypto banks add digital assets and blockchain settlement. Crypto holdings are not covered by deposit insurance, so customers rely on the provider’s license, custody and segregation of client assets.
In the main markets, yes. In the EU, crypto services need authorization under MiCA. In the US, crypto firms operate under state licenses, trust charters or partner banks. The UK is introducing a full crypto regime expected to take effect in October 2027.
Yes. Banks can add crypto custody, trading or stablecoin payments as a module in their existing app, subject to their regulator’s rules. In the EU, a bank must notify its regulator before it starts providing crypto services.
Yes. You can build from scratch or start from a white-label platform and customize it. The 4IRE team helps choose the license route, integrates KYC, custody and banking partners, and hands over IP rights with a source-code license.