

 Bank

Building a neobank from scratch means building a ledger, accounts, cards, payments, KYC and a back office before the first customer signs up. White-label solutions let you skip much of that work: you license a ready platform or module, brand it, and put your effort into the niche and the customer experience.
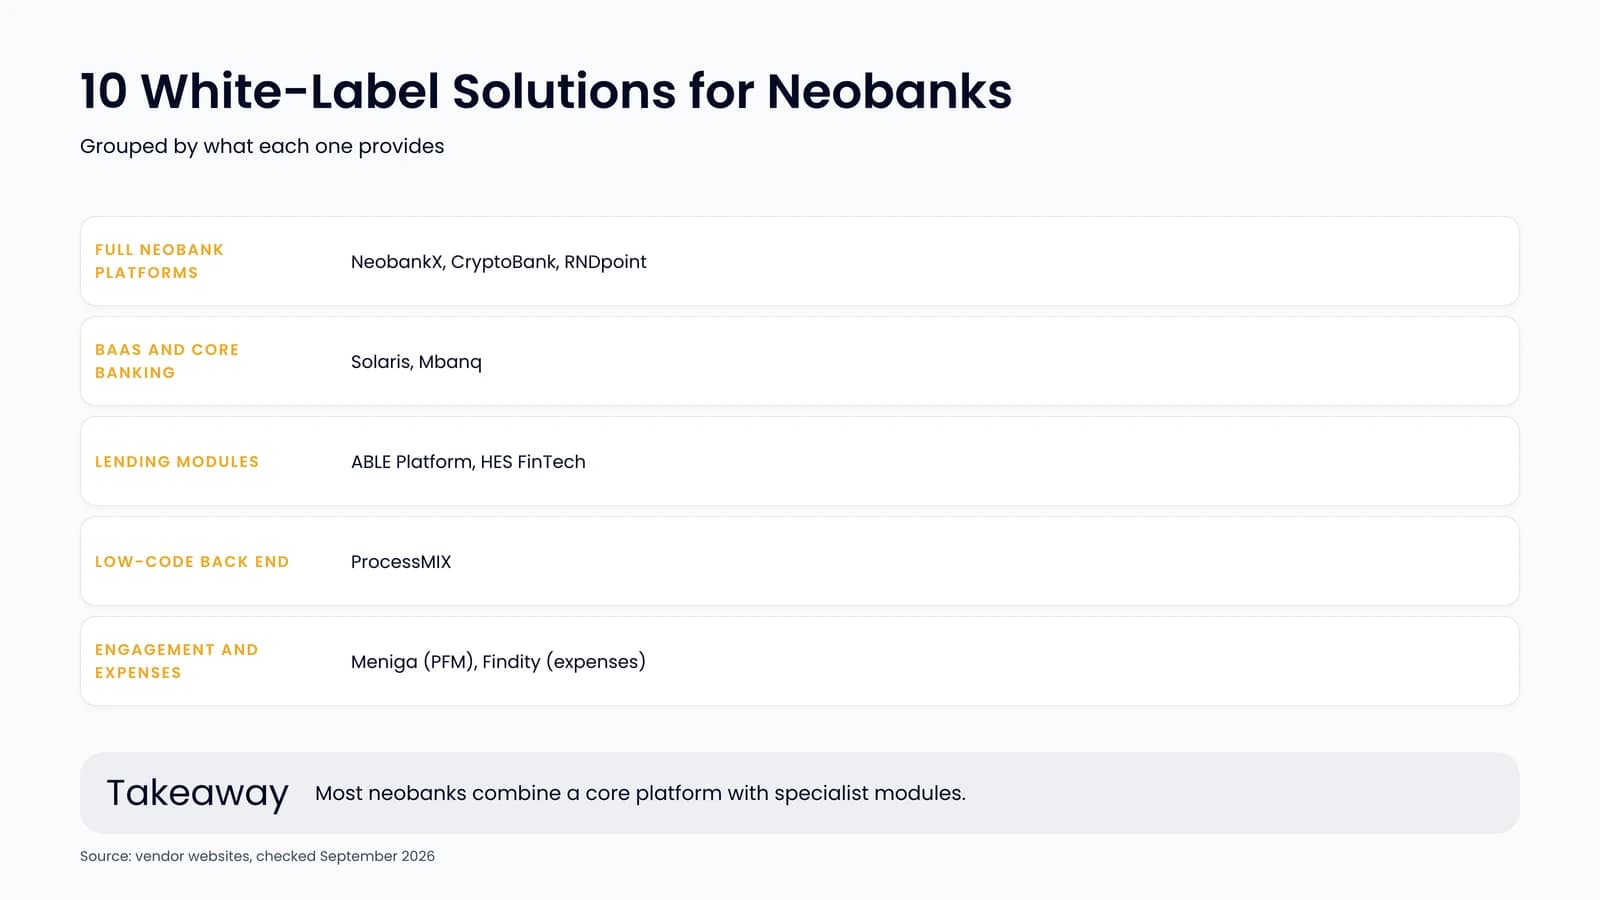
This list covers 10 white-label solutions for neobanks, from full platforms to specialist modules for lending, personal finance and expenses. We checked each vendor’s current website in September 2026 and kept only claims the vendors state themselves. Disclosure: NeobankX and CryptoBank are 4IRE products, and ABLE Platform and ProcessMIX were founded by one of RNDpoint’s leaders.
What Is White-Label Banking?
A white-label banking solution is software built by one company and sold to another, which runs it under its own brand. End customers see your app and your brand; the vendor’s technology works underneath.
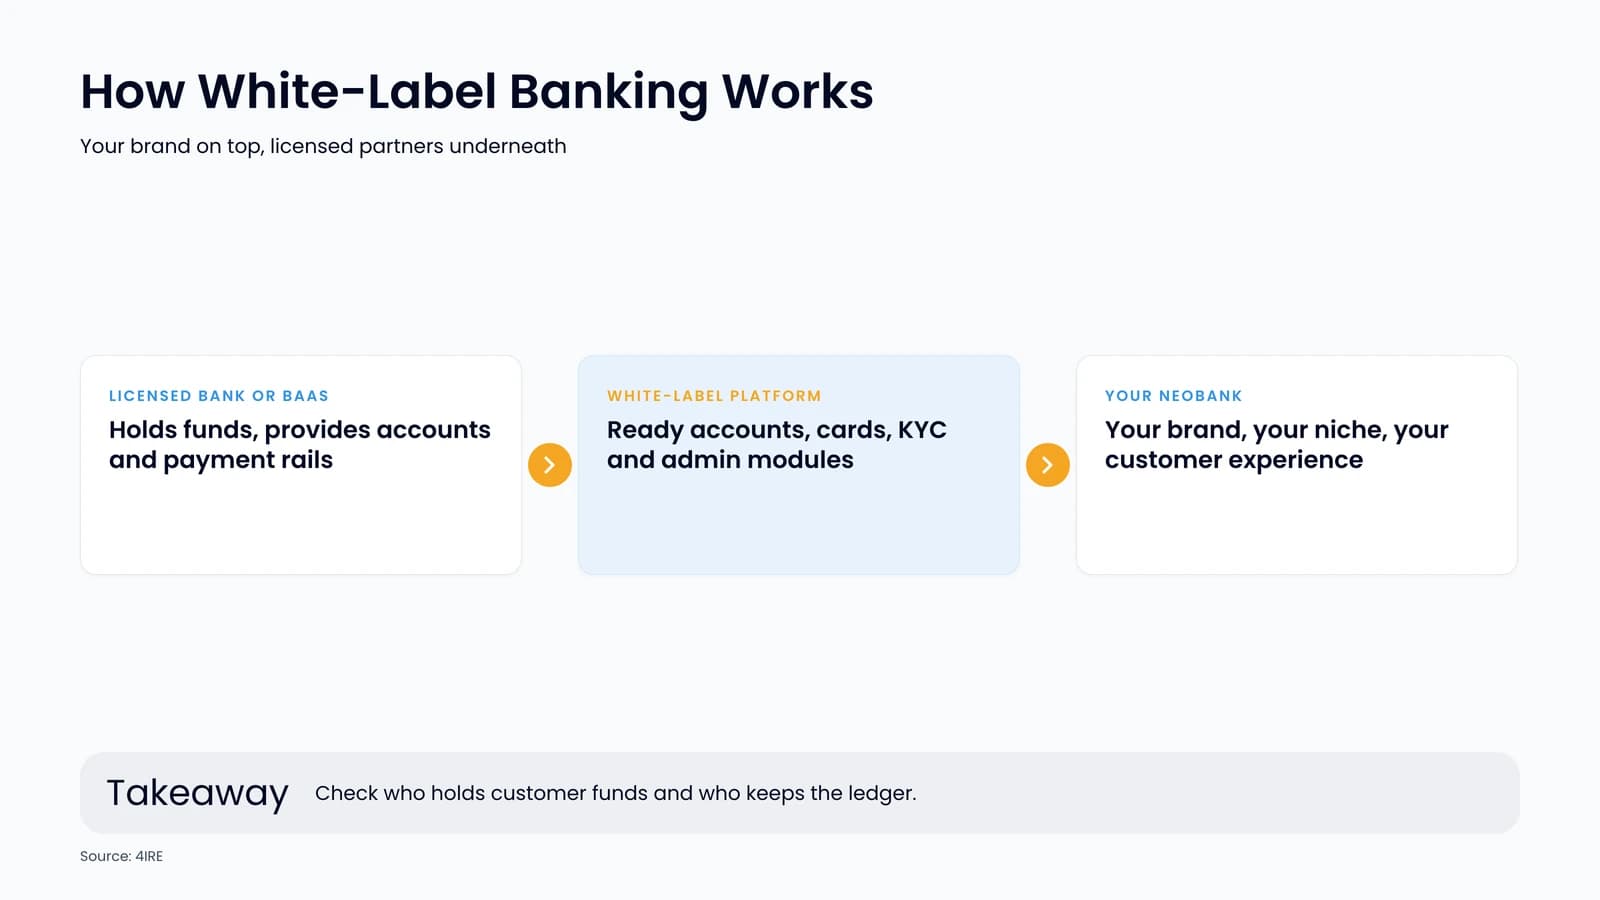
It sits next to two related ideas. Banking-as-a-service (BaaS) gives you access to a licensed bank’s accounts and rails through APIs. Open banking lets licensed third parties access account data and initiate payments with the customer’s consent; our guide to open banking APIs covers that layer. A white-label platform often combines both: ready software on top, licensed partners underneath.
Why Neobanks Use White-Label Platforms
The main reasons are speed and focus. A white-label platform shortens the build from many months to a few, reduces the size of the engineering team, and brings tested modules for KYC, cards and reporting.
The trade-offs are real. You depend on the vendor’s roadmap, pricing and uptime, and on its banking partners. The 2024 collapse of Synapse, a US BaaS middleware firm, left end users of several fintech apps unable to reach their money for months. Before you sign, check who holds customer funds, who keeps the ledger, and whether you can get the source code or migrate your data. Our guide on how to start a neobank explains how this choice fits the licensing decision.
The 10 Best White-Label Solutions for Neobanks
1. NeobankX by 4IRE
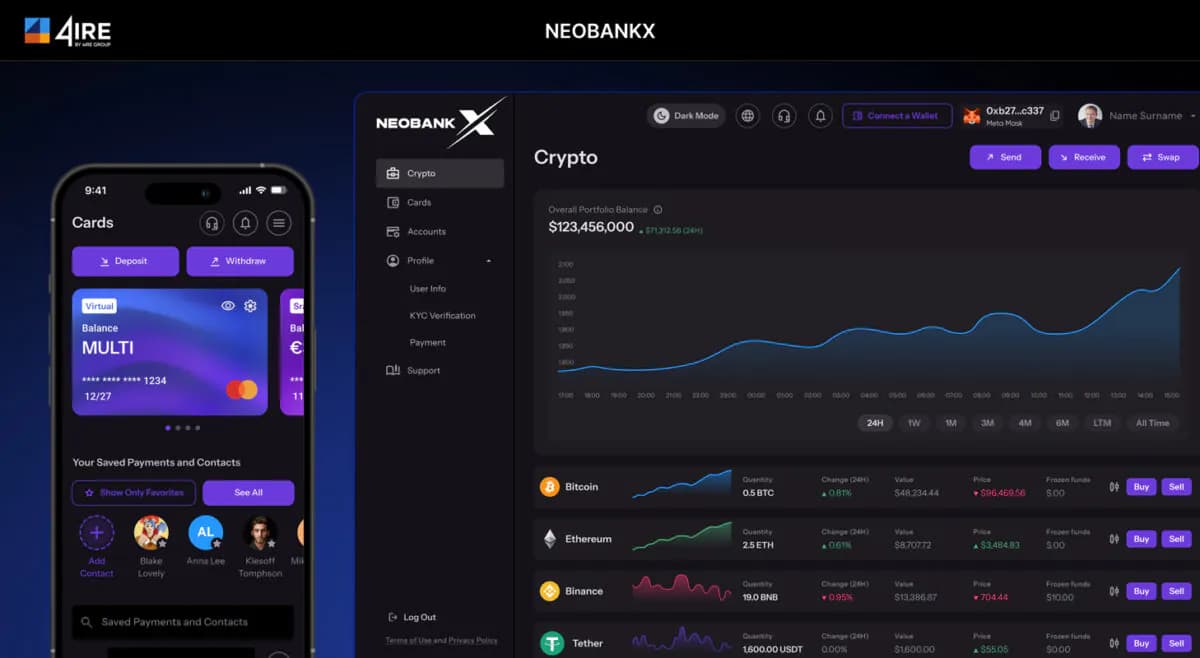
NeobankX is a white-label neobank platform with a web app, mobile app and back-office admin panel. It runs fiat and crypto operations on a single core system, covering deposits, swaps, card issuing and cross-border payments, and includes a custodial wallet. KYC and AML run through providers such as Onfido and Shufti Pro. 4IRE quotes about four weeks for a typical launch, or 2–3 months with customization, and hands over IP ownership with a source-code license.
2. CryptoBank by 4IRE
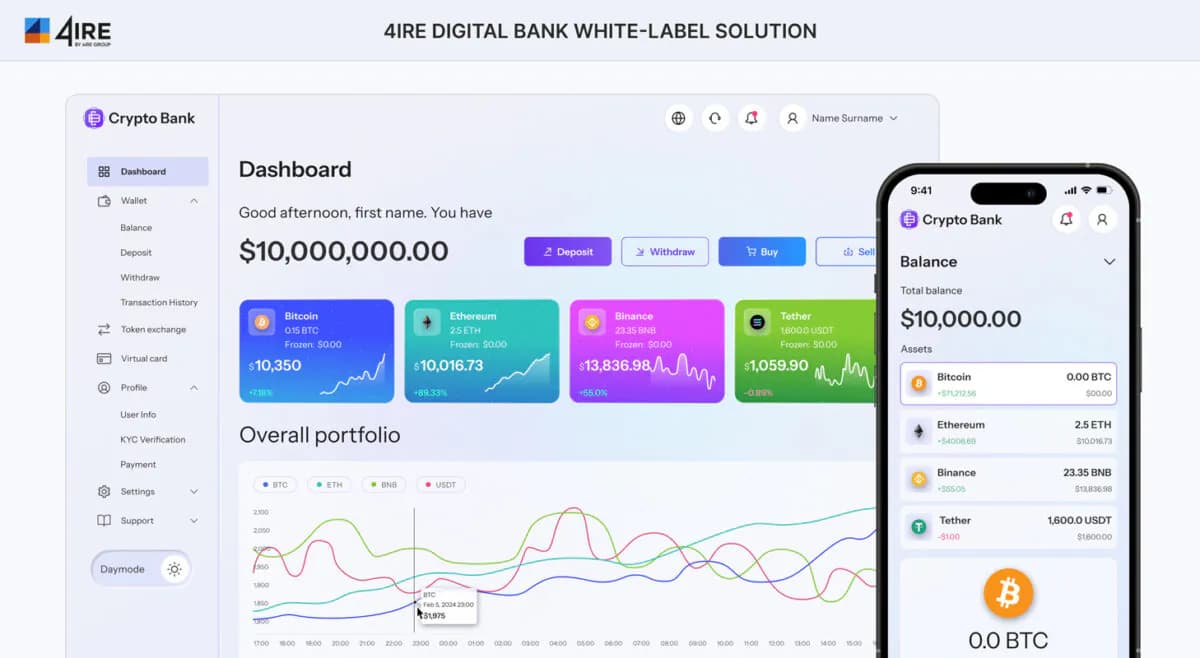
CryptoBank is 4IRE’s white-label crypto banking software for neobanks and fintechs that want digital assets alongside fiat. It includes a web and mobile app with a custodial wallet and exchange interface, virtual payment cards, Google Pay and Apple Pay support, KYC through Onfido, Ondato or Shufti Pro, and an admin dashboard for fees and transaction monitoring. Clients get a source-code license. Our guide on how to build a crypto bank explains where it fits.
3. Solaris
Solaris is a Berlin-based banking-as-a-service provider with a full German banking license. Through APIs, partners can embed accounts, debit, prepaid and credit cards, SEPA and instant payments, consumer lending and KYC or KYB onboarding. Japan’s SBI Group became its majority shareholder after a €140 million funding round in February 2025, so check the partner terms and roadmap during due diligence.
4. Mbanq
Mbanq provides a proprietary, cloud-native core banking platform with banking-as-a-service, card issuing and mobile banking. It can also run the operations behind a program as managed services, including KYC and AML, license acquisition, payment processing, lending and customer support, and it processes stablecoin transactions natively.
5. Meniga
Meniga builds white-label personal finance and data tools for banks: transaction categorization and enrichment, insights, savings features, cashflow forecasting and carbon footprint tracking. Its clients include UOB’s TMRW digital bank and UniCredit. For a neobank, Meniga is a module that adds engagement features on top of an existing core.
6. ABLE Platform
ABLE Platform is a lending automation suite covering loan origination, loan management, credit scoring, debt collection and BNPL. It is low-code, runs as SaaS or on-premises, and the vendor quotes 1–3 months to automate loan origination. It suits neobanks that plan to add credit; our article on credit scoring systems covers the decisioning side.
7. HES FinTech
HES FinTech offers LoanBox, an end-to-end lending platform for consumer and commercial credit, from onboarding and origination to servicing and collection. It supports products such as BNPL, SME loans, factoring and leasing, includes AI credit decisioning through GiniMachine, and can be deployed in the cloud, on-premises or in a hybrid setup.
8. ProcessMIX
ProcessMIX is a low-code platform for financial services that combines workflow automation, business rules and machine learning decisioning. Teams use it to build back-end logic for onboarding, lending and risk checks, and it can run in a private or public cloud or on-premises, including private generative AI models on the customer’s own data.
9. Findity
Findity provides white-label expense management that banks, card issuers and accounting platforms embed under their own brand. It covers receipt capture, AI-assisted expense processing and local tax rules, works with Visa and Mastercard cards, and says a white-label expense app can launch in as little as 12 weeks. It fits neobanks that serve SMEs.
10. Skaleet
Skaleet is a modular, SaaS core banking platform that banks, neobanks, PSPs and BaaS providers use to launch and run branded banking products, hosted in EU data centers with an API-first, event-driven architecture. The vendor is ISO 27001 certified, quotes 99.99% availability and a 4–6 month implementation, and was named Best Core Banking Solution at the Euromoney Awards for Excellence 2026. Clients include Caisse d’Epargne and eZyness, a La Banque Postale subsidiary.
How to Choose a White-Label Neobank Solution
Start from your niche and licensing route, then check each vendor against a short list:
- Licensing fit. Does the platform work with your license or partner bank, in your markets? Our overview of fintech license types helps map this.
- Ledger and data ownership. Who keeps the books, and can you export everything?
- Code and exit terms. Source-code access or escrow, and migration support if you leave.
- Compliance coverage. KYC, monitoring, reporting and security certifications relevant to your regulator.
- Customization. Which parts you can change yourself and which need the vendor.
- Total cost. Setup fees, per-account pricing and the cost of your own team.
A white-label core rarely covers everything. Most neobanks combine a platform with specialist modules and a custom mobile banking app layer where they want to stand out.
The Bottom Line
White-label solutions are the fastest practical route to a neobank launch, but they move risk rather than remove it. Choose a vendor whose licensing model, ledger and exit terms you understand, and plan which parts of the product you will own.
The 4IRE team builds neobanks on NeobankX and CryptoBank and extends them with custom development. If you are comparing options, talk to us about your market, licensing route and timeline.
FAQ on White-Label Solutions for Neobanks
It is ready-made banking software, such as accounts, cards, KYC and an admin panel, that a company licenses and runs under its own brand. It lets a neobank launch without building every component from scratch.
The software part can take a few months. For example, 4IRE quotes about four weeks for a typical NeobankX launch, or 2–3 months with customization. Licensing and partner onboarding often take longer, so start them in parallel with the build.
BaaS gives you access to a licensed bank’s accounts and payment rails through APIs. White-label banking gives you ready software, such as apps and a back office, under your brand. Many neobanks use both.
They can be, but security depends on the vendor. Ask for relevant certifications such as ISO 27001 and PCI DSS, penetration test results, and clear answers on who holds customer funds and keeps the ledger.
Yes. Platforms such as NeobankX and CryptoBank combine fiat accounts with custodial crypto wallets and trading. Offering crypto services also requires the right license, such as MiCA authorization in the EU.