

 Blockchain Use Cases
Insurance runs on shared information that nobody fully shares. A single commercial policy can involve a broker, a lead insurer, several co-insurers and reinsurers, each keeping its own copy of the policy, the premium and the claims. Much of that data is still re-keyed by hand, and every mismatch between copies turns into a reconciliation task or a dispute.
Blockchain offers insurers a shared, tamper-evident record of policies and claims and smart contracts that can pay out automatically when agreed conditions are met. This article looks at the insurance use cases where that is practical today, what the industry learned from its first blockchain consortium, and how to approach a project in 2026.
The Problems Blockchain Targets in Insurance
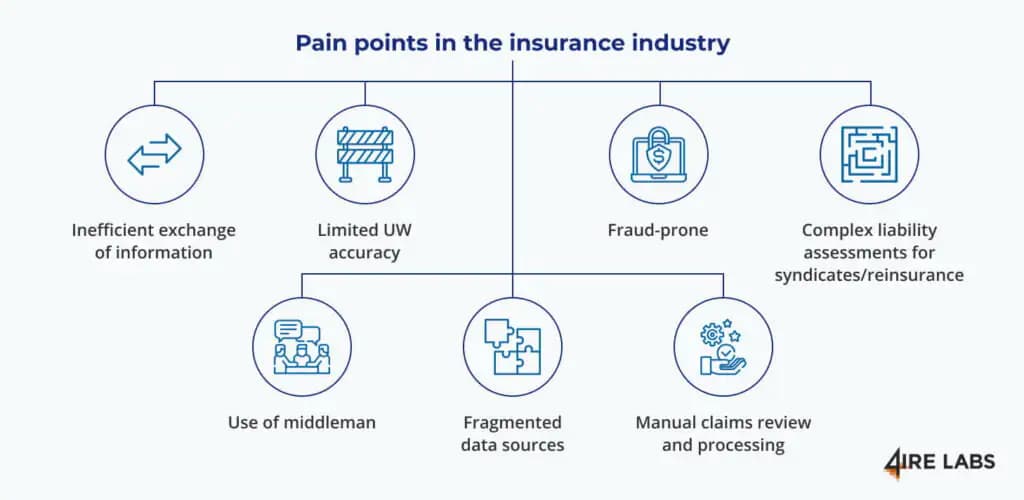
- Slow information exchange. Brokers, insurers and reinsurers pass the same data back and forth, often as documents and spreadsheets.
- Manual claims handling. Claims are checked by hand against policy terms and third-party evidence, which is slow and expensive for small claims.
- Fraud and duplicate claims. The same loss can be claimed from several insurers, because no insurer sees the others' claims.
- Complex reinsurance accounting. Working out who owes what across layers and syndicates takes time and generates disputes.
- Underinsured markets. High admin cost per policy makes small policies in developing markets uneconomic.
Supervisors see the same picture. The European Insurance and Occupational Pensions Authority (EIOPA) consulted the market in 2021 through a discussion paper on blockchain and smart contracts in insurance, covering both the benefits and the risks of the technology from a supervisory point of view.
Blockchain Use Cases in Insurance
Parametric Insurance
Parametric insurance is the clearest fit. Instead of assessing the actual loss, the policy pays a fixed amount when a measurable event happens: an earthquake above a set magnitude in a defined area, rainfall below a threshold during a growing season, a flight delayed by more than a set time. A smart contract holds the terms, an oracle supplies the event data, and the payout goes out automatically, with no claim form and no adjuster.
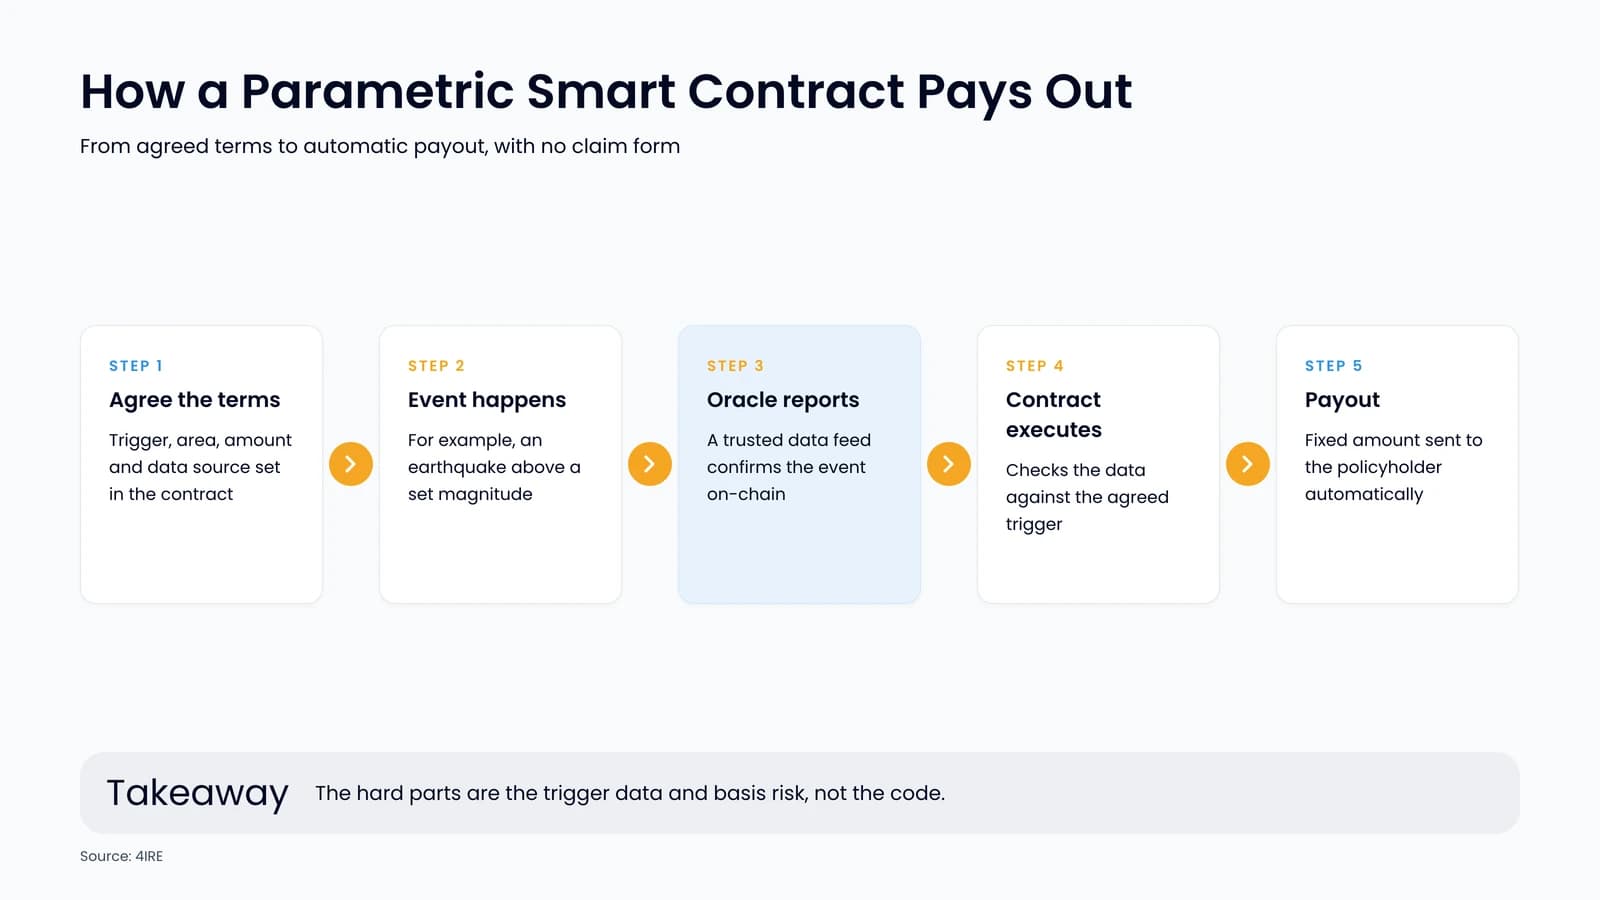
The hard parts are not the code. You need a trusted data source for the trigger, a clear definition of the event, and a way to manage basis risk, the gap between what the index pays and the loss the customer actually suffers. Payouts in stablecoins can reach customers in minutes, but only where the insurer is allowed to pay that way; our stablecoins guide covers the regulatory side.
Claims Automation and Fraud Checks
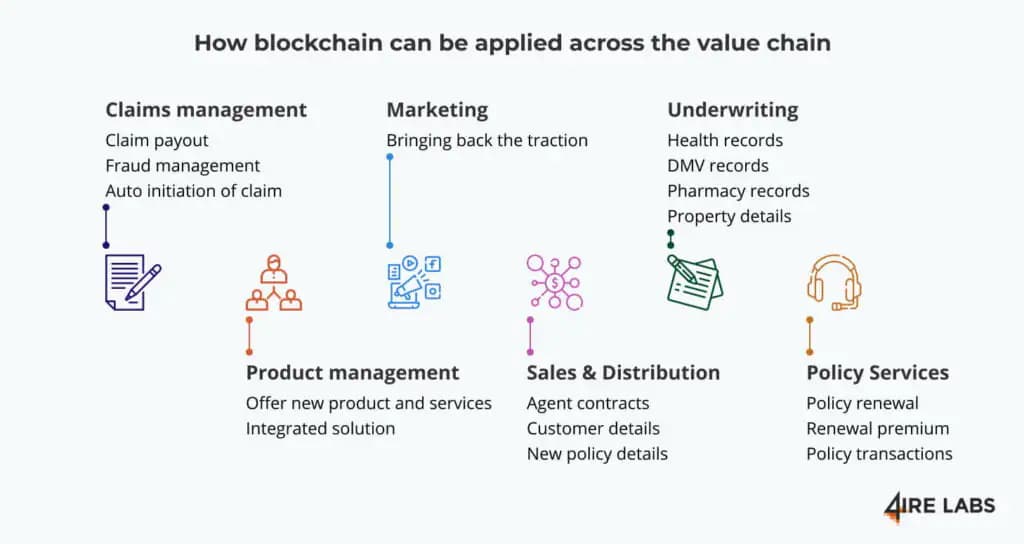
A shared claims registry lets insurers check whether an asset or loss has already been claimed elsewhere, using hashes and identifiers rather than exposing customer data. The same record gives every party to a claim, the insured, the insurer, the repairer and the assessor, one view of its status and evidence.
Reinsurance and Co-Insurance
When a primary insurer and its reinsurers work from one record of premiums, exposures and claims, settlement no longer depends on each side reconciling its own spreadsheets. This is the problem the industry's best-known blockchain consortium set out to solve, and why its fate matters.
Underwriting Data
Underwriters rely on data held by others: vehicle and property records, health data, previous claims, sensor readings. A permissioned ledger can record who shared which data, when and with what consent, so an insurer can use verified records without building a copy of every source. The same consent trail helps with data protection audits, because it shows exactly which party accessed what.
Policy Records and Proof of Cover
A policy held as a digital record, or a token, can be checked instantly by a landlord, a car rental company or a border authority without calling the insurer. Tokenized policies can also be transferred or resold where the product and the regulator allow it.
Micro-Insurance and Peer-to-Peer Cover
Lower admin costs make small policies viable, and pooled cover can be run by smart contracts with transparent rules for contributions and payouts. These models still need a licensed risk carrier and proper capital; blockchain changes the admin cost, not the regulation.
What the Industry Learned from B3i
B3i, the Blockchain Insurance Industry Initiative, was founded in 2016 by major insurers and reinsurers to build shared infrastructure for the market. It announced in July 2022 that it had filed for insolvency after failing to raise new capital. Several trade finance consortia met a similar fate in 2022 and 2023; we cover that story in our article on blockchain in trade finance.
The pattern is the same in both industries. A platform that needs the whole market to join before anyone benefits struggles to survive. Projects that work start with a product one company can launch and sell on its own, such as a parametric cover, then connect to partners through standard data formats.
It also helps to separate the technology decision from the business model. A shared ledger among five reinsurers is a governance project first: who runs the nodes, who pays, who can see which data and how disputes are settled. Those questions took the old consortia years. A product-led project can answer them for a small group of partners and grow the network only when the product earns it.
How to Start a Blockchain Insurance Project
- Pick a product, not a platform. A single parametric cover or a claims registry with a few partners is easier to launch and measure.
- Choose the ledger for your counterparties. Known insurers and reinsurers usually point to a permissioned network; see our review of permissioned blockchain frameworks. Open products sold to the public may run on a public chain.
- Secure the data feeds. Oracles for weather, seismic or flight data decide whether payouts are right. Use more than one source where you can.
- Keep personal data off-chain. Store hashes and references on the ledger and customer data in systems that meet privacy rules.
- Audit the contracts. A bug in a payout contract pays out real money. Plan an independent review; our guide to how to audit smart contracts explains the process.
- Involve compliance early. Licensing, capital rules and consumer protection apply whatever the technology.
How 4IRE Works with Insurers
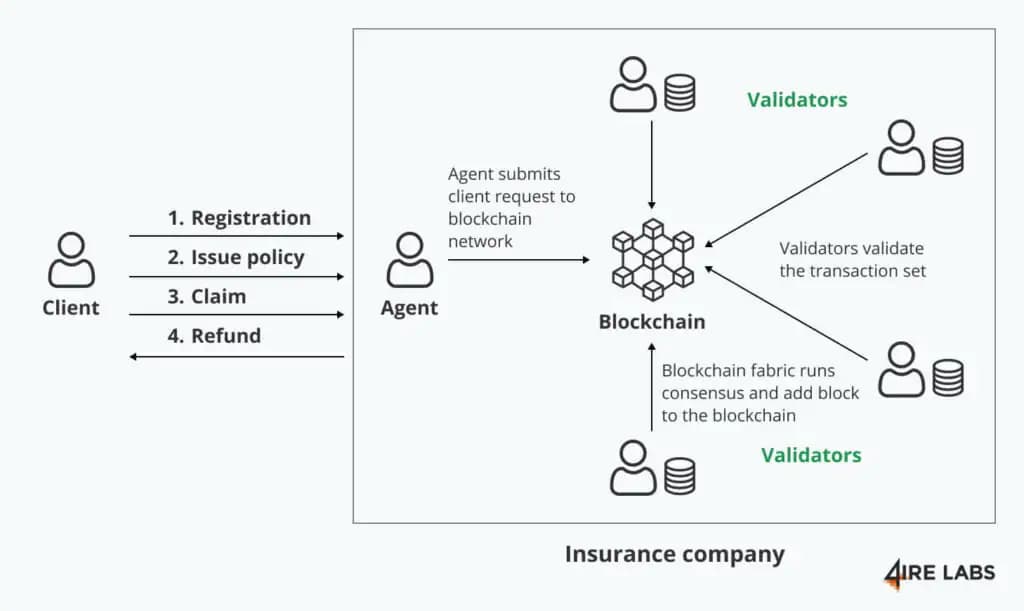
4IRE built ParametricX, a blockchain marketplace for natural disaster insurance, for InsurTech client Decentro. Users choose a location and a type of disaster, such as a hurricane or an earthquake. Their policy is tokenized as an NFT that can be resold, liquidity providers fund the cover, and parametric smart contracts handle collection and payouts. See this and related projects on our insurance industry page, and more cross-industry examples in our overview of blockchain use cases in business.
FAQ
The main uses are parametric insurance paid automatically by smart contracts, shared claims registries that help detect duplicate claims, one shared record of premiums and claims for reinsurers and co-insurers, and digital proof of cover that third parties can check instantly.
A policy that pays a fixed amount when a measurable event happens, such as an earthquake of a set magnitude in a defined area. A smart contract holds the terms, an oracle reports the event, and the payout is released automatically without a claims assessment.
B3i announced in July 2022 that it had filed for insolvency after failing to raise new capital. Like the trade finance consortia, it needed broad market adoption before it paid off, and the volumes did not arrive in time.
Yes. Whoever carries the risk still needs the relevant insurance licence and capital, and consumer protection and data privacy rules still apply. Blockchain changes how policies and claims are administered, not the regulatory status of the product.