

 Bank

A mobile wallet app lets people store money or payment credentials on their phone and use them to pay, transfer and get paid. Building one is less about the app screens than about three decisions underneath: whether you hold customer funds, which payment rails you connect to, and which regulator you answer to.
Demand is real. According to the World Bank's Global Findex 2025, nearly 80% of adults worldwide had a financial account in 2024, and 42% of adults in low- and middle-income countries made a digital merchant payment, up from 35% in 2021. About 900 million adults without an account already own a mobile phone. This guide walks through how to build a mobile wallet app, from wallet type and licensing to features, delivery steps and team.
What Is a Mobile Wallet App?
A mobile wallet is the digital version of a physical wallet: it holds cards, balances, loyalty cards and sometimes crypto assets, and lets users pay in a few taps. In practice there are four models:
- Pass-through wallets store tokenised versions of existing bank cards and pass payments through to the card network. They never hold money.
- Stored-value (e-money) wallets hold a balance that users top up, spend and send to each other. This is the model behind most fintech wallets.
- Closed-loop wallets work only with one merchant or platform, such as a retailer, transport operator or marketplace.
- Crypto wallets hold digital assets and stablecoins, either with the user holding the keys or with the provider holding them.
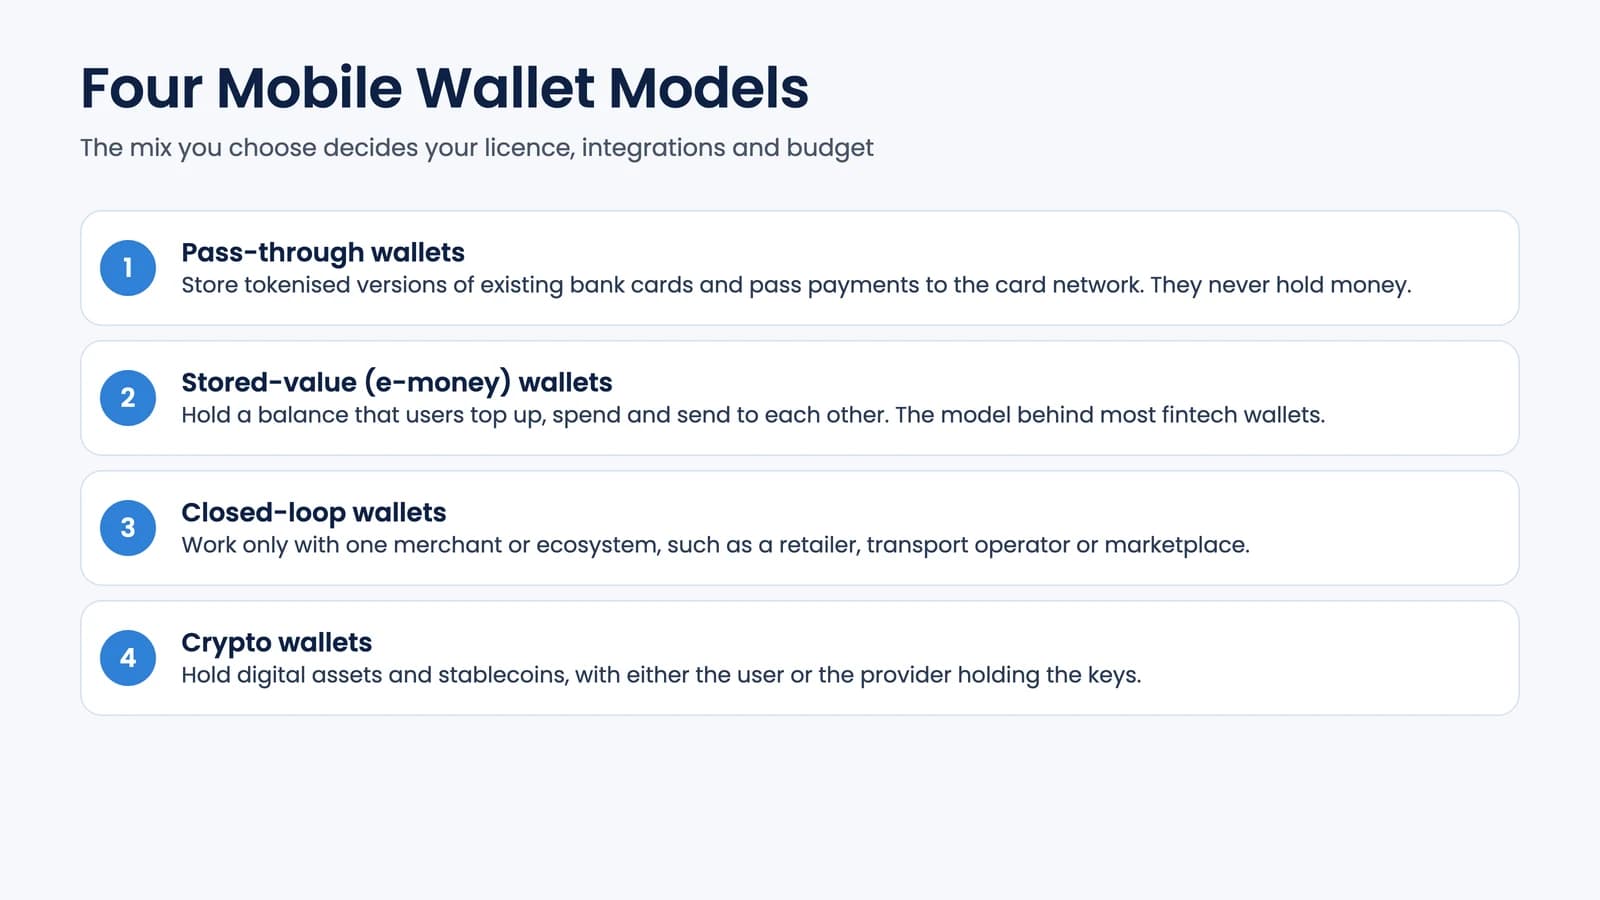
Many products combine models, for example a stored-value wallet with a card and a crypto module. The mix you choose decides your licence, your integrations and your budget.
Why Businesses Build Digital Wallets
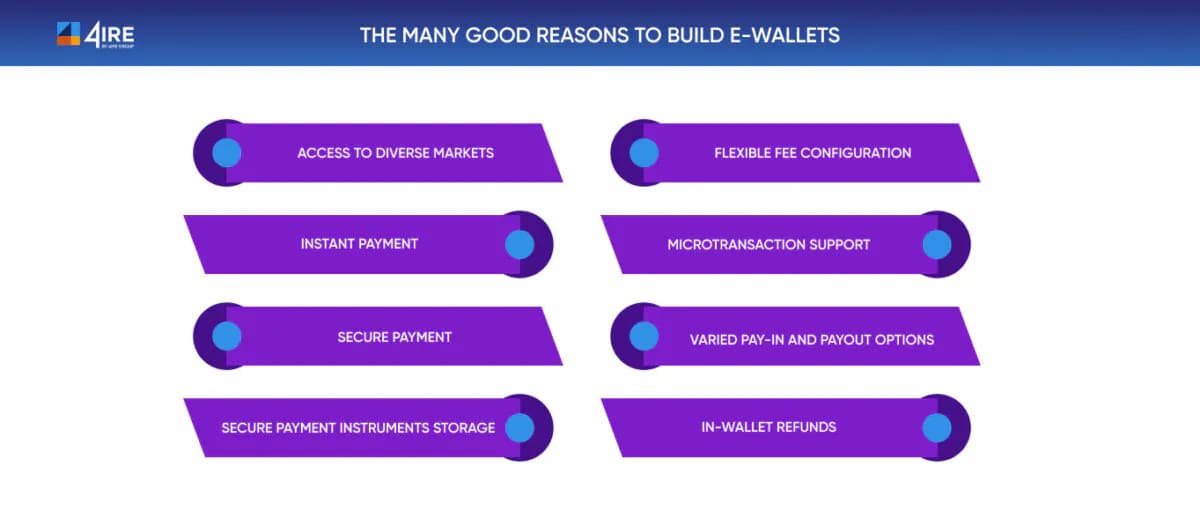
For a bank, fintech or platform, a wallet turns payments into an owned relationship. Users get instant transfers, cheaper cross-border payments and a clear view of their spending. The business gets transaction revenue, data to improve products and a channel for loyalty programmes, cashback and new services.
Step 1. Define the Wallet Model and Licence
Start with discovery: which users you serve, which payments they struggle with, and what existing apps do badly. Then answer the question that shapes everything else: will you hold customer money?
If you do, you need an e-money or payment institution licence, or a licensed partner. Our overview of fintech and crypto licence types covers EMI, PSP and crypto licences. Every model also needs KYC and AML controls, data protection under GDPR or its local equivalent, and PCI DSS compliance if you handle card data.
Watch where the rules are heading. In the EU, the Council and Parliament reached a provisional agreement on a new Payment Services Regulation and PSD3 in November 2025. It makes providers check that a payee's name matches the account identifier and, in some cases, liable for fraud losses when their fraud controls fall short. A wallet designed today should include payee verification and fraud monitoring from the start. A custodial crypto module in the EU needs authorisation under MiCA.
Step 2. Plan the Core Features
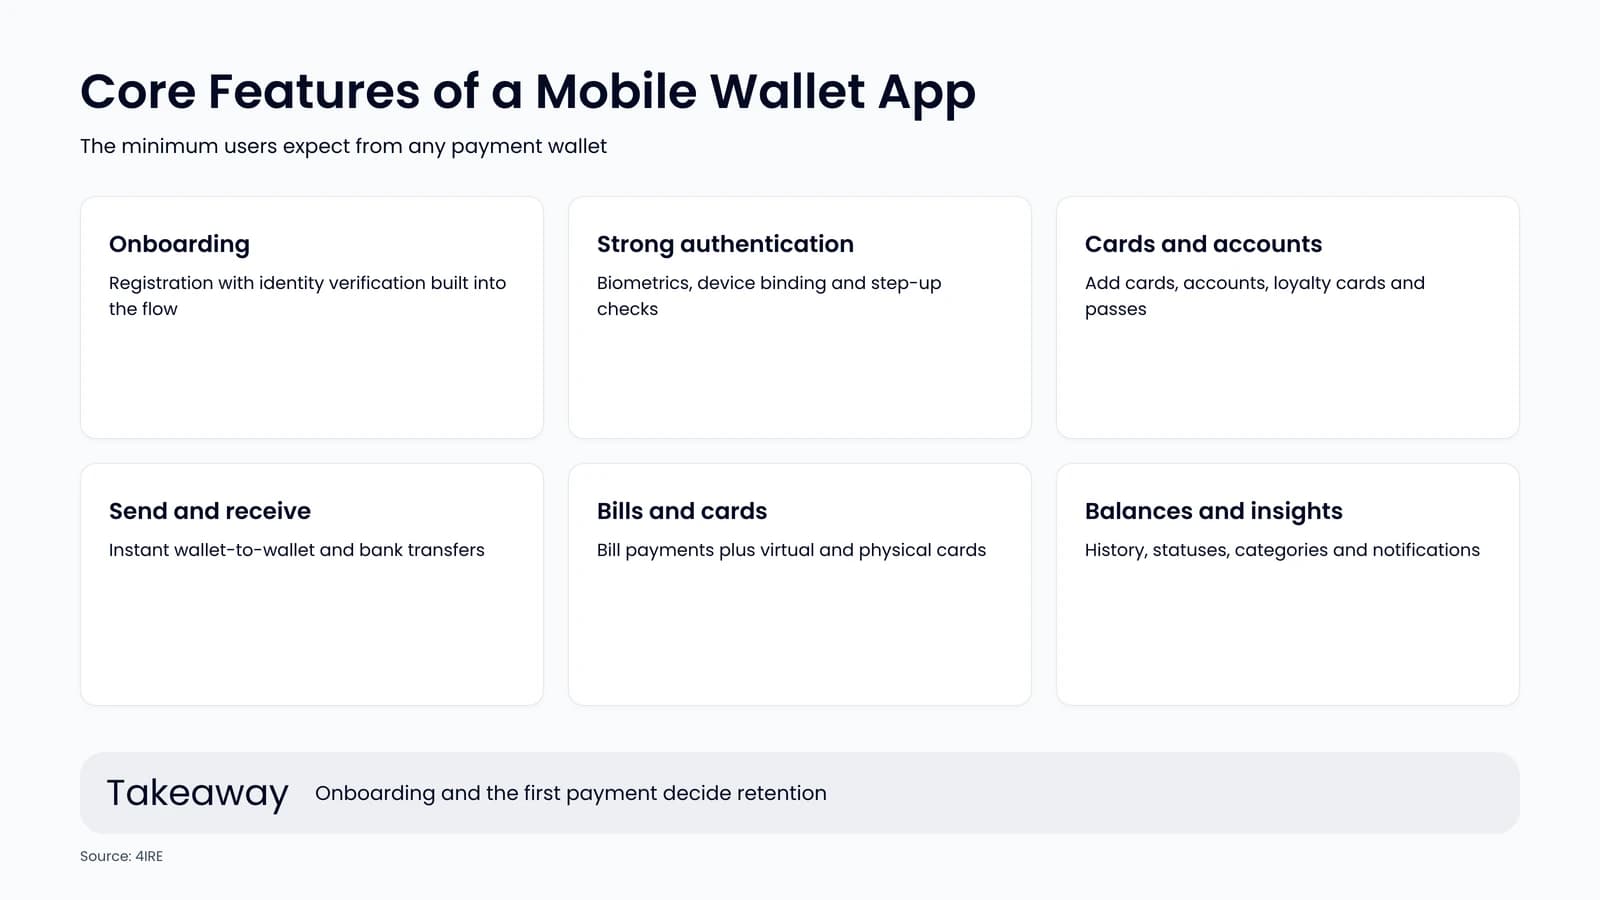
These features form the minimum users expect from any payment wallet:
- Registration and onboarding with identity verification built into the flow.
- Strong authentication: biometrics, device binding and step-up checks for risky actions.
- Adding cards and accounts, plus loyalty cards, vouchers and passes.
- Balances and transaction history with clear statuses and categories.
- Sending and receiving money, including instant wallet-to-wallet transfers.
- Bill payments for utilities and services in one place.
- Bank transfers for top-ups and withdrawals through partner banks.
- Virtual and physical cards to spend the balance anywhere cards are accepted.
- Spending insights and notifications.
For a closer look at the transfer flow, see our guide on how to build a P2P payment app.
Step 3. Choose Additional Features
Once the core works, add what sets you apart:
- Contactless payments. QR payments work on any phone. NFC tap-to-pay on iPhone used to be reserved for Apple Pay, but Apple now offers NFC access to third-party apps in the EEA from iOS 17.4 and, through its NFC & SE Platform, in the US, UK and a growing list of other countries. Both routes need an Apple entitlement and compliance with payment industry requirements.
- A crypto and stablecoin module for holding, sending or paying with digital assets. Our breakdown of crypto wallet development cost covers what this adds.
- An AI assistant for support, spending insights and budgeting tips.
- Cashback and rewards to drive engagement.
Step 4. Design the Architecture and Integrations
A wallet's back end matters more than its UI. At minimum it needs:
- A double-entry ledger that records every balance change exactly once.
- Payment rail integrations: card issuing and processing, instant bank transfers and, where relevant, open banking APIs for account-to-account payments.
- KYC, sanctions screening and transaction monitoring services.
- An admin back office for support, operations and compliance reporting.
Decide early between native iOS and Android development or a cross-platform framework, and which components you buy rather than build. White-label modules shorten time to market; custom code gives you control over the parts that differentiate you.
Step 5. Design, Prototype and Build
Build wireframes, then a clickable prototype, and test it with real target users before development starts. Onboarding and the first payment are the flows that decide retention, so design them first.
Development then runs in iterations: back end and ledger, mobile clients, integrations, then additional features. Keep releases small and demo them regularly.
Step 6. Secure and Test
Payment apps attract attackers. Build in TLS with certificate pinning, encryption of sensitive data at rest, secure key storage in the iOS Keychain and Android Keystore, code obfuscation, root and jailbreak detection, and rate limits on sensitive actions.
Before launch, run functional, security and load testing, an independent penetration test and a closed beta with real money. Regulators and partner banks will ask for the evidence.
Step 7. Launch and Grow
Launch in one market with one strong use case, measure activation and retention, then expand. Plan for operations from day one: customer support, fraud handling, regulatory reporting and regular releases.
The Team You Need
A small wallet project can start with a team of five or fewer; larger ones need more. The core roles are:
- Back-end and mobile developers (or full-stack engineers)
- A UX/UI designer
- A QA engineer
- A project or product manager
- A business analyst and compliance specialist for regulated features
How Much Does It Cost to Build a Mobile Wallet?
Cost depends on the wallet model, licensing route, number of markets, payment rails and how much you build from scratch. A white-label base reduces cost and time; a fully custom core increases both. Licensing and partner onboarding often take longer than development. A scoped discovery phase is the fastest route to a reliable estimate.
Trends Shaping Mobile Wallets
- Stablecoin payments moving from crypto apps into mainstream wallets.
- Embedded wallets inside marketplaces, games and super apps.
- Stronger fraud controls, driven by rules such as the EU's payee verification requirements.
- AI for support, personalisation and fraud detection.
- Wearables extending tap-to-pay beyond the phone.
Build Your Mobile Wallet with 4IRE
4IRE builds mobile banking and wallet apps for fintechs and banks, and crypto wallets for products that add digital assets. If you are still shaping the concept, our digital banking strategy workshop is a good place to start.
Build Your Mobile Wallet with 4IRE
Planning a payment or crypto wallet? Our team will help you choose the wallet model, licensing route and integrations.
FAQ on Building a Mobile Wallet App
Decide which users and payments you serve, whether the wallet will hold customer funds, and in which markets you will launch. These choices determine your licence, your partners and your budget, so settle them during a discovery phase before development starts.
If the wallet holds customer money, you need an e-money or payment institution licence or a licensed partner that holds one. Pass-through wallets that only tokenise existing cards have a lighter load, and custodial crypto features need their own authorisation, such as MiCA in the EU.
A small project can start with five people or fewer: back-end and mobile developers, a UX/UI designer, a QA engineer and a project manager. Regulated features add a business analyst and compliance expertise.
Combine strong authentication, secure key storage, encryption, fraud monitoring and regular independent penetration tests. Test every release before it reaches users, and run a closed beta with real money before launch.