

 Bank
To start a neobank in 2026, you need more than a polished mobile app. You need a niche that incumbents serve badly, a licensing model that lets you hold customer money legally, a core platform that keeps an exact ledger, and a compliance stack that satisfies regulators from day one. The app is the part customers see; the rest is what decides whether you can launch at all.
The market has proven the model. Nubank reached 139 million customers by the end of June 2026, and Revolut ended 2025 with 68.3 million retail customers. Both took years and heavy funding to get there. This guide walks through the decisions the 4IRE team works through with founders who want to launch a neobank, in the order they usually have to be made.
What a Neobank Is — and What It Is Not
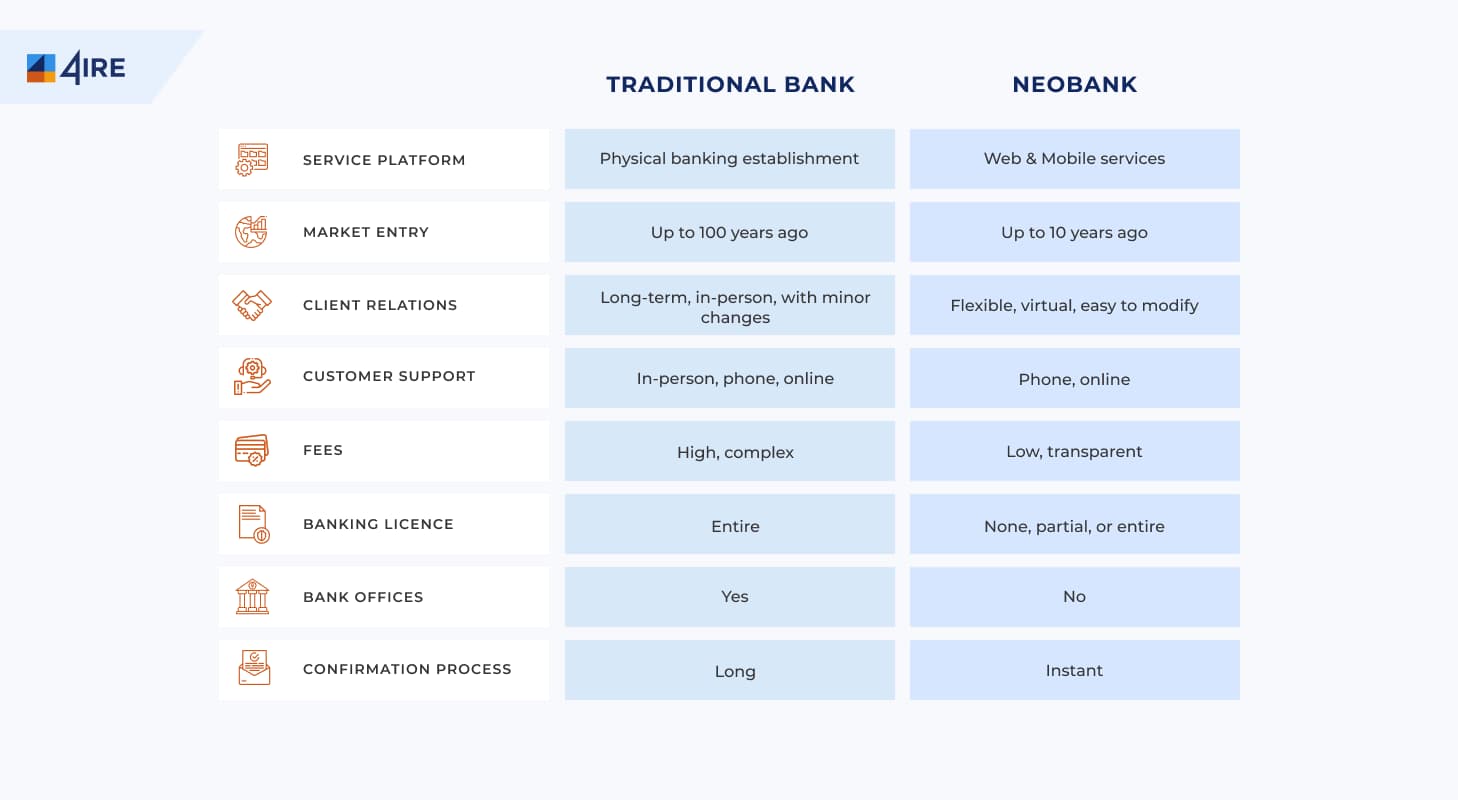
A neobank is a financial services provider that operates entirely through digital channels, with no branch network. It offers accounts, cards, payments and often savings or credit through a mobile or web app.
The word “bank” is misleading. Many neobanks are not banks at all: they hold an electronic money or payment institution licence, or they sit on top of a licensed partner bank. That distinction matters for customers, because e-money balances are safeguarded rather than covered by deposit insurance, and for founders, because it limits what you can offer. A non-bank cannot lend out customer deposits.
Step 1. Pick a Niche with a Real Gap
Most successful neobanks started narrow. Nubank attacked expensive credit cards in Brazil; Revolut started with cheap currency exchange for travellers. A general-purpose “better bank” is hard to fund and harder to market.
Useful questions at this stage:
- Which segment pays too much or gets rejected today: freelancers, SMEs, migrants sending remittances, crypto-active users, a faith-based community?
- Which single product will earn trust first: a card, a multi-currency account, credit, cross-border payments?
- Which jurisdiction will you launch in, and which will you expand to next?
- How will you make money: interchange, FX spreads, subscriptions, lending margin, or B2B fees?
The last question shapes the rest. If lending is your core revenue, you will need a credit scoring system and, eventually, a licence that allows it. Our case study on building a neobank like Plata shows how one credit-first neobank used its product choice to earn a full banking licence.
Step 2. Choose Your Licensing Model
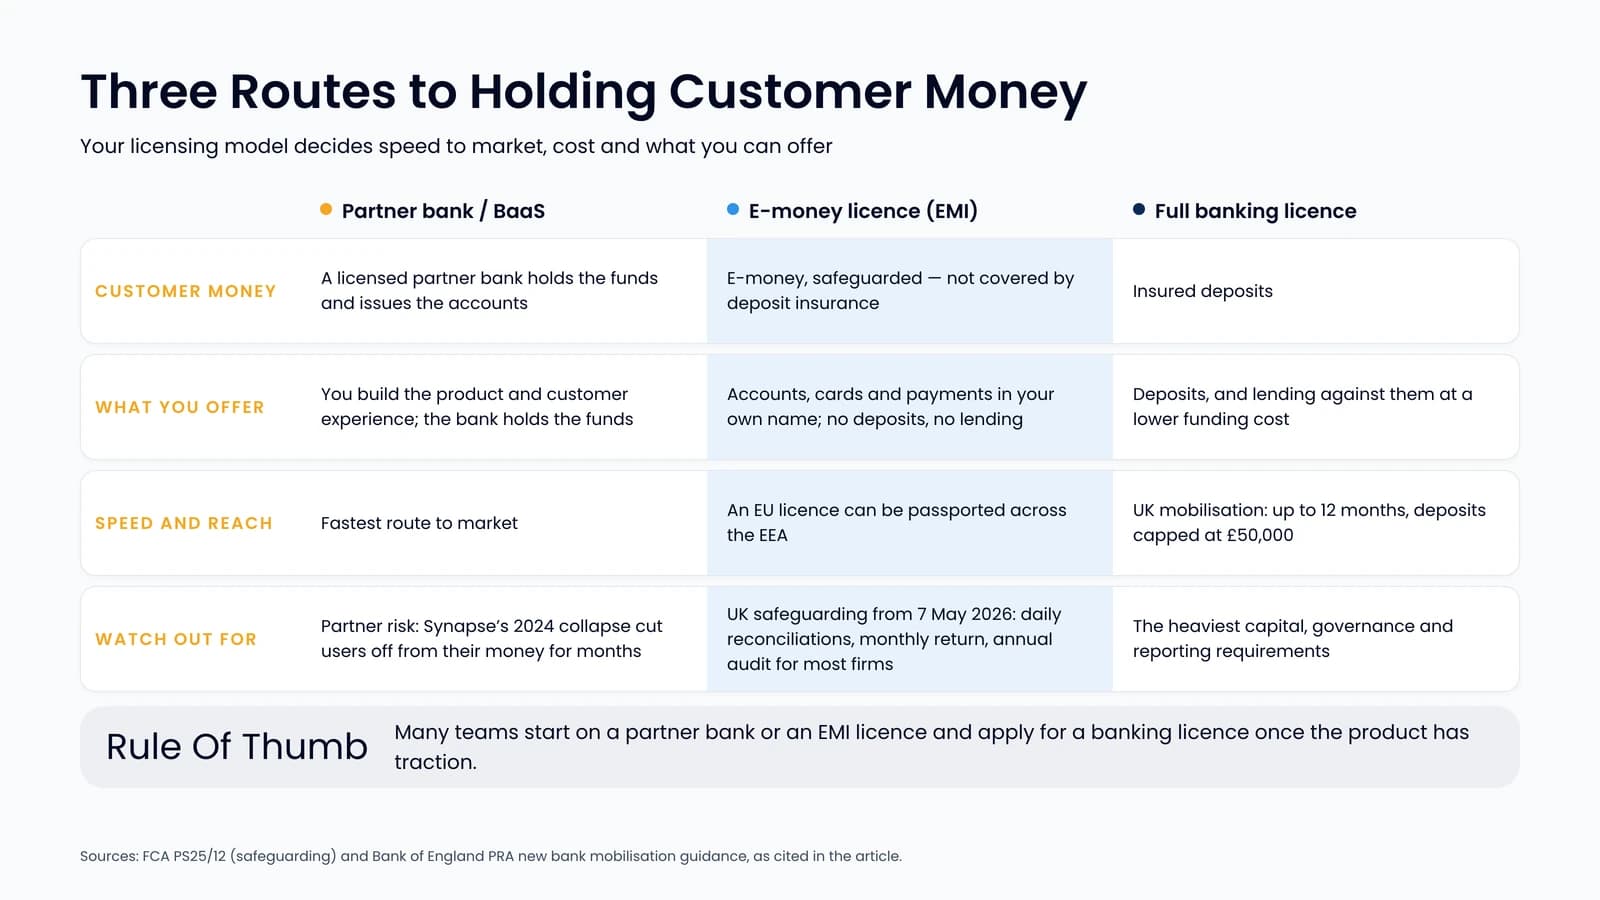
This is the decision that most affects cost and time to market. There are three common routes; our overview of types of fintech licences covers EMI, PSP and crypto licences in more detail.
Partner bank or BaaS provider
You build the product and customer experience; a licensed bank holds the funds and issues the accounts. This is the fastest route to market, but you depend on the partner’s risk appetite and pricing. The 2024 collapse of Synapse, a US banking-as-a-service middleware firm, showed the risk: when its ledger records broke down, end users of several fintech apps could not access their money for months. If you take this route, insist on account-level reconciliation you can see yourself.
E-money or payment institution licence
An EMI licence lets you issue e-money, run accounts and cards, and process payments under your own name, and an EU licence can be passported across the EEA. You cannot take deposits or lend them out, and you must safeguard customer funds. In the UK, the FCA tightened those rules from 7 May 2026 with its new safeguarding regime, which requires daily reconciliations, a monthly safeguarding return and, for most firms, an annual safeguarding audit.
Full banking licence
A banking licence lets you take insured deposits and lend against them, which lowers your funding cost. It also brings the heaviest capital, governance and reporting requirements. In the UK, new banks can go through a mobilisation phase during which total deposits are capped at £50,000 and which should last no longer than 12 months. Even well-funded players can take longer: Revolut received its UK licence with restrictions in July 2024 and launched as a full UK bank only in March 2026.
Many teams start on a partner bank or an EMI licence and apply for a banking licence once the product has traction.
Step 3. Build or Buy the Core Platform
The core banking system keeps the ledger, manages accounts and products, calculates fees and interest, and produces regulatory reports. Everything else plugs into it. Your main options:
- Licensed core platforms from established vendors: proven, but licence fees and integration work can be heavy for a startup.
- White-label neobank platforms: ready-made accounts, cards, KYC and admin modules you brand and extend. Our review of white-label solutions for neobanks compares the main options.
- Custom development: full control and IP ownership, at the cost of time and budget.
A hybrid is often the practical answer: a modular base for accounts, ledger and compliance, with custom work only where you differentiate. That is the approach behind 4IRE’s neobank development platform, NeobankX, which combines white-label modules, low-code configuration, full IP ownership and a source-code licence.
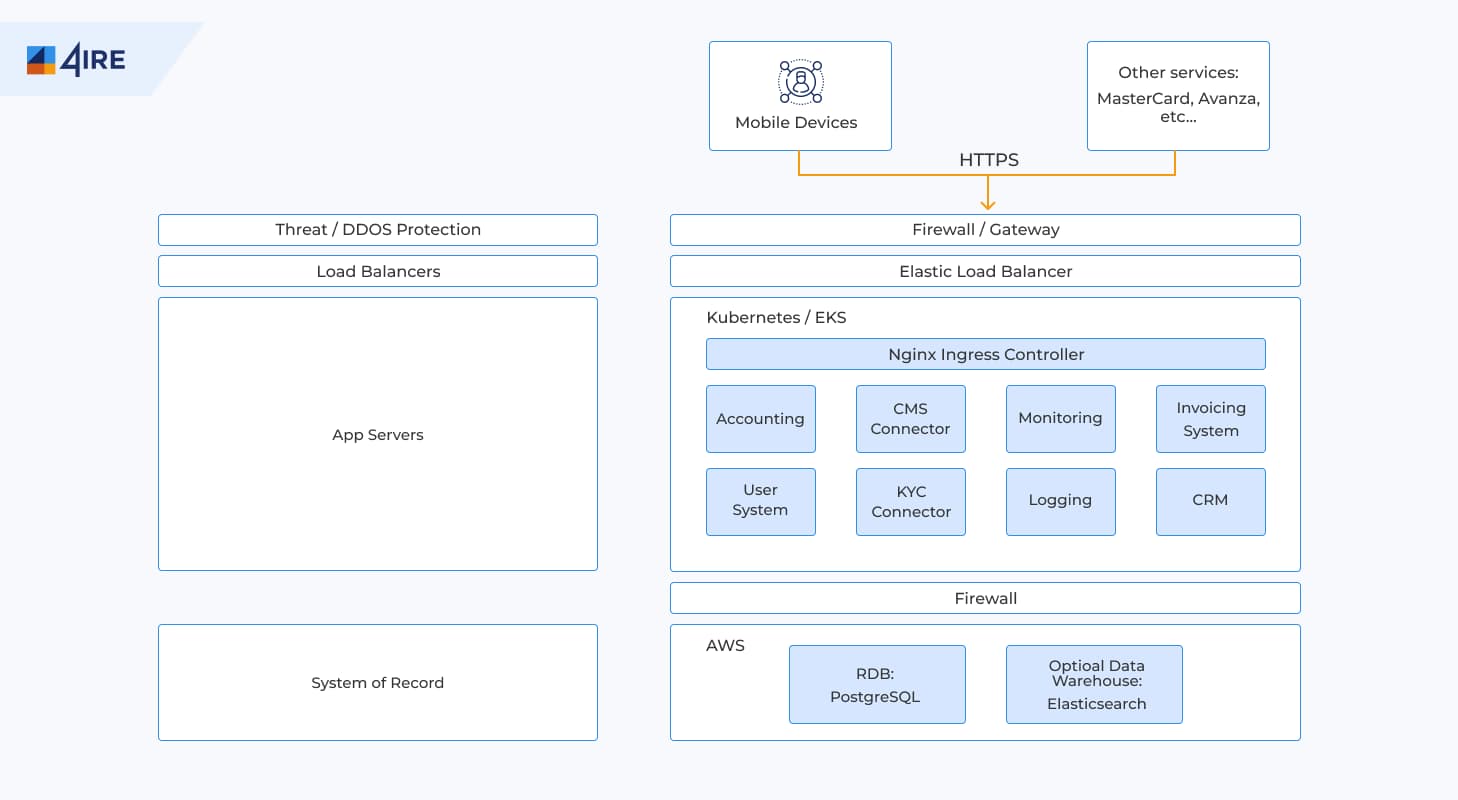
Around the core, a typical stack includes:
- Card issuing and processing, with PCI DSS scope kept as small as possible.
- Payment rails: SEPA, Faster Payments, SWIFT, card networks, and increasingly stablecoin settlement.
- Open banking APIs for account aggregation and account-to-account payments.
- Mobile and web apps, plus an admin back office for operations and support.
- Data, fraud detection and reporting.
Step 4. Put Compliance into the Architecture
Regulators judge your controls, not your intentions. KYC, AML and fraud controls have to be built into onboarding and transaction flows, not added before launch. At minimum, plan for:
- Identity verification and KYB for business clients, with document and liveness checks.
- Sanctions and PEP screening at onboarding and on an ongoing basis.
- Real-time transaction monitoring with case management for suspicious activity reports.
- Safeguarding or reconciliation reports produced from the ledger, not from spreadsheets.
- Data protection under GDPR or the local equivalent, plus audit logs for every admin action.
Keep an eye on changing rules. In the EU, the new Anti-Money Laundering Authority has been operating since July 2025, and the single AML Regulation applies directly in all member states from 10 July 2027. A neobank launching now should design its KYC and monitoring to that standard rather than retrofit it later.
Step 5. Design and Test the Product
Customers judge a neobank in the first few minutes: how fast they can open an account, get a card and make a first payment. Design onboarding around that path, then add features in the order your niche needs them.
Common first-release features include multi-currency accounts, virtual and physical cards, instant transfers, push notifications and spending analytics. A focused mobile banking app with fewer, reliable features usually beats a crowded one.
Before launch, run functional, security and load testing, a penetration test, and a closed beta with real users and real money. Regulators and partner banks will ask for evidence of all of it.
Step 6. Launch, Grow and Stay Compliant
Launch in one market with one strong product, measure activation and retention, then expand. Referral programmes and visible benefits such as fee-free FX or cashback are the usual growth levers; the Plata case shows how far referrals alone can take a neobank. Paid acquisition is expensive in financial services, so unit economics matter from day one.
After launch, operations become the main job: customer support, fraud handling, regulatory reporting, audits and regular releases. Budget for this run cost, not only for the build.
How Much Does It Cost and How Long Does It Take?
There is no honest single figure. Cost and timeline depend on the licensing route, the number of markets, the payment rails and how much you build from scratch. Regulatory approval often takes longer than development. A white-label or modular platform shortens the build considerably compared with a fully custom core. The fastest way to a reliable estimate is a scoped discovery phase with your chosen jurisdiction and feature list.
How 4IRE Can Help
The 4IRE team builds neobanks, digital wallets and payment platforms for fintech startups and banks. We combine our NeobankX platform with custom financial software development, integrate KYC, AML and banking partners, and hand over full control of the IP. If you are planning to start a neobank, talk to us about your niche, jurisdiction and timeline.
Launch Your Neobank with 4IRE
Planning a neobank or digital wallet? Our team will help you choose the licensing model, platform and integrations. Schedule a free consultation with our experts today.
FAQ on Starting a Neobank
No. Many neobanks launch on a partner bank or banking-as-a-service provider, or with an electronic money institution licence. A full banking licence is needed only if you want to take insured deposits and lend them out, and it is the slowest and most capital-intensive route.
The main revenue streams are card interchange, FX spreads, subscription plans, lending interest, and fees from partner products such as insurance or investments. Which of them are available to you depends on your licence.
It depends on the licensing route, number of markets, payment rails and how much you build from scratch. A white-label or modular platform usually costs less and ships faster than a fully custom core. A discovery phase gives a reliable estimate for your specific scope.
Product development is often not the longest part. Partner onboarding and licensing can take months, and a full banking licence can take much longer; in the UK, the mobilisation phase alone can last up to 12 months.