

 Bank
Islamic banks hold roughly half of Kuwait's banking sector assets, according to Fitch Ratings via CIBAFI data, and the Central Bank of Kuwait (CBK) continues to push digital transformation across the sector. Yet there's a widening gap between mature, Shariah-compliant banking models and the crypto-enabled neobank infrastructure that's becoming standard elsewhere in the Gulf. That gap is the real story for anyone evaluating Kuwait: banks, investors, and platform builders.
This comparison draws on 4IRE's benchmarking of leading Islamic digital banks in Kuwait and the wider region (UAE, Bahrain, Qatar), cross-referenced against CBK data and Fitch's Islamic banking coverage. It focuses on three models worth understanding before you commit capital or a build roadmap to this market: Boubyan Bank's hybrid modernization, Nomo Bank's cross-border digital play, and National Bank of Kuwait's conventional scale, plus how Kuwait's regulatory stance on crypto changes what's actually buildable here.
Kuwait's Islamic Banking Market in 2026
Fitch's late-2025 outlook expected a stable operating environment for Kuwaiti banks through 2026, with steady non-oil-driven growth and continued bank credit expansion; the IMF's more recent Article IV review, published in early 2026, put Kuwait's 2026 real GDP growth at 3.8%. Within that, Islamic finance keeps gaining share, helped by government support for the sector and growing retail interest in Shariah-compliant and ethical-investment products. Kuwait Finance House, the country's largest Islamic bank, had its Long-Term Issuer Default Rating affirmed by Fitch at 'A' with a Stable Outlook in November 2025, in line with the ratings Fitch assigns to major banks elsewhere in the Gulf.
Growth isn't friction-free. New entrants face more than 30 overlapping CBK rules and licensing requirements, which raises costs and discourages smaller players, and every digital-first entrant competes against conventional incumbents that still hold roughly 70% of total banking assets. Market-size estimates from Ken Research put upcoming Islamic finance investment in the KWD 27 billion range; treat that figure as a directional estimate from a paid research provider rather than an official CBK statistic.
Three Models: Boubyan, Nomo, and NBK
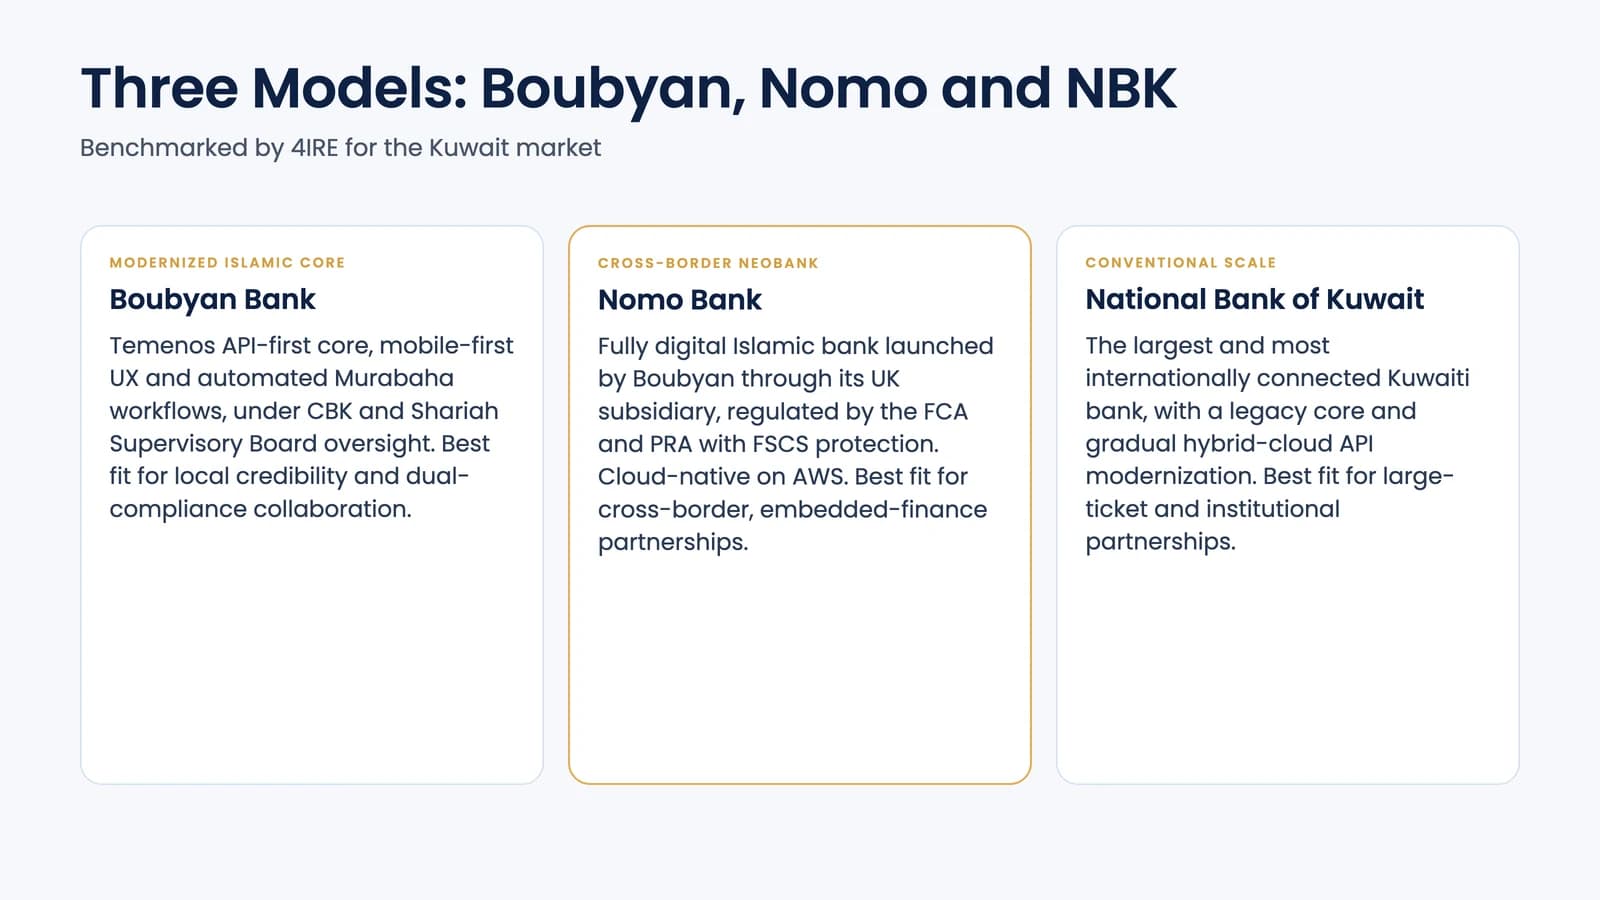
Kuwait Finance House, founded in 1977, is the country's oldest and largest Islamic bank, but Boubyan Bank (founded 2004, backed by the National Bank of Kuwait) is the clearer digital-modernization story, and Nomo Bank shows what a Kuwait-linked institution looks like once it moves outside CBK's jurisdiction entirely.
- Boubyan Bank — modernized Islamic core. Runs on a Temenos API-first core banking platform with a mobile-first UX and automated Murabaha workflows, all under direct CBK and Shariah Supervisory Board oversight. Best fit for partners who want local credibility and a structured, dual-compliance (CBK plus Shariah) collaboration.
- Nomo Bank — cross-border cloud-native neobank. A fully digital Islamic bank launched by Boubyan through its UK subsidiary, Bank of London and The Middle East, regulated by the FCA and PRA with FSCS deposit protection. Cloud-native on AWS with an Open Banking API layer, but not available to UK residents and with a smaller balance sheet than a domestic Kuwaiti bank. Best fit for cross-border, embedded-finance partnerships rather than domestic Kuwaiti distribution.
- National Bank of Kuwait — conventional scale. The largest and most internationally connected Kuwaiti bank, running a legacy core with gradual, hybrid-cloud API modernization. Strong on institutional and corporate relationships and Basel-aligned governance, weaker on time-to-market for new FinTech integrations. Best fit for large-ticket financing and institutional-scale partnerships where stability matters more than launch speed.
For context on the international side of this comparison, Revolut and N26 both offer crypto trading in-app (Revolut region-dependent, N26 via N26 Crypto) and operate under EMI or full banking licenses in Europe, which the Kuwaiti banks in this comparison cannot replicate domestically because of CBK's stance on virtual assets, covered next.
CBK Regulation and the Crypto Ban
Every Islamic digital bank operating in Kuwait sits under a conservative, Shariah-supervised CBK regime: Basel III-aligned capital rules, a licensed Islamic banking charter, a mandatory independent Shariah Supervisory Board, product-level Shariah approval before launch, and strict outsourcing and cybersecurity controls, including AAOIFI-aligned standards for FinTech integrations. Murabaha, the cost-plus financing contract behind most Islamic retail products, has its own compliance layer: genuine asset transfer and ownership before resale, disclosed profit margins, no riba (interest) in the pricing, and a full audit trail.
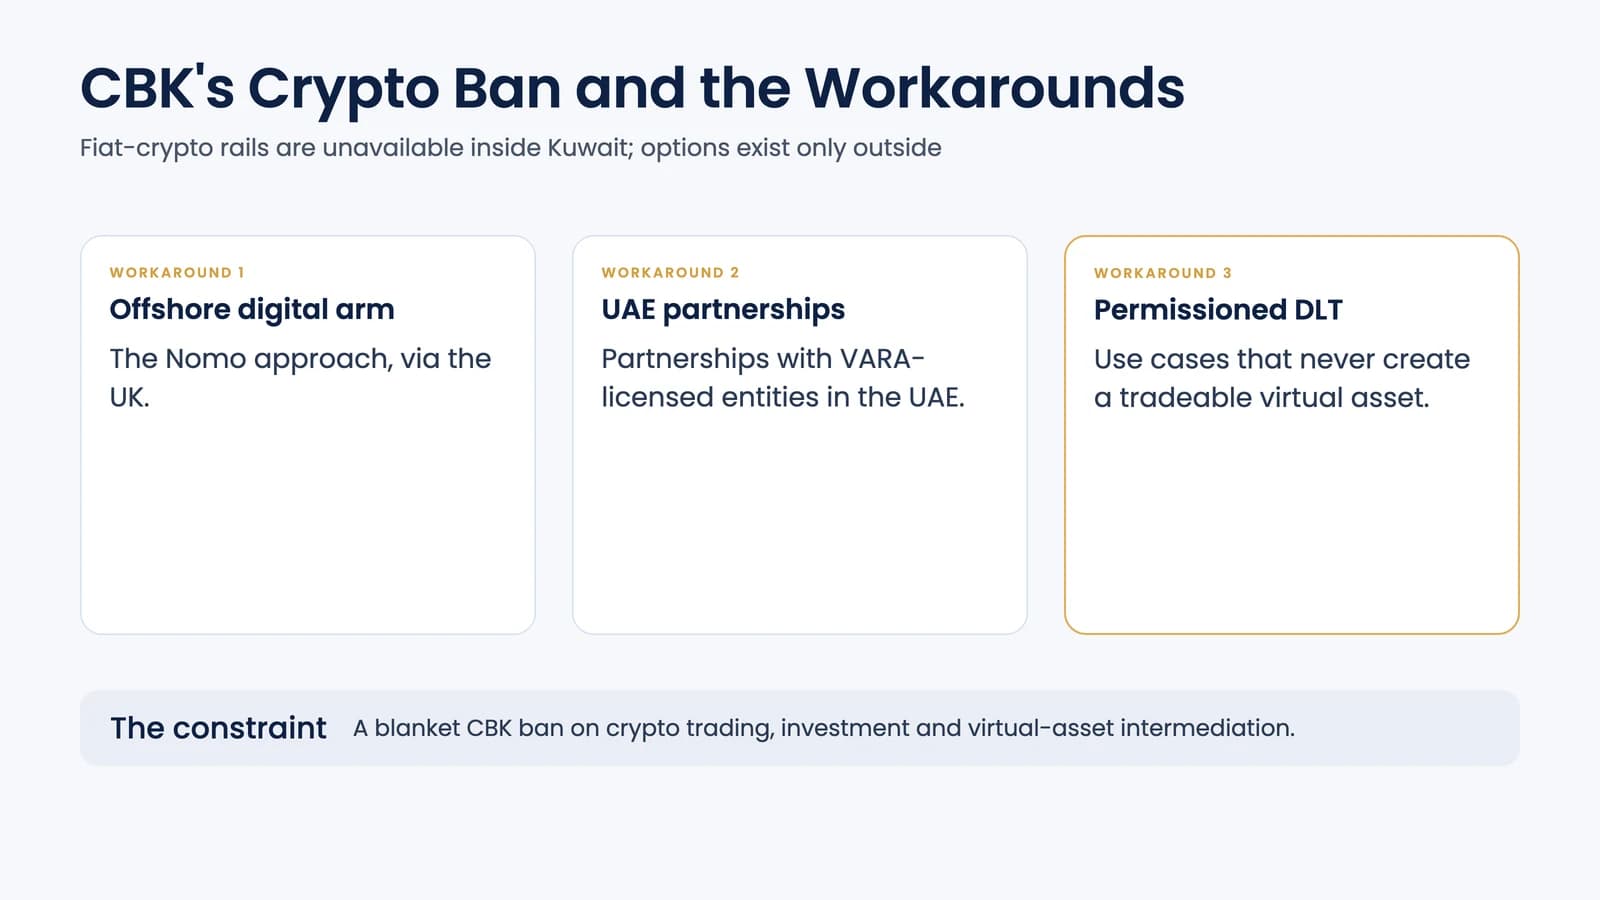
The headline constraint is CBK's blanket ban on crypto trading, investment, and virtual-asset intermediation, which makes fiat-crypto rails structurally unavailable inside Kuwait regardless of a bank's technical readiness. Workarounds exist only outside the jurisdiction: an offshore digital-arm model (the Nomo approach via the UK), partnerships with VARA-licensed entities in the UAE, or permissioned DLT use cases that never create a tradeable virtual asset. Liv Bank, a UAE-regulated digital bank with a visible presence in Kuwait, shows the offshore-crypto pattern in practice, running in-app crypto trading through VARA-regulated partners like Aquanow and Zodia Custody. None of this closes the fiat-crypto gap for a Kuwait-domiciled customer; it only shows where a Kuwait-linked institution can go to offer it.
Where the Real Opportunity Sits
The constraints are real, but so is the market. Kuwait's retail banking sector isn't saturated the way some GCC neighbors are, sustainable and green-finance products are gaining traction as Shariah-compliant options, and Sukuk (Islamic bonds) continue to draw investor interest even as the crypto door stays closed. The practical near-term moves for a bank, investor, or platform builder targeting Kuwait are:
- Open banking and eKYC. Standardized APIs and remote identity verification are the clearest near-term modernization path that doesn't touch the crypto ban.
- Embedded Islamic finance. Murabaha-based financing embedded into e-commerce, SME, and B2B flows, following the same halal-structuring discipline covered in our guide to Shariah-compliant DeFi for teams that also want to understand the blockchain side of halal product design.
- SME-focused Murabaha automation. Digitizing and automating SME financing lets smaller institutions compete with the conventional incumbents that dominate on scale alone.
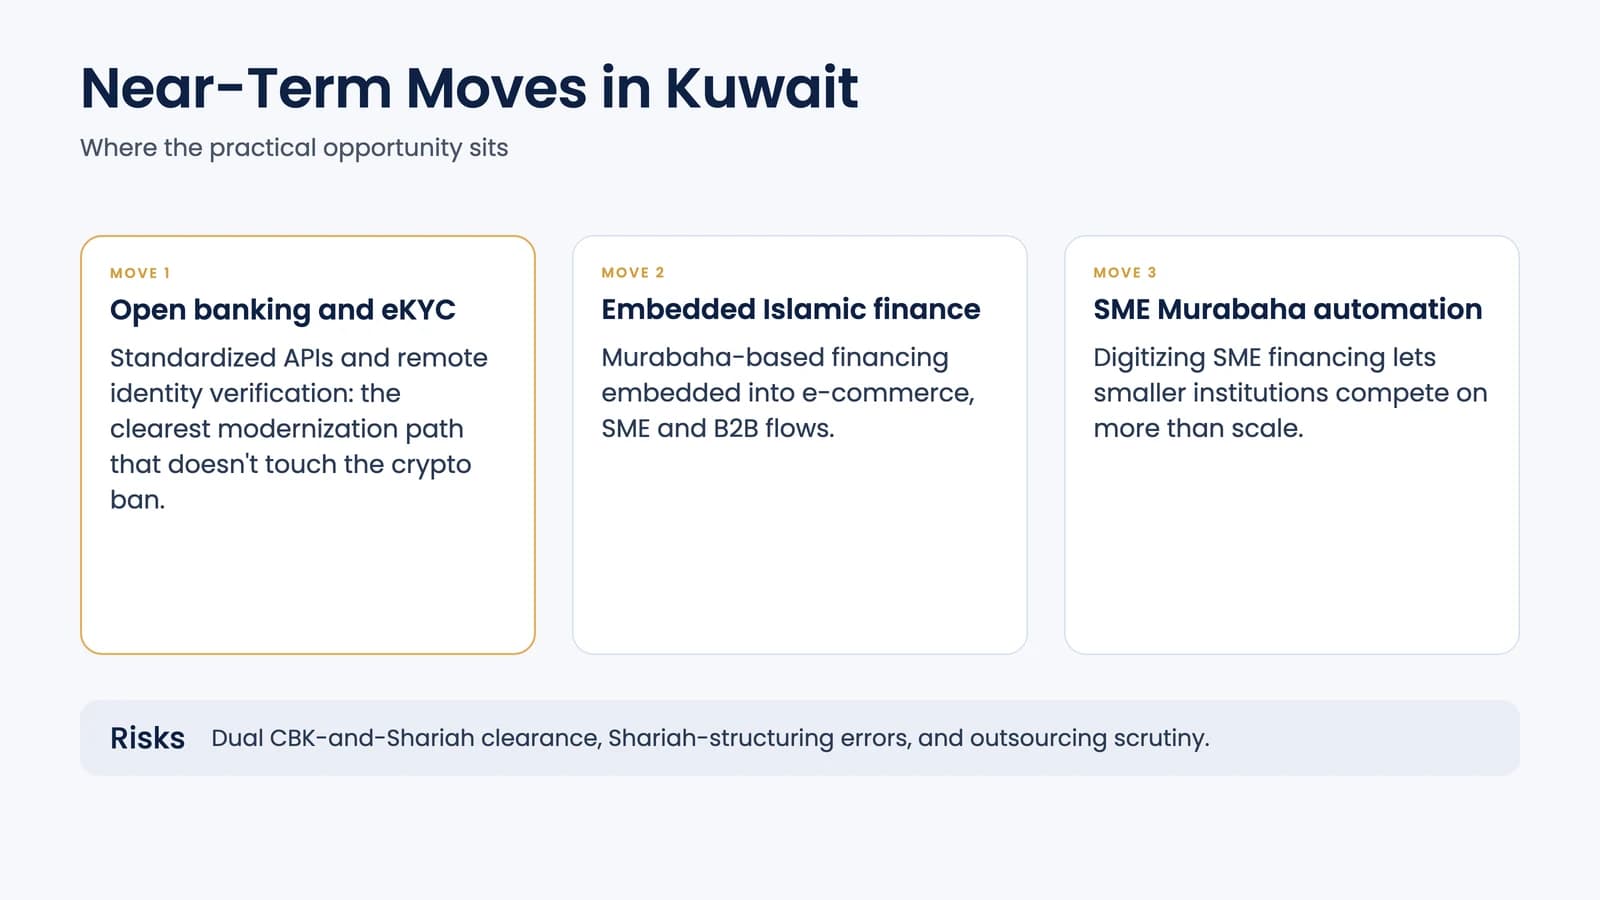
The main risks to plan around are regulatory (dual CBK-and-Shariah clearance slows every new product), Shariah-structuring risk (execution errors in disclosure or asset-ownership sequencing can invalidate a contract), and outsourcing risk (cloud and vendor arrangements draw extra CBK scrutiny). None of these are reasons to avoid the market; they're reasons to design compliance into the architecture from day one rather than retrofitting it, the same principle that applies to any regulated digital bank.
How 4IRE Can Help
4IRE builds modular, white-label Shariah-compliant digital banking infrastructure informed by exactly this kind of benchmarking work for banking industry clients across the Gulf. If you're evaluating a partnership model, our step-by-step guide on how to start a neobank covers the licensing and core-platform decisions that apply just as much to a hybrid Islamic build, and our review of white-label solutions for neobanks and our neobank development platform both apply directly to a Kuwait-style hybrid build: modular core, low-code configuration, and a compliance layer designed for dual CBK-and-Shariah oversight from the start. If your roadmap includes CBDC-adjacent product design, our explainer on CBDCs and how banks can benefit is a useful companion piece, since it's the one digital-asset direction that doesn't run into CBK's ban on private virtual assets. Talk to us about your target market and licensing route before you commit to an architecture.
FAQ: Common Questions on Kuwait Islamic Digital Banking in 2026
Islamic neobanks operate under Shariah governance and structure their products, such as Murabaha-based financing, to avoid riba (interest). That means genuine asset ownership sequencing, disclosed profit margins instead of interest rates, and sign-off from an independent Shariah Supervisory Board on every product before launch.
No. Kuwaiti regulation bans crypto trading, investment, and virtual-asset intermediation for licensed banks, including Islamic banks. Kuwait-linked institutions that want to offer crypto services do it through an offshore subsidiary or partnership in a jurisdiction with its own crypto licensing regime, such as the UAE's VARA framework, not domestically.
CBK sets and enforces capital, liquidity, governance, outsourcing, and AML/CFT rules for every licensed bank, and adds Shariah-specific governance requirements for Islamic institutions, including continuous Shariah Supervisory Board oversight and product-level approval before launch.
Dual compliance clearance (CBK and Shariah) slows product launches, outsourcing and cloud arrangements face extra regulatory scrutiny, and the crypto ban rules out an entire category of product that's available to competitors in nearby jurisdictions. None of these are unique to Kuwait, but together they lengthen time-to-market compared with more permissive GCC markets.
Partnerships in Kuwait are bank-led: new entrants typically integrate with an incumbent Islamic bank via API rather than obtaining a standalone license of their own. Any crypto-related infrastructure has to be built and licensed outside Kuwait, then connected back in through a compliant partnership structure.