

 Fintech news
Ten years ago, a customer who wanted to see all their accounts in one place, verify income for a loan or pay a merchant straight from a bank account had few good options. Today most of that runs over open banking APIs. For a digital bank or fintech, the question is no longer whether to use them, but which provider to build on and how much of the plumbing to own.
This guide explains what open banking and banking APIs are, where regulation stands in the EU, the UK and the US as of September 2026, and how seven established open banking API providers compare. It is written for product and tech leads choosing a data or payments layer for a digital bank or fintech app.
What Is Open Banking?
Open banking is a model in which banks let licensed third parties access customer account data or initiate payments, with the customer's explicit consent, through secure APIs. Instead of asking users to type in their bank password or upload PDF statements, an app redirects them to their bank, the bank authenticates them, and the app receives a token that allows it to read data or start a payment within agreed limits.
Two regulated roles sit at the core of the model in Europe and the UK:
- Account information service providers (AISPs) read balances and transactions to power budgeting apps, affordability checks, accounting tools and onboarding flows.
- Payment initiation service providers (PISPs) start account-to-account payments from the customer's bank, often called pay by bank.
Many providers also offer variable recurring payments (VRPs), payouts, account ownership checks and data enrichment on top of these two basics.
What Is a Banking API?
An API is a defined interface that lets one system request data or actions from another. In banking, APIs let a bank expose accounts, transactions and payment functions to its own apps, to partners, or to regulated third parties.
Open banking aggregators add a layer on top: one integration that connects your product to thousands of banks, normalizes their different data formats, and handles consent, token refresh and connection errors. That is what most fintechs buy, because integrating bank by bank is slow and each bank's API behaves slightly differently.
Why Open Banking Matters for Digital Banks
For a digital bank or fintech, open banking APIs typically deliver value in four places:
- Onboarding: confirm that the customer owns the account they are funding from, and pre-fill or verify identity data.
- Lending: read income and spending patterns for affordability checks, which is why open banking data is now a standard input for a modern credit scoring system.
- Payments: accept pay by bank at checkout, fund wallets and send instant payouts, often at lower cost than cards.
- Engagement: show external accounts inside your app, so the user manages their money in one place.
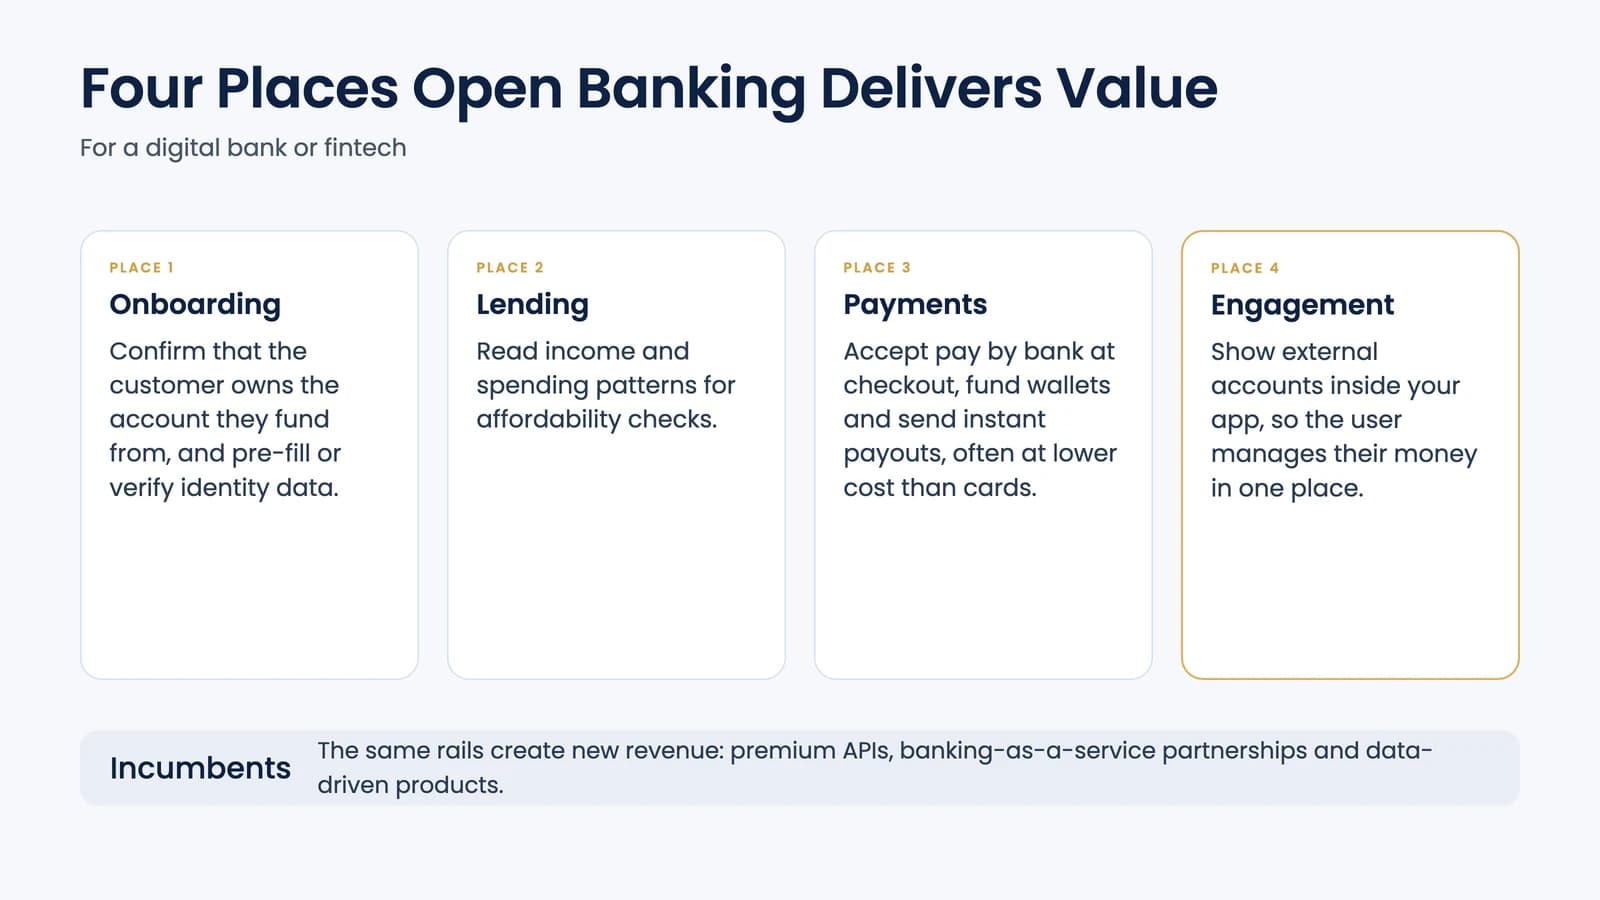
For incumbents, the same rails create new revenue: premium APIs, banking-as-a-service partnerships and data-driven products.
Where Open Banking Regulation Stands in 2026
EU. PSD2 has required banks to open account access to licensed third parties since 2018. Its successors, the third Payment Services Directive (PSD3) and the directly applicable Payment Services Regulation (PSR), were politically agreed in November 2025, and final compromise texts were published in April 2026; formal adoption and publication in the Official Journal were still pending in September 2026. They tighten API performance requirements, add a permissions dashboard for users and bring e-money firms into the payments framework; most rules are not expected to apply before 2028.
UK. The CMA-mandated open banking regime is moving to a long-term framework led by the FCA, which plans to consult on it by the end of 2026. In June 2026 the industry-led UK Payments Initiative scheme launched commercial variable recurring payments, which let customers authorise flexible recurring payments for goods and services directly from their bank account.
US. The CFPB finalized its Section 1033 personal financial data rights rule in October 2024, but a federal court has blocked its enforcement while the agency reconsiders it. In August 2026 the CFPB sent a revised proposal to the White House for review; one of the issues it reopened is whether banks may charge fees for data access. Until that settles, US data sharing runs mainly on bilateral agreements between banks and aggregators.
For founders, the practical upshot is that EU and UK products can rely on regulated access, while US products should plan for changing costs and contract terms. Which license you need to use these APIs yourself is covered in our guide to types of fintech licenses.
Top 7 Open Banking APIs for Digital Banks
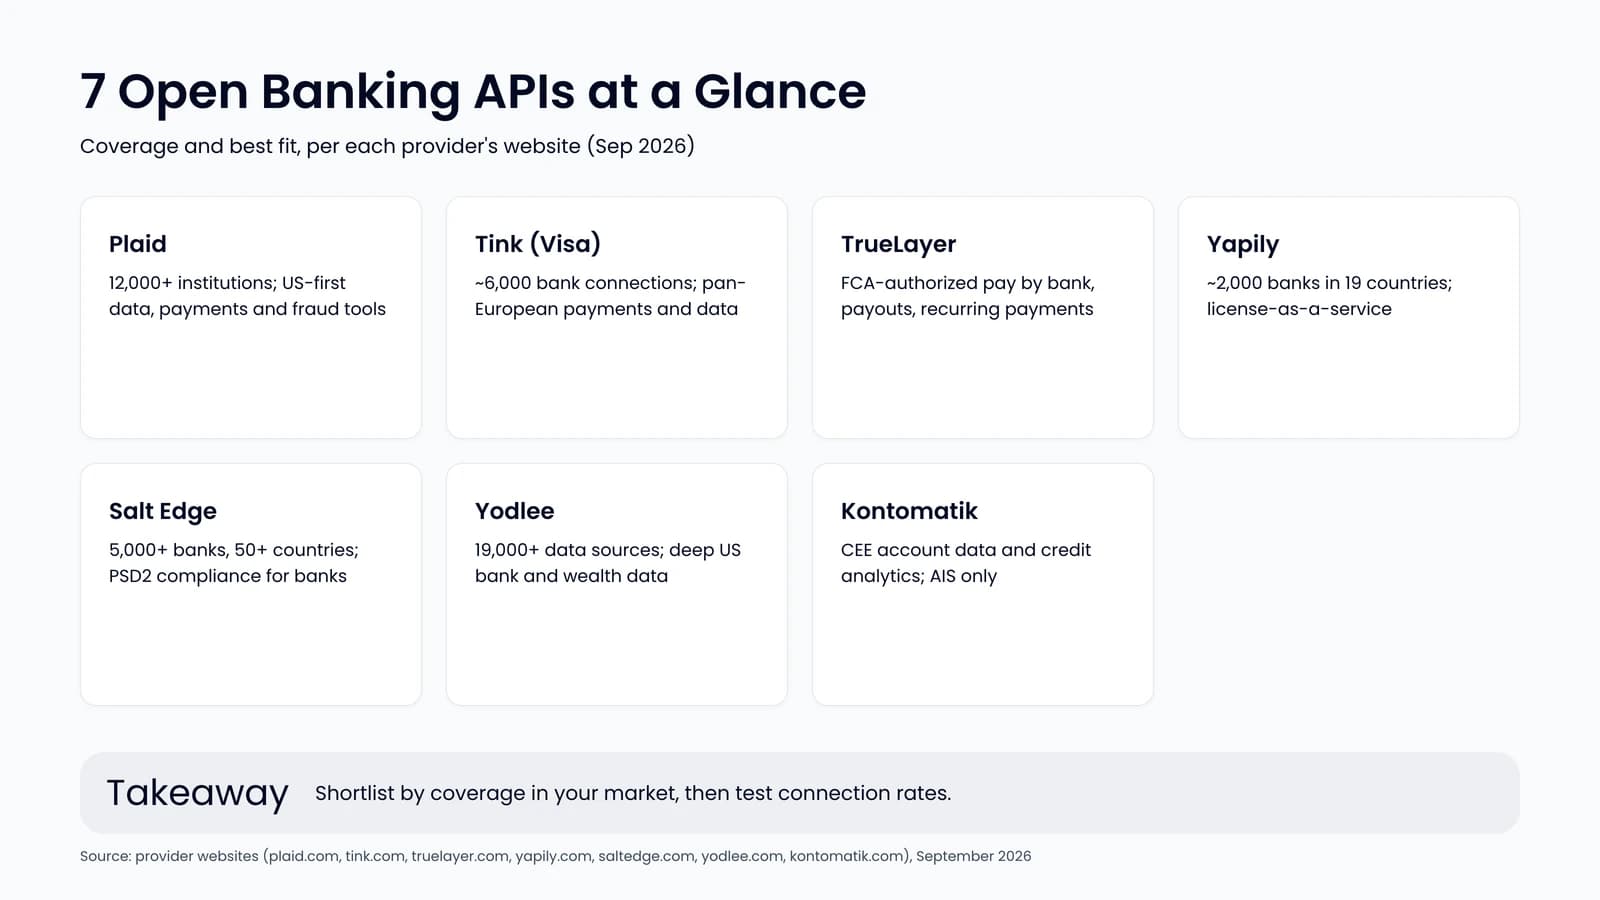
The providers below are established, still operating and cover the main use cases. Figures come from each provider's own website as of September 2026.
Plaid
Plaid is the default data network for many US fintechs and also operates in the UK and EU. It says it supports over 12,000 financial institutions and that more than 9,000 digital financial services are built on it. Its product set spans account verification (Auth), balances, transactions, identity checks, income and liabilities data, and payment and fraud tools such as Transfer and Signal. Best for: US-first consumer apps and lenders.
Tink
Tink, now part of Visa, is one of the largest European platforms with about 6,000 bank connections. It covers pay by bank, sweeping VRPs, payouts, account checks, transaction data and enrichment, plus income, expense and risk insights. Clients can operate under Tink's own PSD2 license rather than obtaining one. Best for: pan-European payments and lending products.
TrueLayer
TrueLayer focuses on pay by bank. It is authorized by the UK FCA and operates across the UK and major EU markets. Alongside payments it offers payouts, recurring payments and a data API. The company says its network reaches over 30 million consumers. Best for: checkout, wallet top-ups and instant payouts in the UK and Europe.
Yapily
Yapily provides open banking infrastructure with about 2,000 banks and institutions integrated across 19 countries, with the deepest coverage in the UK and Germany. It offers payments, data, enrichment and VRPs. Through Yapily Connect, regulated in the UK and Lithuania, customers can access open banking without their own license. Best for: platforms that want a lean API layer and license-as-a-service.
Salt Edge
Salt Edge offers account information and payment initiation across more than 5,000 banks in over 50 countries. It also sells a PSD2 compliance product for banks that need to expose their own APIs, along with strong customer authentication and AML monitoring tools. Best for: broad geographic coverage, and banks that must meet their own open banking obligations.
Yodlee
Yodlee has aggregated financial data for about 25 years and was acquired by private equity firm STG in September 2025. It reports more than 601 million connected consumer accounts and over 19,000 data sources, and serves large US banks and wealth managers. Its FastLink flow handles account linking and verification. Best for: banks and wealth platforms that need deep US data coverage.
Kontomatik
Kontomatik specializes in Central and Eastern Europe (Poland, the Baltics, Czechia and Romania) and also covers Spain and Portugal. It is an authorized AISP in Lithuania and Poland and combines account data with income verification, transaction labeling and credit-risk analytics. It does not provide payment initiation. Best for: lenders and neobanks in the CEE region.
How to Choose an Open Banking API
A short list of seven quickly becomes two or three once you apply your own constraints:
- Coverage where your users bank. Test connection success rates for your top 20 banks, not the headline bank count.
- Data or payments, or both. Some providers are strongest in data, others in pay by bank; mixing two vendors is common.
- Licensing model. Decide whether you operate under the provider's license or your own AISP/PISP authorization.
- Data quality. Check categorization accuracy, history depth and how often balances refresh.
- Pricing. Compare per-connection, per-call and per-payment fees against your unit economics.
- Security and compliance. Ask for SOC 2 or ISO 27001 reports and review how consent and data retention work.
If you are building the app layer as well, our step-by-step guide on how to develop a mobile banking app shows where these integrations sit in the overall architecture, and our article on how to build a P2P payment app covers pay by bank in a peer-to-peer context.
Final Thoughts
Open banking has moved from a compliance project to core infrastructure. Regulation in the EU and UK is maturing, the US is still settling its rules, and the provider market has consolidated around a handful of large networks plus regional specialists. The right choice depends on where your customers bank and whether you need data, payments or both.
At 4IRE, we integrate open banking providers into neobank and fintech products as part of our financial software development work, from account linking and affordability checks to pay by bank. If you are planning a new digital bank, our guide on how to launch a neobank is a good place to start.
FAQ
Open banking covers payment accounts such as current accounts and cards. Open finance extends the same consent-based data sharing to savings, investments, pensions, insurance and loans. The EU and UK are both working on open finance frameworks, but payment account access remains the most mature part.
Not always. Many providers let you operate under their own AISP or PISP authorization as an agent or client. You need your own license if you want to hold that regulated role directly, which gives more control but takes longer and costs more.
Yes, when implemented properly. The customer authenticates with their own bank, the third party never sees the bank password, and access is limited by consent, scope and time. Providers must also meet security and data protection requirements under PSD2 and GDPR in Europe.
It depends on your market and use case. US consumer apps often start with Plaid, European payments products with Tink or TrueLayer, and CEE lenders with Kontomatik. Test connection rates for your target banks before committing.