

 Stablecoin news
Stablecoins are cryptocurrencies designed to hold a steady value, usually one US dollar, by linking each token to a reserve of assets or to an on-chain stabilisation mechanism. They move like crypto (on public blockchains, around the clock, in seconds) but behave like money, which is why they now sit underneath exchange trading, DeFi, cross-border payments and a growing share of corporate treasury flows.
This guide explains what stablecoins are, how the main types keep their peg, what the market looks like in 2026, how the new rules in the US, EU, Hong Kong and Singapore change the picture, and where the risks lie. It is written for founders and product teams deciding whether to integrate, hold or issue a stablecoin.
What is a stablecoin?
A stablecoin is a token whose price is pegged to a reference asset (most often the US dollar, sometimes the euro, another fiat currency or gold). The peg is only as credible as two things: what backs the token, and whether holders can actually swap it back for the reference asset at par.
That is the main difference from Bitcoin or Ether, whose prices float freely. A stablecoin is closer to a digital bearer claim on an issuer or a smart contract. Its usefulness comes from being programmable: it can be sent to any wallet, locked in a smart contract, or settled against another token in a single transaction.
How stablecoins keep their peg
For the dominant, fiat-backed model the mechanics are straightforward:
- Minting. An approved customer, usually an exchange, fintech or institution, sends dollars to the issuer, which mints the same number of tokens.
- Reserves. The issuer holds those dollars in cash, bank deposits, short-dated Treasury bills, repo or government money market funds, and publishes regular attestations of the reserve.
- Redemption. The customer returns tokens, the issuer burns them and pays out dollars at $1 per token.
- Arbitrage. If the market price drifts below $1, traders buy cheap tokens and redeem them at par; above $1, they mint and sell. That loop keeps the secondary price close to the peg.
Retail users rarely redeem directly; they rely on exchanges and market makers that do. Redemption access, reserve quality and transparency are therefore what separate a sound stablecoin from a fragile one. For a closer look at how two regulated issuers structure this, see our Circle vs Paxos comparison.
Types of stablecoins
Fiat-backed stablecoins
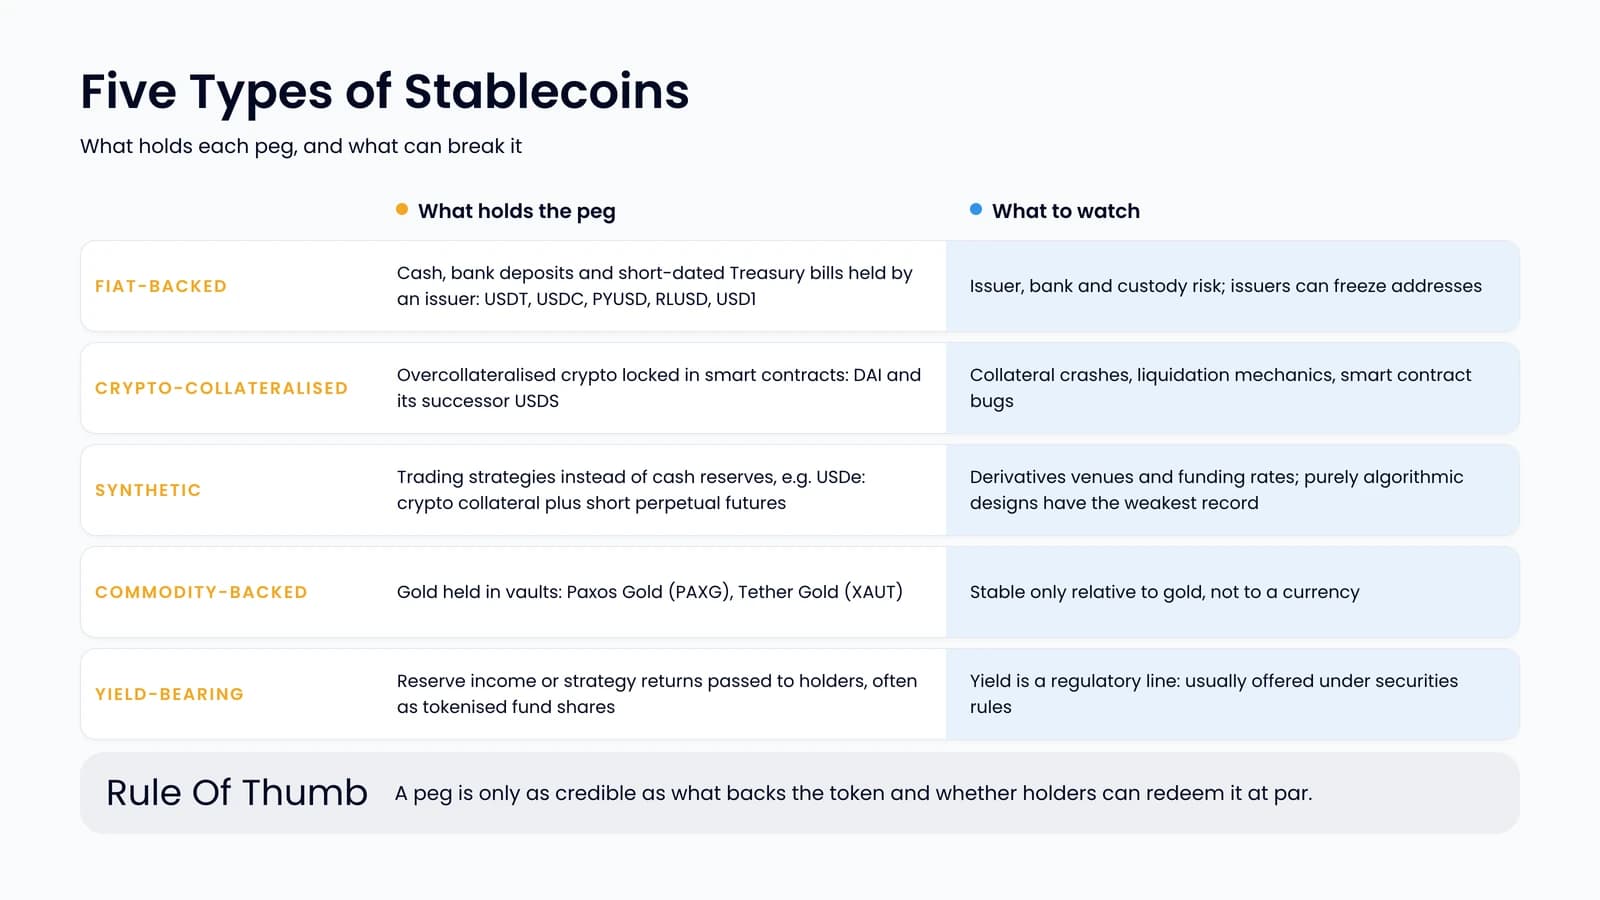
Tokens backed by cash and cash equivalents held by a centralised issuer. Tether’s USDT and Circle’s USDC dominate this category; PayPal USD (PYUSD), Ripple USD (RLUSD) and World Liberty Financial’s USD1 are newer entrants. They are simple and liquid, but holders depend on the issuer, its banks and its custodians, and issuers can freeze addresses.
Crypto-collateralised stablecoins
Tokens minted against crypto deposited in smart contracts, typically overcollateralised so that a price drop in the collateral does not break the peg. DAI and its successor USDS from Sky (formerly MakerDAO) are the best-known examples. They are more transparent on-chain, but exposed to collateral crashes, liquidation mechanics and smart contract bugs.
Synthetic and algorithmic stablecoins
Synthetic dollars hold value through trading strategies rather than cash reserves. Ethena’s USDe, for instance, pairs crypto collateral with short perpetual futures positions so that the combined position is delta-neutral. Purely algorithmic designs, which try to hold a peg by expanding and contracting supply with no hard collateral, have the weakest track record: the collapse of TerraUSD is the textbook case.
Commodity-backed stablecoins
Tokens backed by physical assets, most commonly gold held in vaults, such as Paxos Gold (PAXG) and Tether Gold (XAUT). They track the commodity rather than a currency, so they are stable only relative to gold.
Yield-bearing stablecoins
Tokens that pass reserve income or strategy returns to holders, often structured as tokenised money market or Treasury fund shares. Because regulators treat yield as a key line between money and investment products, these are usually offered under securities rules or outside payment stablecoin regimes. We cover the design options in our guide to yield-bearing stablecoins.
The stablecoin market in 2026
As of 28 September 2026, the total supply of US dollar stablecoins stood at roughly $313 billion, according to DefiLlama. The market is highly concentrated:
- USDT (Tether): about $184 billion, close to 59% of the total.
- USDC (Circle): about $75 billion, roughly 24%.
- USDS, USDe, DAI, USD1, PYUSD and RLUSD: each between about $2.5 billion and $10 billion.
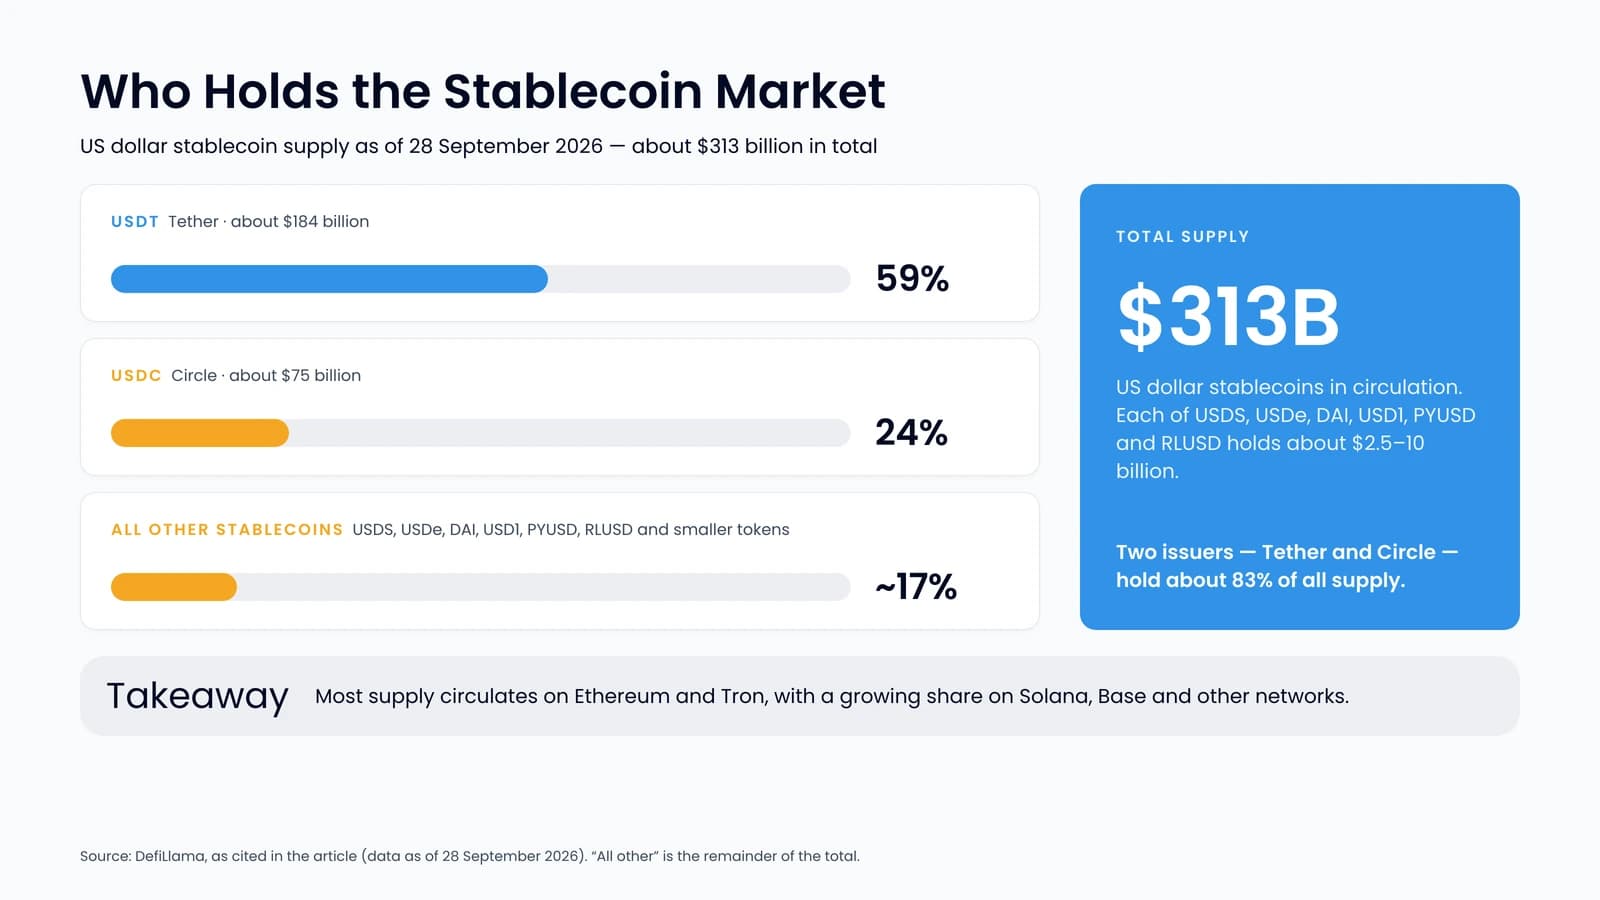
Most of that supply circulates on Ethereum and Tron, with a growing share on Solana, Base and other networks. Much of the demand still comes from crypto trading and DeFi, but payments companies, card networks and banks are now building on the same rails. Some banks prefer tokenised deposits over stablecoins. We explain the difference in stablecoins vs deposit tokens.
Stablecoin regulation
Until recently most stablecoins operated in a grey zone. That has changed in the largest markets:
- United States: GENIUS Act. Signed into law on 18 July 2025, it creates a federal licensing regime for payment stablecoin issuers. Issuers must hold at least 1:1 reserves in cash, insured deposits, Treasury bills maturing within 93 days, Treasury-backed repo or government money market funds, publish monthly reserve reports, and may not pay interest or yield to holders (Richmond Fed overview). The law takes effect on the earlier of 18 January 2027 or 120 days after final implementing rules; the OCC, FDIC, NCUA, Treasury and the Federal Reserve published proposals in 2026, and final rules were still pending at the time of writing.
- European Union: MiCA. Stablecoin rules have applied since 30 June 2024. Single-currency tokens are e-money tokens (EMTs), which only authorised credit or e-money institutions may issue; tokens referencing a basket of assets are asset-referenced tokens (ARTs). Tether has not sought MiCA authorisation for USDT, so major EU-regulated exchanges have restricted it for EEA users, while USDC and EURC are issued under an e-money licence.
- Hong Kong: Stablecoins Ordinance. In force since 1 August 2025. On 10 April 2026 the HKMA granted the first issuer licences to HSBC and Anchorpoint Financial, a joint venture involving Standard Chartered.
- Singapore: MAS framework. MAS finalised its single-currency stablecoin framework in August 2023 and in September 2026 opened a consultation on the Payment Services Act amendments that will give it legal force.
The practical effect: issuing a stablecoin to the public now means, or will soon mean, a licence, a reserve and custody structure, audits and ongoing reporting, not just a token contract. For enterprise architecture, see our piece on stablecoin infrastructure.
What stablecoins are used for
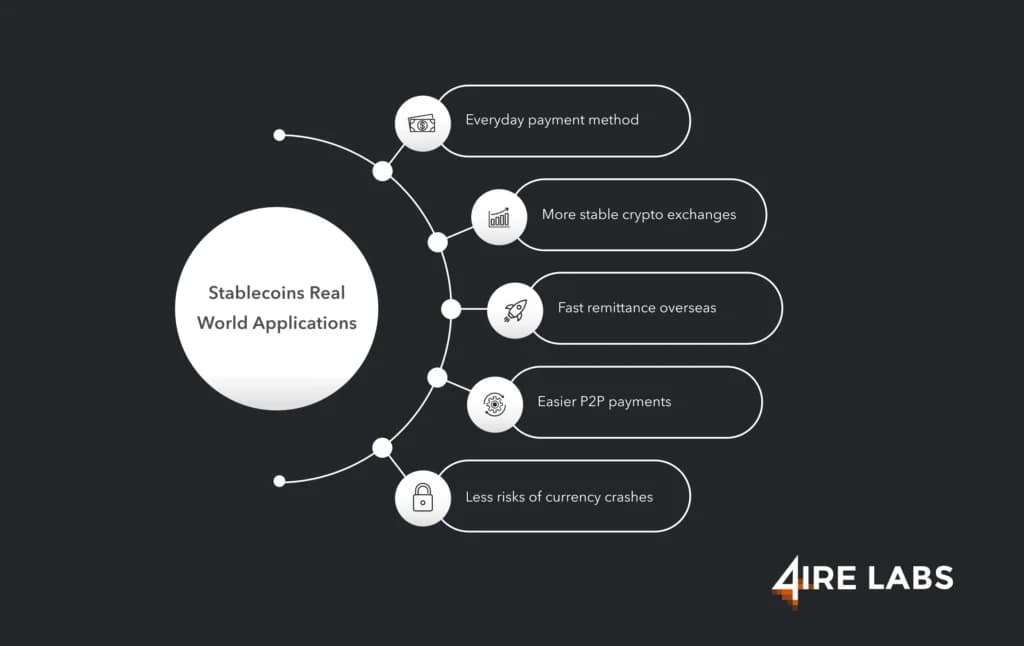
- Trading and settlement. Stablecoins are the base pair on most crypto exchanges and the unit in which positions are settled.
- Cross-border payments. Businesses and remittance providers use them to move dollars between countries in minutes, converting to local currency at the edges.
- DeFi. Lending markets, AMMs and derivatives protocols use stablecoins as collateral and liquidity, the core of most DeFi products.
- Treasury and savings. Companies hold stablecoins as working capital for on-chain operations; users in high-inflation economies hold them as a dollar substitute.
- Embedded finance. Wallets, neobanks and marketplaces add stablecoin balances, payouts and cards as a product feature.
Risks to understand
- Depegs. TerraUSD (UST), an algorithmic stablecoin, lost its peg in May 2022 and collapsed together with its sister token LUNA. In March 2023 USDC fell to about $0.87 after Circle disclosed that $3.3 billion of its reserves sat at the failed Silicon Valley Bank; it recovered once US authorities protected SVB depositors (Circle).
- Issuer and custody risk. A fiat-backed token is only as strong as its reserves, banks and custodians.
- Smart contract risk. Bugs in token, bridge or collateral contracts can drain funds; a smart contract audit is a baseline, not an option.
- Regulatory and freeze risk. Tokens can be delisted in a jurisdiction, and centralised issuers can freeze addresses on legal orders.
- Counterparty and liquidity risk in synthetic designs that depend on derivatives venues and funding rates.
Building with stablecoins
For most businesses the question is not whether to launch a new coin but how to integrate existing ones: choosing which tokens and chains to support, wiring on- and off-ramps, managing custody and compliance, and handling redemptions and reconciliation. Launching your own token makes sense mainly for regulated institutions or ecosystems with their own settlement volume; our walkthrough on how to create a stablecoin on Ethereum covers the technical side.
The 4IRE team designs and builds stablecoin wallets, payment flows, DeFi integrations and issuance platforms as part of our cryptocurrency development services.
FAQ
They are designed to be less volatile than other crypto, not risk-free. Safety depends on the quality and transparency of reserves, the issuer’s regulatory status and redemption terms, and the security of the smart contracts. Both algorithmic and fully reserved stablecoins have lost their peg in the past.
Fiat-backed issuers earn interest on the reserves they hold, mainly short-term Treasury bills and cash, and may charge minting or redemption fees. Under the US GENIUS Act, payment stablecoin issuers may not pass interest or yield to holders.
Both are US dollar stablecoins backed by reserves. USDT, issued by Tether, is the largest by supply. USDC, issued by Circle, is the second largest and is issued under an e-money licence in the EU, which makes it available on MiCA-regulated exchanges where USDT has been restricted.
Technically, yes: the token contract is the easy part. Issuing to the public in the EU or Hong Kong already requires a licence, and the US (GENIUS Act, effective by January 2027) and Singapore (pending legislation) are following, with segregated high-quality reserves, redemption at par, audits and reporting, so most businesses integrate existing stablecoins or partner with a licensed issuer.