

Payments are the part of fintech every other part depends on: lending, banking and investing products all eventually move money, and how efficiently that money moves shapes the product built on top of it. This guide looks at what has actually changed in payment infrastructure by 2026, separating genuine shifts in how money moves from branding around features that have existed for years.
Instant and Programmable Rails
Real-time payment rails have moved from a retail novelty to standard infrastructure for payroll, treasury and cross-border transfers. A decade ago, instant payments meant a person sending a friend money on a Saturday; by 2026, the same rails move payroll runs, supplier payments and treasury sweeps that used to wait for the next banking day.
Programmable payments extend that shift further: a transfer fires automatically once a contract condition is met, a shipment confirmation, an invoice due date, a usage threshold, without a person approving it manually. For a treasury team, that turns a payment run that used to need a multi-day approval chain into a rule that executes itself and gets reviewed after the fact, not before.
| Rail type | Typical settlement | Where it fits |
|---|---|---|
| Card networks | Authorized instantly, settled in 1-3 days | Consumer retail, subscriptions |
| Bank transfer / ACH-style rails | Same day to a few days | Payroll, supplier payments, recurring bills |
| Real-time payment schemes | Seconds | Person-to-person, urgent B2B, payroll in markets that support it |
| Stablecoin / tokenized settlement | Minutes, limited by block confirmation | Cross-border B2B, treasury between entities on the same network |
Open Banking Matures
Open banking gives a customer's own account data to a third-party app through a regulated API, not a screen-scraped login. It started as a UK and EU regulatory requirement and has become a feature banks in more markets ship voluntarily, because the use cases it unlocks, a lender checking real transaction history instead of a self-reported income figure, a budgeting app that reads balances across every account a user holds, a checkout that pays directly from a bank account instead of routing through a card network, are now customer expectations, not a compliance checkbox.
Our roundup of the best open banking APIs compares the providers building on top of this layer.
Stablecoins and Tokenized Settlement
Stablecoin supply passed $311 billion as of 30 September 2026, per DefiLlama, and a growing share of that volume is settlement between businesses, not crypto trading. The pitch is straightforward: a cross-border transfer that would otherwise wait on correspondent banking hours can settle in the time it takes a block to confirm. In the UAE specifically, this kind of payment token falls under the CBUAE's Payment Token Services Regulation, in effect since 31 August 2024, covered in our guide to getting a crypto license in the UAE.
AI in Fraud Prevention and Service
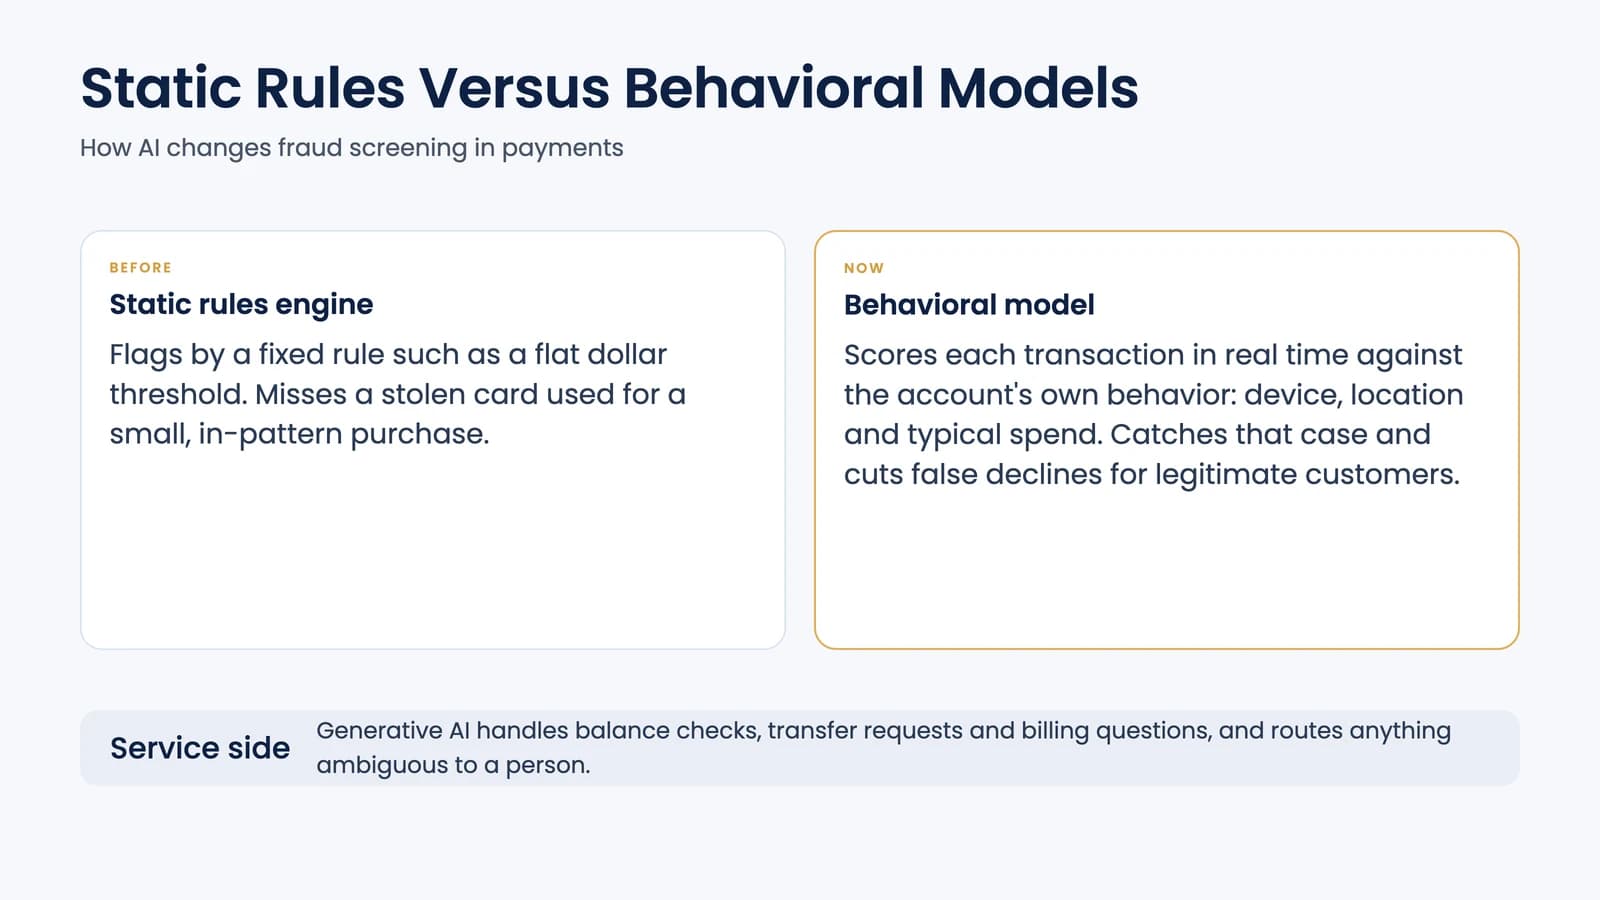
Machine learning models score transactions for fraud in real time by comparing a transaction against the account's own behavior, device, location, typical spend, not a fixed rule such as a flat dollar threshold. That shift catches cases a static rules engine misses, a stolen card used for a small, in-pattern purchase, while also cutting the false declines that frustrate legitimate customers at checkout.
On the service side, generative AI now handles a growing share of balance checks, transfer requests and billing questions through a chat interface, routing anything genuinely ambiguous to a person instead of trapping the customer in a menu tree. Our wider look at AI use cases in finance covers both patterns in more depth.
Alternative and Local Payment Methods
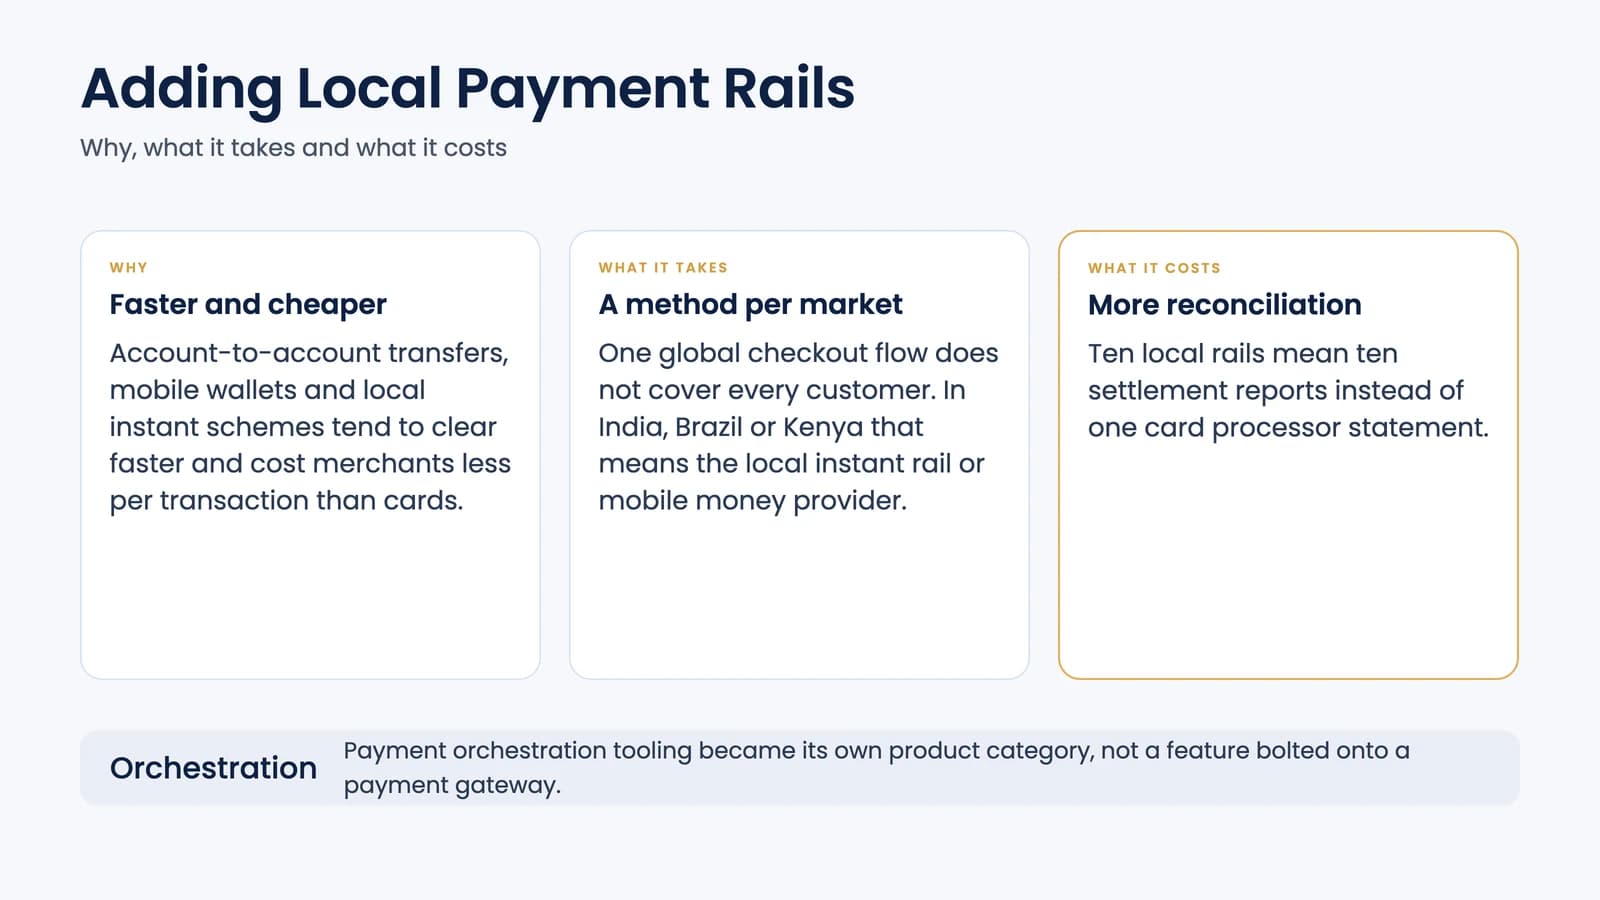
Account-to-account transfers, mobile wallets and local instant-payment schemes are taking a growing share of checkout volume away from cards in markets where they are well established, because they tend to clear faster and cost merchants less per transaction. A merchant selling into India, Brazil or Kenya without supporting the local instant-payment rail or mobile money provider is competing with checkout flows that convert better simply because they feel native to the buyer.
Supporting this usually means adding payment methods per market, not assuming one global checkout flow covers every customer. It also raises the reconciliation workload: a business accepting ten local rails is reconciling ten settlement reports instead of one card processor statement, which is the main reason payment orchestration tooling has become its own product category, not a feature bolted onto a payment gateway.
Digital Identity, Underneath All of This
Every rail above depends on verifying who is sending and receiving money, and that verification layer is itself changing. Reusable digital identity, verify once with a bank or government-backed credential, then reuse that verification across apps, is replacing the pattern of re-entering ID documents and waiting for manual review at every new provider. The effect is mostly invisible to the end user: fewer onboarding drop-offs, faster fraud checks, and fewer accounts rejected because a document scan failed for a reason nobody explained.
Financial Inclusion
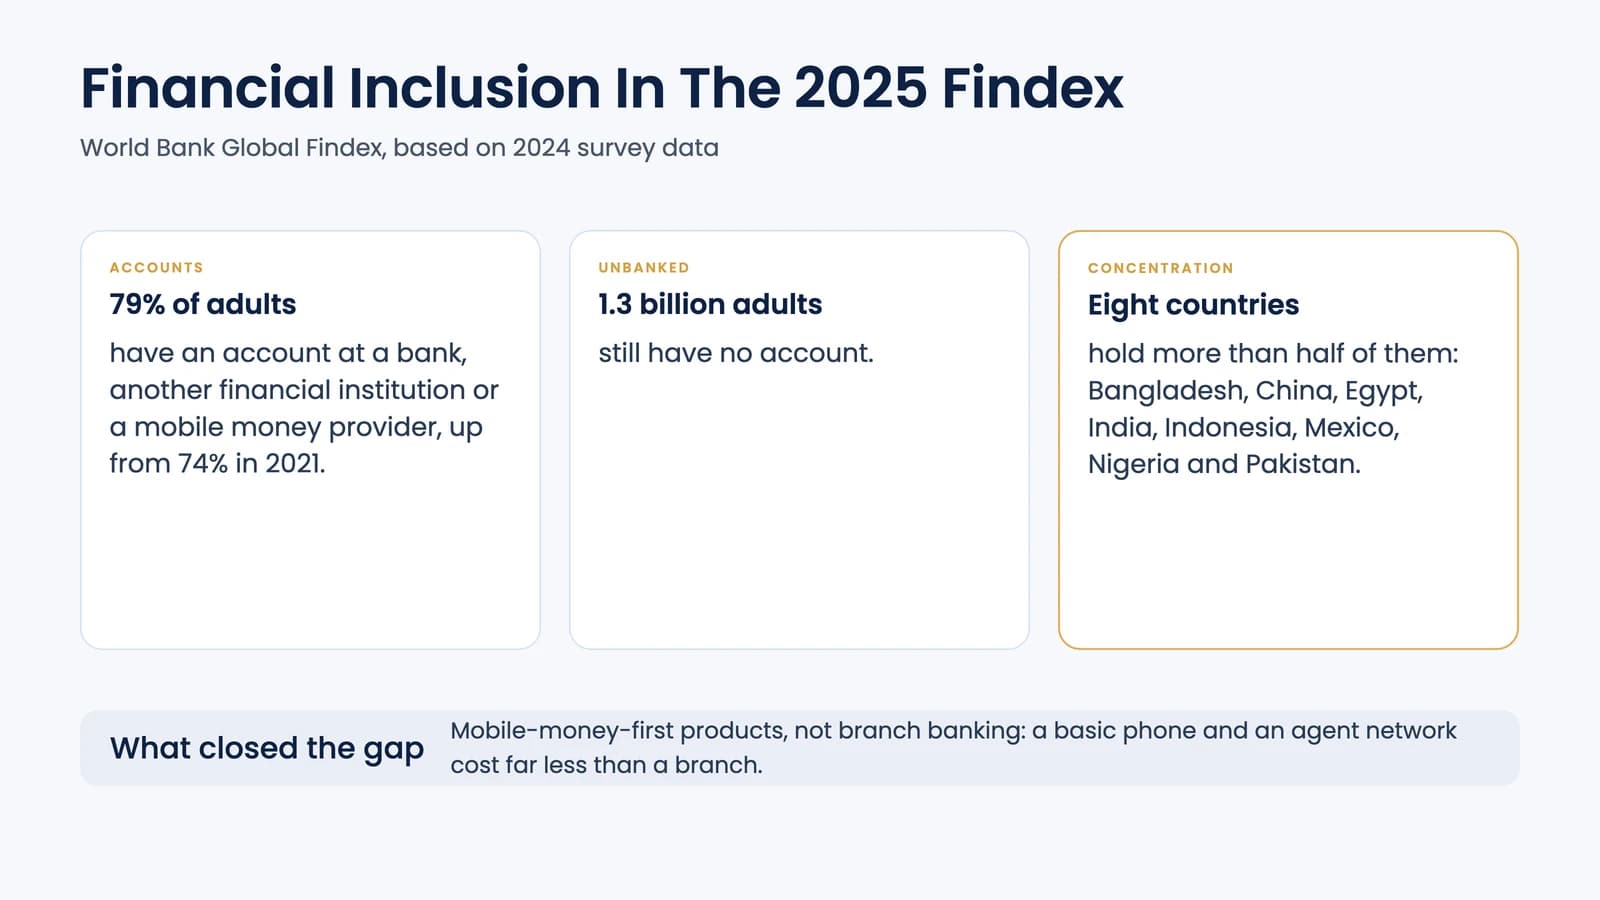
The World Bank's 2025 Global Findex report, based on 2024 survey data, found that 79% of adults worldwide now have an account at a bank, another financial institution, or a mobile money provider, up from 74% in 2021. That still leaves 1.3 billion adults unbanked, more than half of them concentrated in eight countries: Bangladesh, China, Egypt, India, Indonesia, Mexico, Nigeria and Pakistan.
Mobile-money-first products, not branch banking, have done most of the work closing that gap over the past decade, because a basic phone and an agent network cost far less to roll out than a branch. The same pattern that drove mobile money adoption, meeting people on infrastructure they already have, is now repeating with instant-payment rails and digital wallets in markets with younger banking systems.
What This Means for Builders
None of this removes the hard parts of building a payments product: licensing, fraud liability and reconciliation across rails do not get simpler just because the rails themselves got faster. Our guides on starting a fintech company and on product innovation in fintech cover the parts of the build that do not show up in a trends list.
Conclusion
The infrastructure behind payments has genuinely changed: rails settle faster, open banking is now mainstream, stablecoins carry real settlement volume, and AI handles more fraud screening and customer service than it did even two years ago. None of it replaces the underlying work of getting licensing, custody and reconciliation right.
Learn more from us
 Fintech news28 Sept 2026
Best Open Banking APIs for Digital Banks: Top 7 Providers
Compare 7 open banking API providers for digital banks: coverage, products and licensing, plus where PSD3, UK and US 1033 rules stand in 2026.
Vladislav Malynovskyi
 28 Sept 2026
AI in Finance: How AI Solutions Reshape the Financial Sector
AI in finance in 2026: fraud and AML, credit scoring, GenAI assistants, agentic payments, EU AI Act rules and how to start an AI project.
Olena Petrashchuk
 05 Sept 2019
4IRE Meetup in Sweden: Product Innovations in FinTech
Learn how 4IRE organized a meetup on fintech innovations with Chromia and Regtech Association, gathering the thriving fintech community in Sweden.
Olena Petrashchuk
Building a payments or fintech product?
Our team builds the infrastructure behind payment rails, open banking integrations and fraud tooling, not just the demo. Let's scope your build.
FAQ
Instant and programmable rails moving from consumer transfers into business treasury and cross-border payments, where approval cycles used to take days, not minutes.
Both, increasingly. Stablecoin supply passed $311 billion as of 30 September 2026 per DefiLlama, and a growing share of that volume is business-to-business settlement, not trading.
A regulated way for a customer to let a third-party app access their account data or initiate a payment directly through their bank's API, instead of the app screen-scraping a login page.
Mainly for real-time fraud scoring against behavioral patterns, and for handling routine customer service, balance checks, transfer requests, billing questions, through a conversational interface instead of a phone queue.