

 Payments & Banking

Peer-to-peer (P2P) payment apps let people send money to each other in seconds from a phone, using a phone number, email, username or QR code instead of bank details. What started as a way to split dinner bills now carries serious volume: in the US, Zelle users sent more than $1.2 trillion in 2025, and India's UPI processed 24.51 billion transactions in August 2026 alone, according to NPCI data.
That scale shows the demand, but also the bar. Users expect instant transfers, zero or tiny fees and bank-grade security. This guide walks through how to build a P2P payment app: the product decisions, licensing, core features, architecture, development process, monetization and the risks that sink new entrants.
Before You Develop a P2P Payment App
The code is rarely the hardest part. What decides success is made before development starts:
- choose the type of P2P app;
- define the problem it solves and for whom;
- decide how you will hold and move money legally;
- set the feature list and turn it into a clear brief.
Types of Peer-to-Peer Payment Apps
Standalone wallet apps. Independent apps such as Venmo (owned by PayPal) or Cash App hold a balance for the user and link to bank accounts and cards. They control the whole experience but need their own licenses or a licensed partner.
Bank-embedded P2P. Transfers built into a bank's own app, such as Zelle in the US, run on the bank's accounts and rails. This is the natural route for banks and neobanks adding P2P to a mobile banking app.
Super-app and social payments. Payments inside messaging or marketplace apps. They benefit from an existing user base but are usually built by the platform itself or its payments partner.
Cross-border and crypto P2P. Apps focused on remittances, often using stablecoins or local instant payment rails to cut cost and settlement time. Our guide to stablecoins explains how these tokens work and how they are now regulated.
Questions to Answer First
- Who is your audience? Friends and family, freelancers, migrant workers sending money home, families managing children's spending?
- What problem do you solve? Speed, cost, cross-border reach, shared expenses, or access for people underserved by banks?
- Which markets and currencies? This drives licensing, payment rails and localization.
- What will it connect to? Bank accounts, cards, other wallets, crypto, merchant checkouts. Each integration shapes the architecture.
Licensing and Compliance
Moving other people's money is a regulated activity almost everywhere. Typical routes:
- EU: a payment institution or e-money institution license, which can be passported across the EEA, or operating as an agent of a licensed firm.
- UK: authorization or registration with the FCA as a payment or e-money institution.
- US: state money transmitter licenses in most states plus FinCEN registration as a money services business, or a partnership with a sponsor bank.
Our overview of types of fintech licenses compares EMI, PSP and crypto licenses in more detail.
Two recent rules directly shape P2P product design. In the euro area, the Instant Payments Regulation has required euro-area banks to send instant euro transfers since 9 October 2025, and from the same date every euro-area provider of credit transfers, including payment and e-money institutions, must offer Verification of Payee, a name-and-IBAN check before the user confirms a payment. In the UK, payment firms must reimburse most victims of authorized push payment scams, up to £85,000 per claim, with the cost split between the sending and receiving firms. Fraud controls are therefore a direct cost line, not a nice-to-have.
You will also need KYC and AML screening, transaction monitoring, PCI DSS compliance if you store or process card data, and data protection compliance such as GDPR. This article is not legal advice; involve a payments lawyer in each target market before launch.
12 Must-Have Features for a P2P Money Transfer App
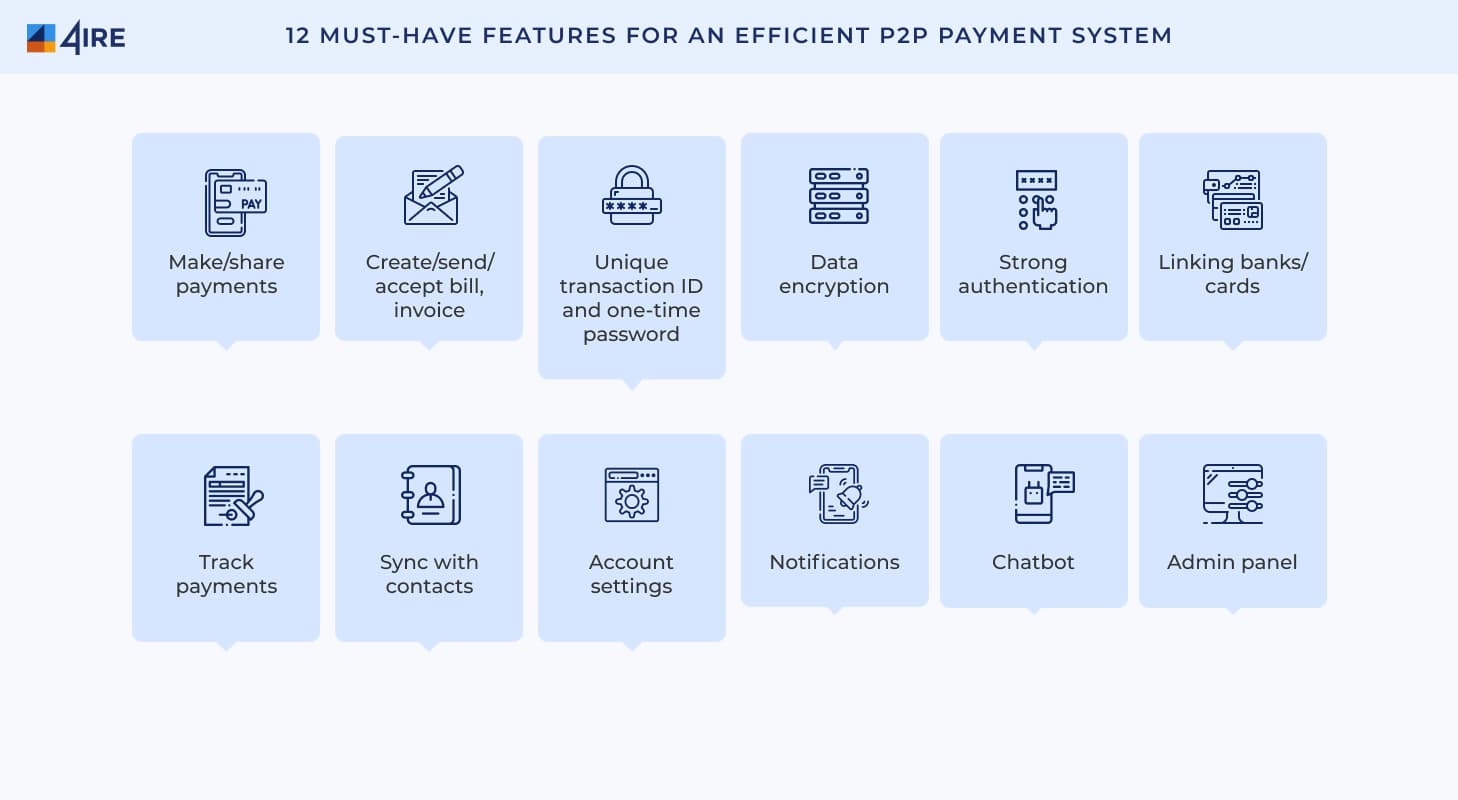
- Make and share payments: send money in real time to a contact, phone number or QR code, and split bills.
- Request money and invoices: let users request payment and, for small businesses, send simple invoices.
- Unique transaction ID and one-time passwords: every transfer gets a traceable ID; risky actions require an extra confirmation.
- Data encryption: encrypt data in transit and at rest, and tokenize card data.
- Strong authentication: biometrics, device binding and multi-factor login.
- Linking banks and cards: connect bank accounts through open banking or card rails so users can fund and withdraw.
- Payment tracking: clear status and history for every transfer, which also supports disputes and record-keeping.
- Contact sync: pay people from the phone's contact list instead of typing details.
- Account settings: limits, default funding source, privacy and notification preferences.
- Notifications: instant alerts for incoming money, requests and suspicious activity.
- In-app support and chatbot: answer routine questions and route disputes to a human.
- Admin panel: operations, compliance and support teams manage users, limits, refunds and cases.
Architecture and Payment Rails
Under the interface, a P2P app is a ledger with integrations around it. The core pieces are:
- A double-entry ledger that records every balance movement exactly once and can be reconciled daily against bank and partner statements.
- Payment rails: card networks for funding, ACH, RTP and FedNow in the US, SEPA Instant in the euro area, Faster Payments in the UK, and local schemes such as UPI or Pix where you operate.
- Open banking for account linking and pay by bank; our comparison of the best open banking APIs covers the main providers.
- Identity, fraud and AML services for onboarding, sanctions screening and real-time transaction scoring.
- Wallet and custody components if you hold balances in stablecoins or other digital assets, as described in our guide to building a mobile wallet app.
Plan for growth from the start. Features are added in layers, and a ledger or data model designed only for an MVP becomes expensive to change once real money flows through it.
How to Develop a P2P Payment App
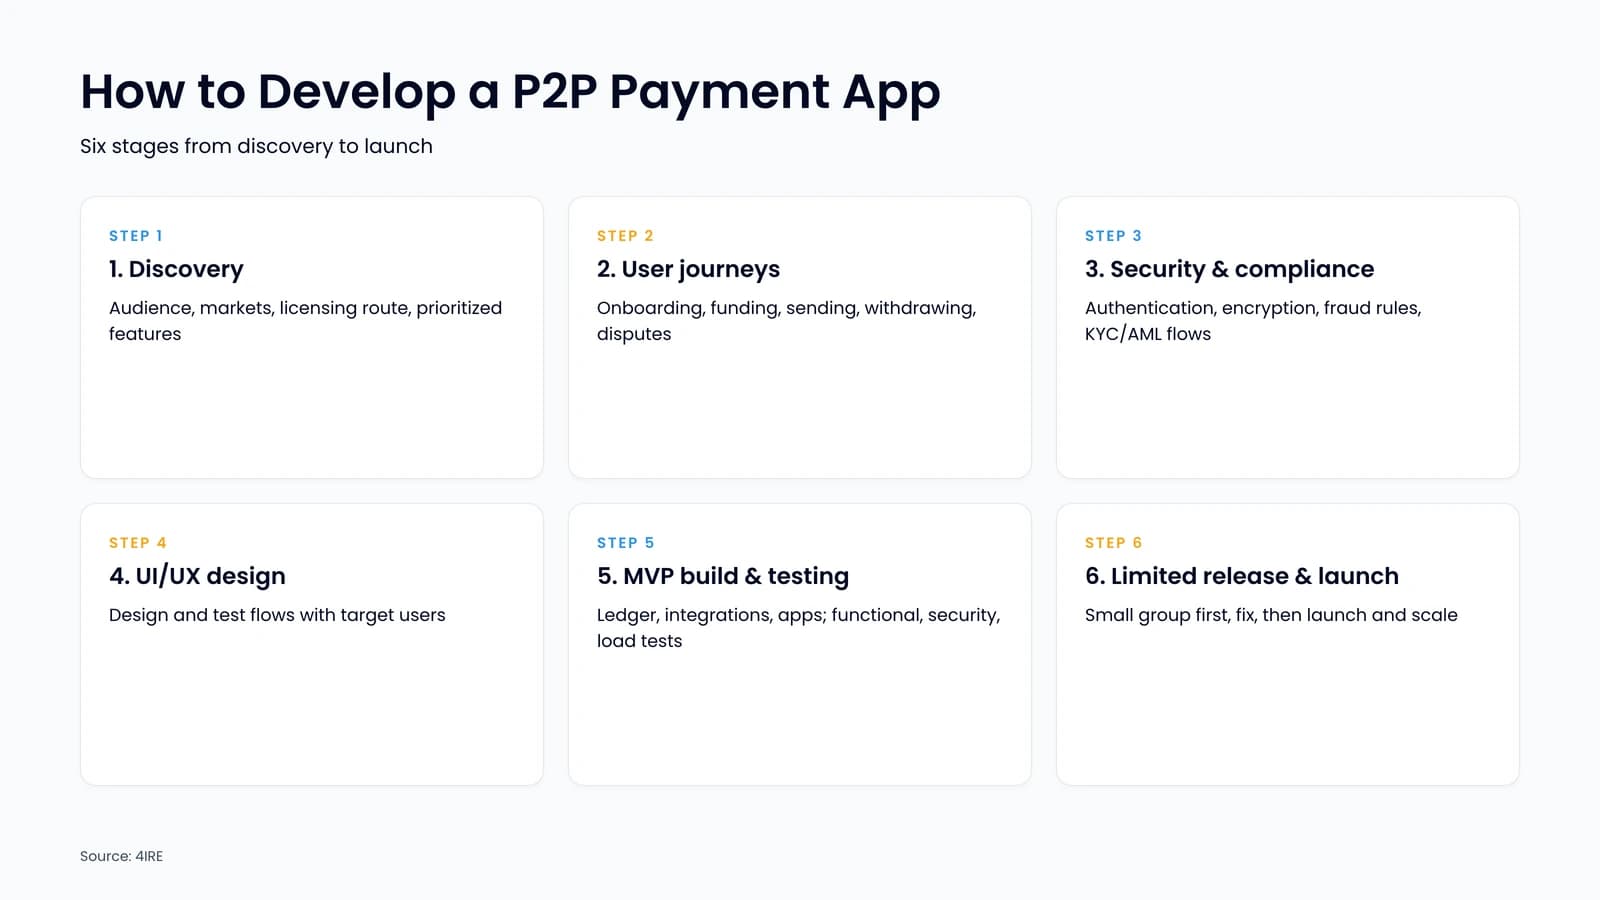
- Discovery: define audience, markets, licensing route and a prioritized feature list.
- User journeys and features: map the key flows (onboarding, funding, sending, withdrawing, disputes) and the features each needs.
- Security and compliance design: plan authentication, encryption, fraud rules and KYC/AML flows before UI work starts.
- UI/UX design: design and test the flows with real users from your target segment.
- MVP development and testing: build the ledger, integrations and apps, then run functional, security and load tests.
- Limited release and launch: open to a small group, fix what you learn, then launch and scale.
How to Monetize a P2P Payment App
Free person-to-person transfers are the norm, so revenue usually comes from around them:
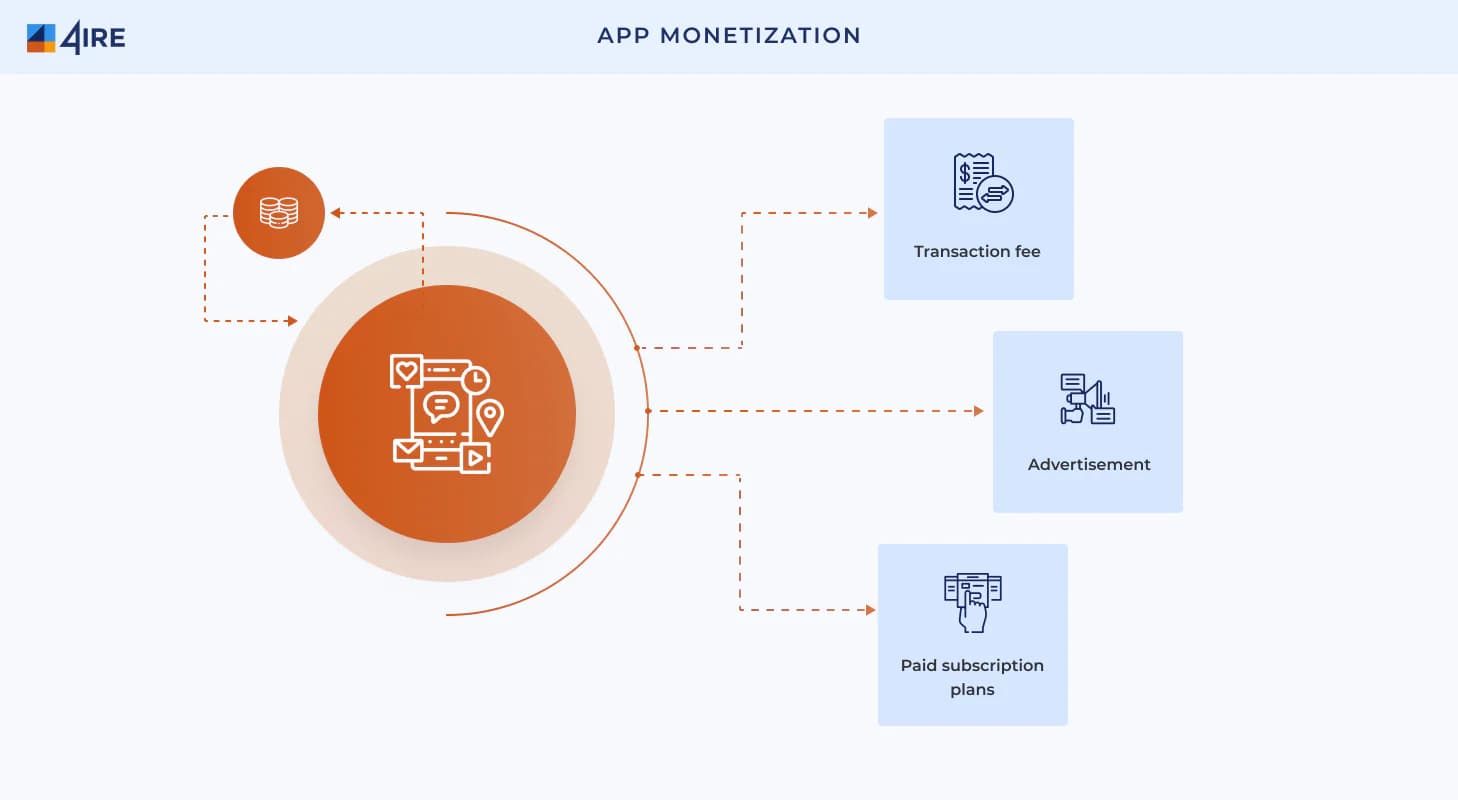
- Transaction fees on instant withdrawals, card-funded transfers or business payments.
- FX margins on cross-border and multi-currency transfers.
- Paid subscription plans with higher limits or premium features.
- Card interchange if you issue debit cards linked to the wallet.
- Advertising and partner offers, used carefully so they do not undermine trust.
Common Challenges and How to Handle Them
Fraud and scams. Instant, irrevocable payments attract fraud. Combine Verification of Payee or confirmation-of-payee checks, behavioral analytics, limits for new accounts and warnings on risky payments.
Security of user data. Follow PCI DSS where card data is involved, run regular penetration tests and monitor continuously. A single breach can end a young payments brand.
Disputes. Transfers fail or go to the wrong person. Build a clear dispute flow with tracking and a support team empowered to investigate and, where rules require, refund.
The Bottom Line
The P2P market rewards focus. Rather than cloning Venmo, find a segment with a real payment problem, secure the right license or partner, and build a secure ledger and fraud stack before adding features.
4IRE's financial software development team builds payment apps, wallets and the compliance tooling behind them. If you are planning a P2P or remittance product, we can help you choose the rails and architecture that fit your market.
Build Your P2P Payment App with 4IRE
Planning a P2P, wallet or remittance app? Our team will help you choose the licensing route, payment rails and architecture. Book a free consultation.
FAQ
A secure sign-up with KYC, account and card linking, a ledger that tracks balances, instant send and request flows, notifications, transaction history, strong authentication, fraud monitoring and an admin panel for operations and support.
Usually yes, or a licensed partner. In the EU and UK that means a payment or e-money institution license (or acting as an agent of one); in the US it typically means state money transmitter licenses and FinCEN registration, or working through a sponsor bank.
Stablecoins on public blockchains can make cross-border transfers faster and cheaper and settle around the clock. They add their own requirements, including wallet security, custody and compliance with rules such as MiCA in the EU and the GENIUS Act in the US.
Typical revenue comes from instant-withdrawal and card-funding fees, FX margins on cross-border payments, subscriptions, card interchange and partner offers.