


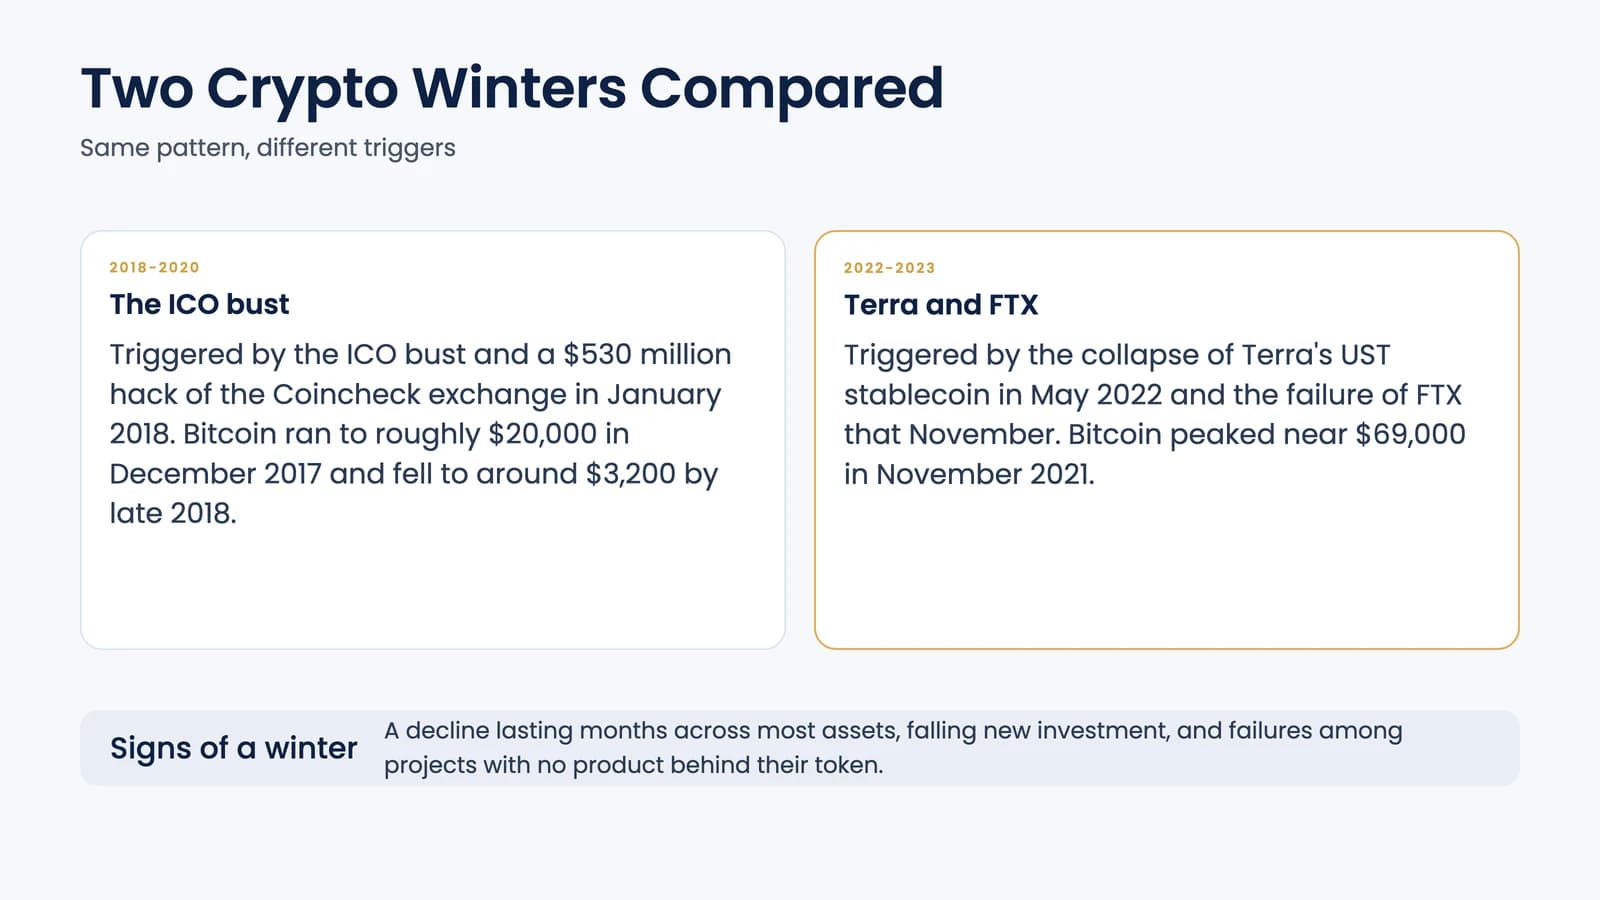
Crypto markets have been through two sustained downturns since 2017: 2018-2020, triggered by the ICO bust and a $530 million hack of the Coincheck exchange in January 2018, and 2022-2023, triggered by the collapse of Terra's UST stablecoin in May 2022 and the failure of FTX that November. Both times, most projects with live products and real users kept building through the decline. This article looks at ten projects that launched during the first of those winters, between 2017 and 2020, and checks where each one stands in October 2026.
What Is a Crypto Winter?
A crypto winter is a sustained, broad decline in crypto asset prices, usually following a period of rapid price growth and new project launches. Market watchers generally point to the same signs:
- A decline lasting months, not weeks, spread across most major assets, not just one token.
- Falling new investment in crypto projects and a slower pace of new launches.
- A round of failures among projects that had no product behind their token, followed by consolidation around the ones that did.
The 2018-2020 winter followed Bitcoin's run to roughly $20,000 in December 2017; by late 2018 it had fallen to around $3,200. The 2022-2023 winter followed Bitcoin's November 2021 peak near $69,000, and the Terra and FTX collapses turned a correction into a crisis of confidence in centralized platforms specifically, not in the underlying technology.
The Lesson: a Downturn Clears Out Weak Projects, Not Working Ones
Both winters removed the same kind of project: ones whose token price, not usage, was the whole business case. LUNA and UST are the clearest case, built on a stablecoin design that needed continuous growth to stay solvent. FTX failed for an unrelated reason, mismanagement and misuse of customer funds at a centralized exchange, which is a governance failure rather than a crypto-winter casualty, but it deepened the 2022 downturn regardless.
What a downturn does not reliably remove is a project with a working product and paying or active users, which is why several projects that launched during the 2018-2020 winter, when funding was hardest to raise and attention was lowest, are still operating, and in most cases still leading their category, in 2026.
10 Projects Launched in the 2018-2020 Crypto Winter, and Where They Stand Now
| Project | Launched | Built for | Status, October 2026 |
|---|---|---|---|
| Solana | 2020 | High-throughput smart contracts | Still a top-tier L1 by usage and market cap ($69.1B, CoinGecko, 1 Oct 2026). |
| Uniswap | 2018 | Automated market-making DEX | The largest on-chain exchange by volume on Ethereum; $5.7B market cap. |
| Chainlink | 2019 | Decentralized oracle network | The dominant oracle provider for DeFi and tokenized assets; $10.8B market cap. |
| NEAR Protocol | 2020 | Sharded, developer-friendly L1 | Active sharded mainnet; $6.5B market cap. |
| Polkadot | 2020 | Cross-chain interoperability | Parachains live; migrated to Polkadot Hub in November 2025; $2.0B market cap. |
| Tezos | 2018 | Self-amending proof-of-stake smart contracts | Two protocol upgrades shipped in 2026 (Tallinn, Ushuaia); $349M market cap. |
| MakerDAO (now Sky) | 2017 | Decentralized, overcollateralized stablecoin | Rebranded to Sky in August 2024, MKR to SKY; $1.9B market cap on the new token. |
| 1inch | 2019 | DEX aggregation | Still routes trades across many DEXs; $143M market cap. |
| Axie Infinity | 2018 | Play-to-earn NFT game | Still live and updated, but daily players are a fraction of the 2021 peak of 2.7 million; $199M market cap. |
| Rarible | 2020 | General-purpose NFT marketplace | The marketplace is still trading and expanded onto Solana in August 2026 under new owner IMPOSSIBLE, which bought the brand in June 2026, but its RARI token has fallen to a $3.2M market cap. |
Market caps above are from CoinGecko, taken 1 October 2026; they move daily and are included to show scale, not as investment guidance.
Two of the ten are worth a closer look because the project and its token tell different stories. Rarible the marketplace is still operating and growing its chain support, but RARI, its governance token, has fallen more than 99% from its peak: a platform can survive a winter while its token does not. MakerDAO dropped its own name in the August 2024 rebrand to Sky, after most MKR holders chose not to convert to the new SKY token at first; the protocol kept running under either name, but a rebrand carries real risk of its own if the community does not follow.
What This Means for a New Project Today
None of this argues for timing a launch to a downturn on purpose. It argues against waiting for ideal conditions that a cyclical market will not provide. The ten projects above raised money, shipped a working product and kept their users through a funding drought most startups never face. A team with the same discipline does not need a bull market to get started; it needs a product people will use regardless of where the price chart is.
Two traits separate the projects on this list from the ones that did not make it past 2020. Each either shipped its mainnet or reached a usable product during the downturn itself, without waiting for better conditions to launch. And each had a revenue or usage model that did not depend on its own token price staying high, whether that was trading fees, protocol fees or demand for the service itself. Neither trait requires a bull market; both require a product worth using before the market decides to notice.
FAQ
Usually a mix of a sharp price correction after a speculative run, and a shock that breaks confidence in a widely held asset or platform. The 2018 winter followed the ICO boom and a major exchange hack; the 2022 winter followed the collapse of the Terra stablecoin and the failure of the FTX exchange.
Not based on this list: Solana, Uniswap and Chainlink, all launched in the 2018-2020 winter, lead their categories in 2026. A downturn reduces funding and attention, which is a real cost, but it does not appear to cap how far a project with real usage can go once conditions improve.
Market timing matters less than product-market fit and runway. A project that needs continuous new investment to survive is vulnerable in any downturn; one with paying users or a working core use case can be built and shipped in a down market, as every project in this list was.