

An initial coin offering (ICO) was, for a few years in the mid-to-late 2010s, the default way a blockchain project raised money: sell a new token directly from the project's own website, with no exchange, launchpad or regulator standing between the buyer and the issuer. It largely doesn't work that way anymore.
This guide explains what an ICO was, how the model rose and fell, and why most token launches today go through an IDO, an IEO, or a fully regulated offering instead. It's written as history and context, not as a recommendation. If you're planning a token launch in 2026, the practical guidance is in our companion articles on IDOs and crypto fundraising, not this one.
What Was an ICO?
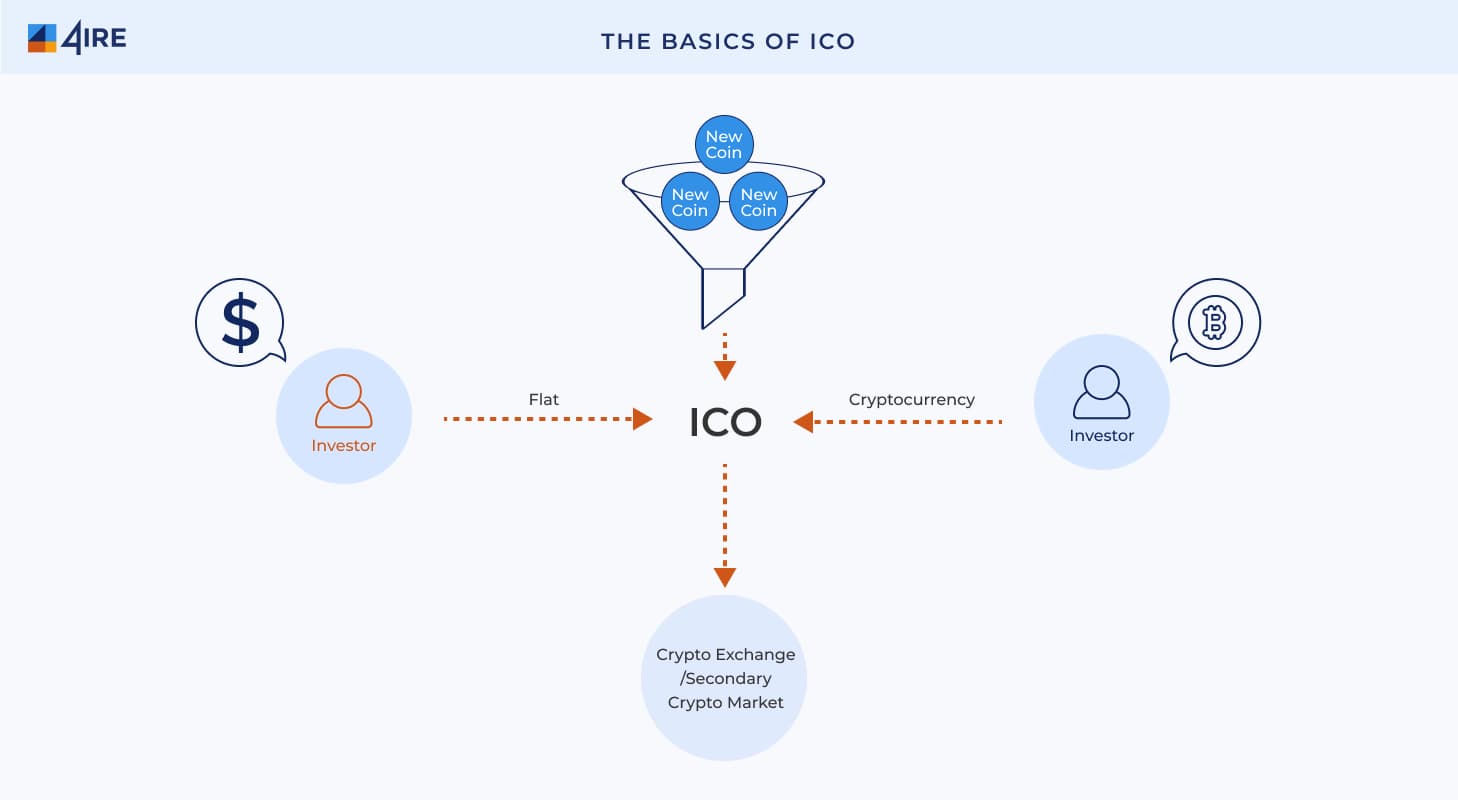
An ICO is often compared to an IPO, but the two work differently. In an IPO, a company sells shares (a stake in the business, with voting rights and a legal claim on profits). In an ICO, a project sold tokens, which in most cases granted no ownership or vote at all; buyers were purchasing a digital asset they hoped would rise in value or become useful once the project shipped.
Most ICOs fell into one of two categories: utility tokens, which promised early access to a product or service once launched, and equity-like or security tokens, which behaved more like the IPO model by offering a claim closer to ownership, and which, as regulators later made clear, were often securities in substance regardless of what they were called.
How an ICO Worked
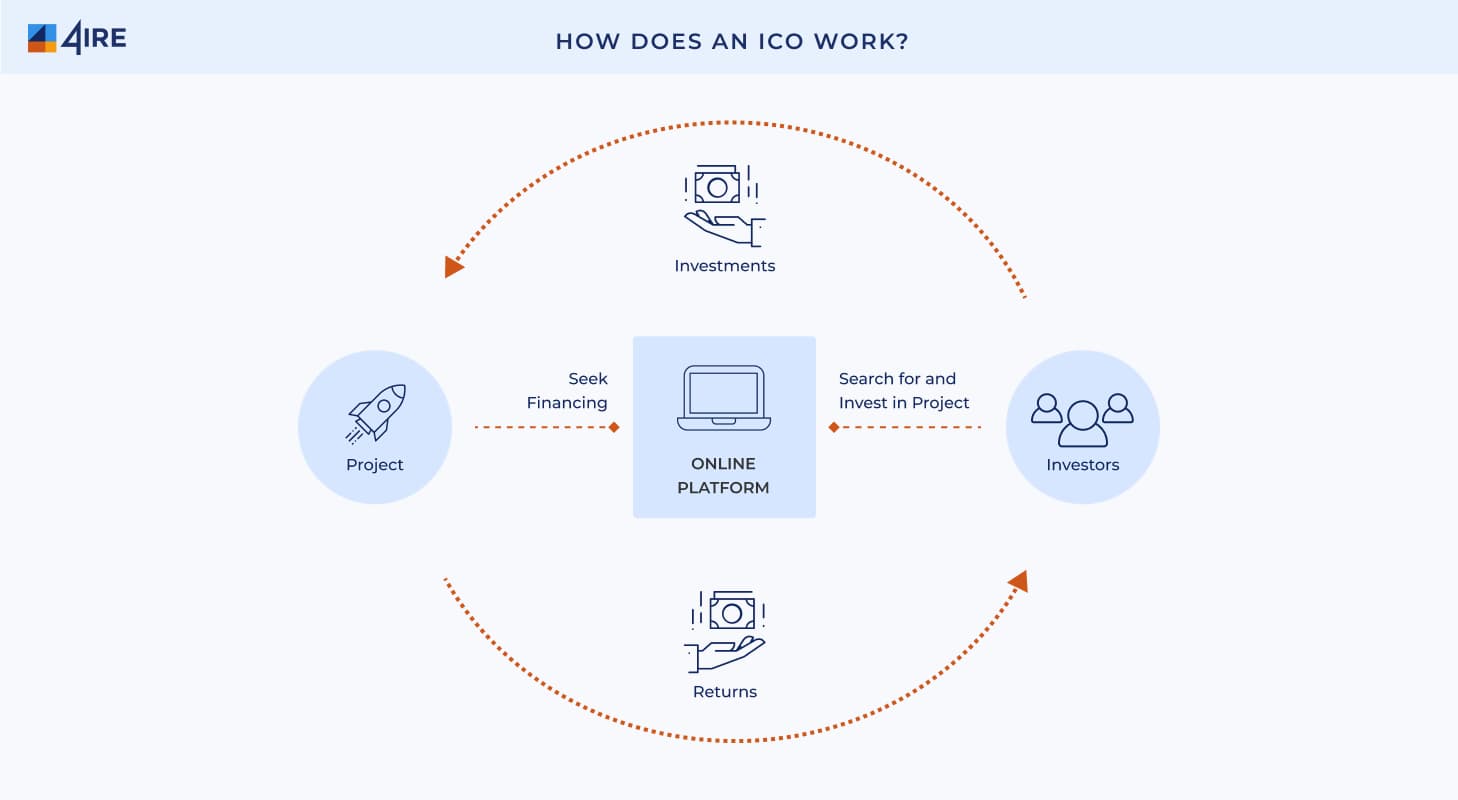
A project published a whitepaper describing the problem, the token's intended utility, the team, and how raised funds would be spent. Investors sent cryptocurrency (usually BTC or ETH) directly to a project-controlled address in exchange for newly issued tokens, with no exchange or launchpad vetting the offer beforehand. Once the sale closed, the token might (or might not) get listed on an exchange, at which point it became tradable.
The ICO Boom and Bust
Mastercoin ran one of the first widely cited token sales in 2013. Ethereum's 2014 presale, which raised roughly 31,000 BTC over a public sale that ran from July to August of that year, is generally credited with putting the model on the map. Ethereum's mainnet later launched in July 2015.
ICO activity stayed modest until 2016–2017, when it expanded sharply. By the peak of the boom in late 2017, ICOs were collectively raising well over a billion dollars a year worldwide, and mainstream financial press had started covering the phenomenon as a serious, if speculative, funding class. That peak coincided with a wave of regulatory attention: the US SEC published its Report on The DAO in July 2017, concluding that tokens sold in that case qualified as securities under existing federal law, and China banned ICOs outright on 4 September 2017, ordering issuers to refund investors.
Fundraising volumes fell substantially through 2018 as regulatory enforcement increased and crypto asset prices declined sharply, a pattern commentators have since compared to earlier speculative bubbles. A large share of ICO-era projects turned out to be scams or simply never shipped a product, which is the main reason the model lost investor trust faster than it gained it.
Historically Notable ICOs
A handful of ICO-era projects are still cited as reference points for how the model played out. Stratis launched its ICO in 2016 to fund a blockchain-as-a-service platform. Tezos ran a large 2017 token sale to fund a self-amending blockchain, though its rollout was delayed for over a year by internal governance disputes and litigation before its network launched in September 2018. Filecoin raised heavily in a 2017 sale to build a decentralized storage network, then took until late 2020 to ship its mainnet, a reminder that a large raise didn't guarantee a fast, or even eventual, working product. We've left out ICO-era price and ROI figures here, since token prices from that period are not a reliable guide to any project's current state.
Why the Model Lost Investor Trust
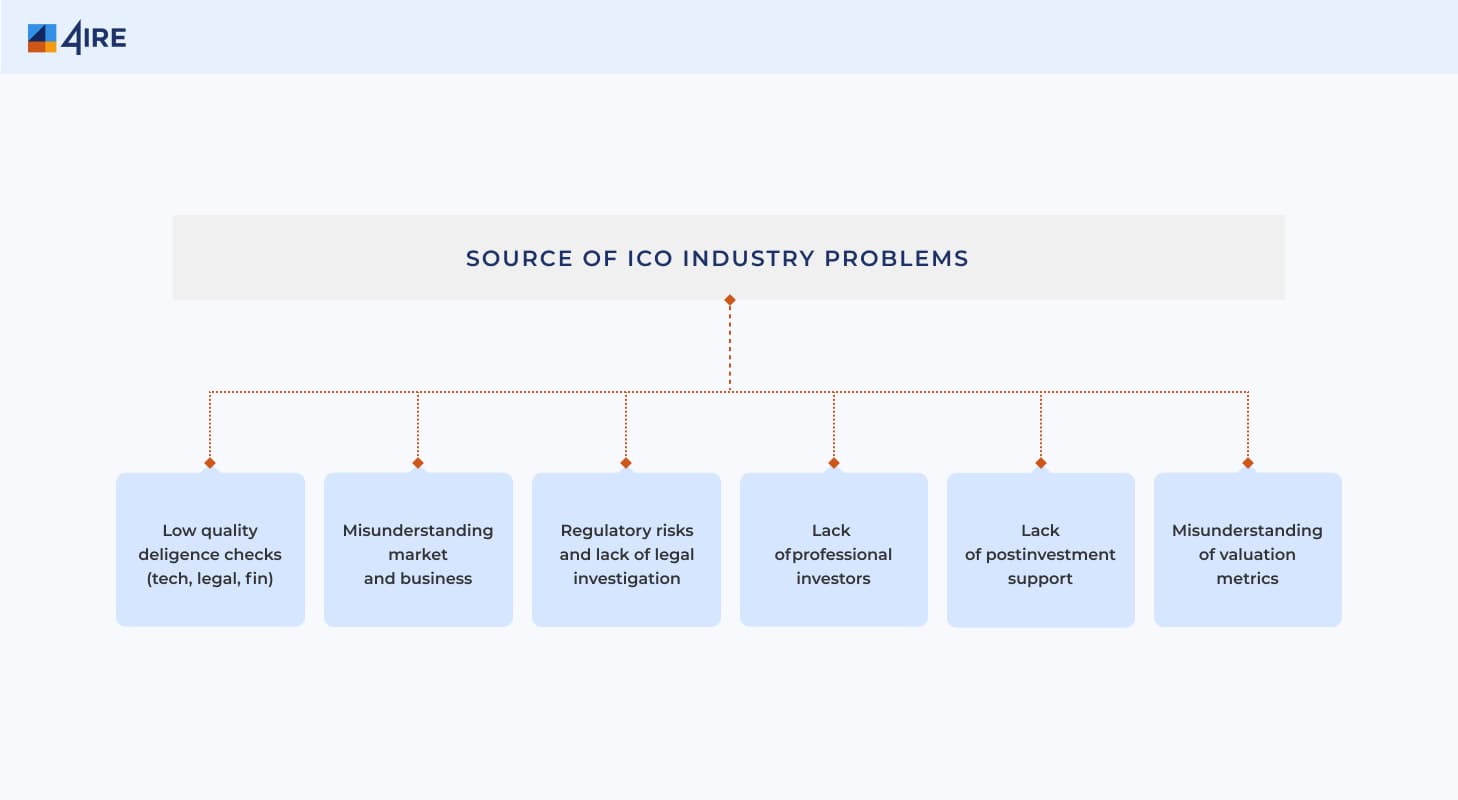
The structural weaknesses that undermined ICOs are the same ones later fundraising models were built to fix: no independent screening of the issuer, whitepapers that ranged from optimistic to fabricated, teams with no verifiable track record, and essentially no legal recourse if a project disappeared after the raise. Regulators in the US, China and elsewhere responded with enforcement action and, eventually, dedicated frameworks, which is what pushed the market toward models with a built-in screener.
What Replaced the ICO Model
Three models absorbed most of the fundraising activity that used to go through ICOs. IEOs moved the sale onto a centralized exchange, which vets projects and usually requires KYC. IDOs moved it onto a decentralized exchange or launchpad, keeping the speed of a crypto-native raise while adding a screening layer. See the two guides linked above for how each works today. And for projects tokenizing a real asset or share rather than selling a pure utility token, security token offerings formalized what some ICOs were doing anyway, inside an actual securities framework.
Where This Leaves ICOs Today
A raise structured like a classic 2017-style ICO (no launchpad, no exchange, no compliance review) would run into real trouble in most major markets today. In the EU, MiCA's rules for public offers of crypto-assets, including a mandatory compliant white paper, have applied in full since 30 December 2024, and the transitional authorisation period for crypto-asset service providers ended 1 July 2026. In the US, a token offered and sold in a manner that meets the Howey test is treated as a security, with the registration and disclosure obligations that implies, largely the same standard the SEC applied in its 2017 DAO report. None of this is legal advice; a project weighing any public token sale in 2026 needs jurisdiction-specific counsel, not a decision based on how things worked in 2017.
How 4IRE Can Help
If a token launch is part of your roadmap, 4IRE builds and audits the smart contracts behind it and advises on which launch model (an IDO, an IEO, or a fully tokenized security offering) fits your project and its regulatory footprint. Get a smart contract audit scoped before any public sale, regardless of which model you choose.
Conclusion
The ICO's legacy isn't the fundraising model itself, which few serious projects use unmodified today; it's the lesson every model since has tried to build in: some form of independent screening between the issuer and the investor. Understanding why ICOs failed that test is more useful to a 2026 founder than trying to run one.
Planning a Compliant Token Launch?
Talk to our team about smart contract development, audits and choosing a launch model that fits your project today.
FAQ
Rarely in their original 2017 form. Most token launches now go through an IDO, an IEO, or a compliant security token offering, each of which adds a screening or regulatory layer that a classic ICO lacked. A handful of small or niche projects still call their sale an 'ICO,' but the surrounding compliance work looks very different from 2017.
An ICO was run directly by the issuing project on its own site, with no independent screener. An IDO is hosted by a decentralized exchange or launchpad, which vets the project and supplies the liquidity that lets the token trade immediately after the sale, a structural fix for the ICO model's lack of oversight.
Regulatory enforcement increased sharply (the SEC's July 2017 Report on The DAO and China's September 2017 ICO ban were early, high-profile actions), while a large share of ICO-era projects turned out to be scams or never shipped, eroding investor trust faster than new capital could replace it.
It depends entirely on jurisdiction and structure. In the EU, MiCA's public-offer and white paper rules already apply to crypto-asset offerings. In the US, a token sold in a way that meets the Howey test is treated as a security. Get jurisdiction-specific legal advice before structuring any public token sale.