

 Fintech news
Every loan decision is a bet on whether the borrower will repay. A credit scoring system turns that bet into a number: it combines data about an applicant into a score that estimates the probability of default, and the lender uses it to approve, decline, price and set limits.
Done well, credit scoring lets a lender grow its book without growing losses. Done badly, it either turns away good customers or lets risky ones through, and increasingly it also creates regulatory exposure. This article explains how credit scoring works in 2026, how AI and new data sources are changing it, what the new EU rules require, and how to build a reliable credit scoring system for a bank, neobank or lending app.
How Traditional Credit Scoring Works
Classic scores are built from credit bureau data. The best-known example, the FICO Score used by most US lenders, weighs five categories: payment history (35%), amounts owed (30%), length of credit history (15%), credit mix (10%) and new credit (10%), according to myFICO. Many countries have their own bureau scores built on similar logic.
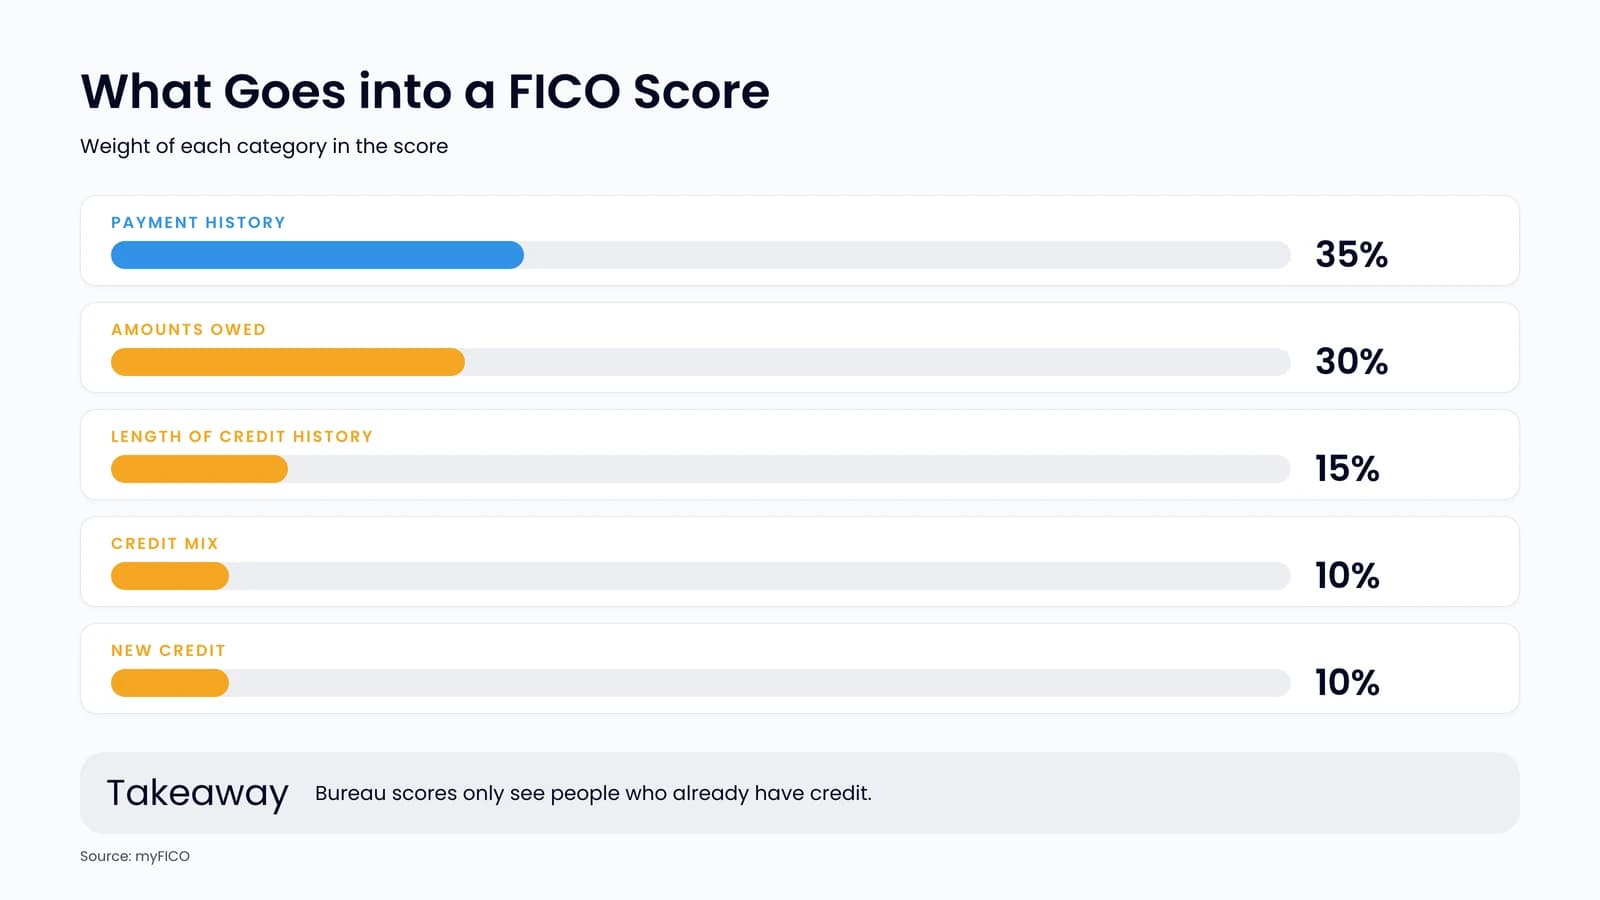
The weakness is that bureau scores only see people who already have credit. According to the World Bank's Global Findex 2025, 79% of adults worldwide now have an account, which still leaves roughly one in five without one, and far more have little or no credit history. Young people, migrants, the self-employed and small businesses are often "thin-file": not risky, just invisible to the model.
Scoring is shifting even in mature markets. In the US, Fannie Mae and Freddie Mac now accept VantageScore 4.0, which can also take rent payment history into account, alongside Classic FICO for mortgages they buy, according to the FHFA.
Credit Scoring Trends in 2026
AI and Machine Learning Models
Gradient-boosted trees and other machine learning models can capture non-linear patterns that traditional scorecards miss, and they update faster as data changes. Our overview of AI in finance covers broader use cases. The trade-off is explainability: a lender must still be able to say why an applicant was declined, so many teams pair ML models with interpretable scorecards or explanation techniques.
Cash-Flow Data from Open Banking
With the customer's consent, open banking lets lenders read real income, recurring expenses and balance history directly from bank accounts. For thin-file applicants, this cash-flow data is often more predictive than a sparse bureau file. Our comparison of the best open banking APIs covers the main data providers.
Multiple Data Sources, Carefully Chosen
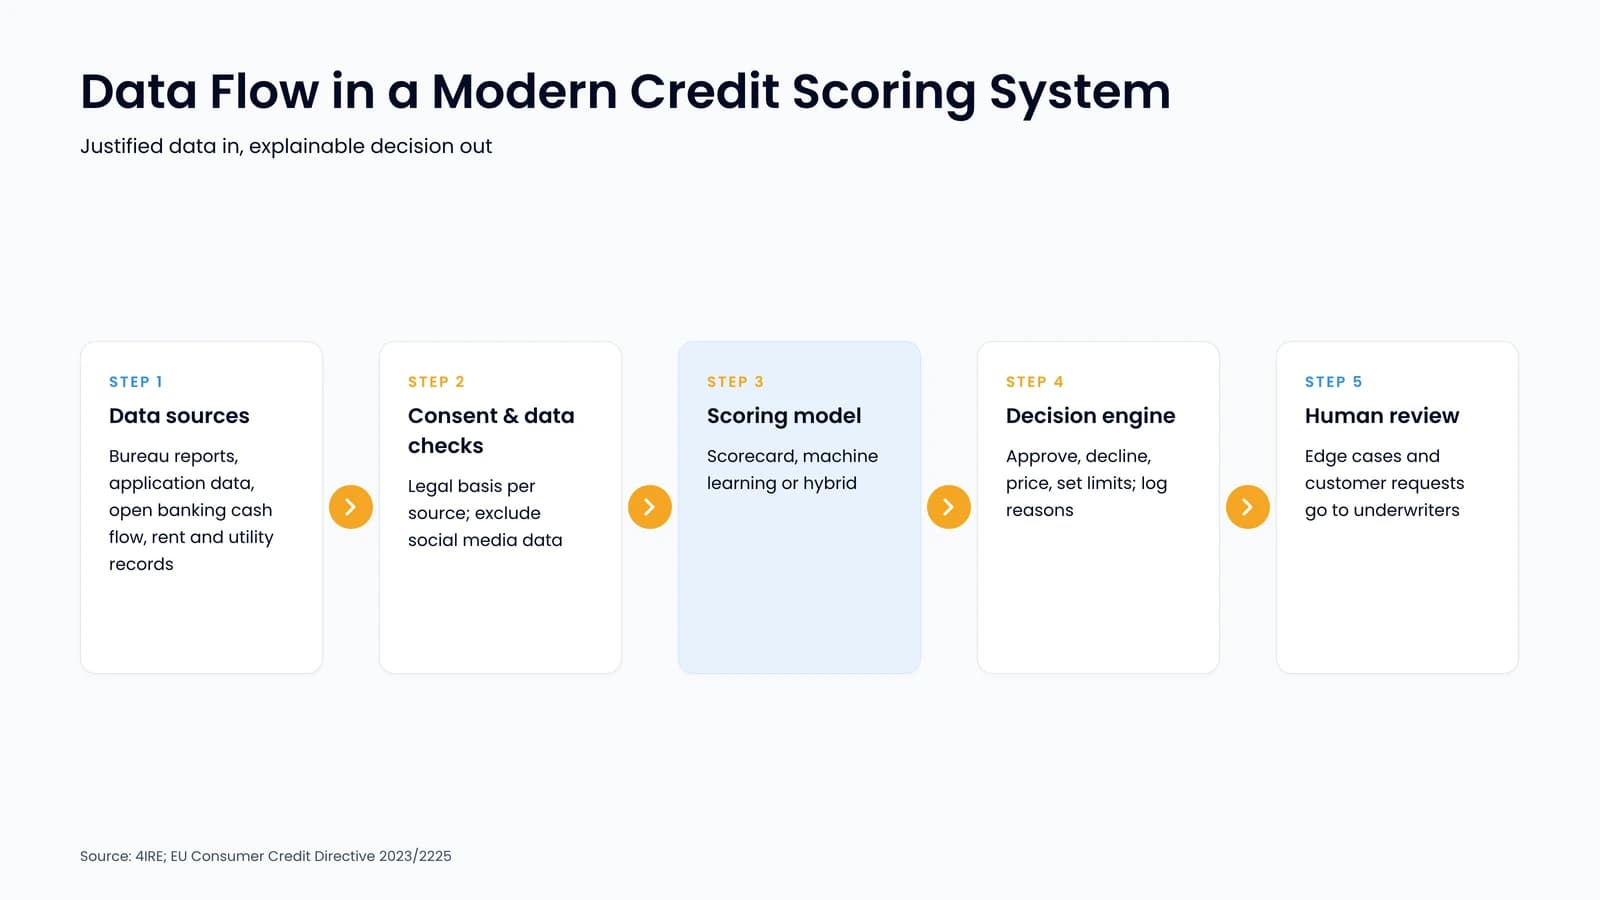
Modern systems combine bureau reports, application data, bank transactions, rent and utility payment records and, for businesses, accounting and e-commerce data. What they increasingly exclude matters as much: data that is hard to justify or explain, such as social media activity, is being pushed out by regulation.
Regulation: Credit Scoring Is Now High-Risk AI
Credit scoring has become one of the most regulated uses of AI.
- EU AI Act. AI systems used to evaluate the creditworthiness of individuals or establish their credit score are classified as high-risk (fraud detection is excluded). After the Digital Omnibus amendment, the obligations for these systems apply from 2 December 2027 instead of August 2026. They include risk management, data governance, technical documentation, logging, human oversight and accuracy and robustness testing.
- EU Consumer Credit Directive (2023/2225). From 20 November 2026, lenders may not use data from social networks in creditworthiness assessments, and consumers subject to automated assessments can request human intervention, an explanation and a review of the decision.
- GDPR. In its 2023 SCHUFA judgment (C-634/21), the EU Court of Justice held that a credit score can itself be an automated decision when a lender relies on it heavily, which triggers the GDPR's rules on automated decision-making.
- US. Under the Equal Credit Opportunity Act, lenders must give specific reasons when they decline an application, whether the model is a scorecard or machine learning.
The practical consequence: explainability, bias testing and documentation are no longer optional features. They need to be designed into the system from the start.
Ready-Made vs Custom Credit Scoring Solution
You can buy a scoring product and plug it into your loan origination flow, or build a custom model around your own data and customer segment.
| Ready-made credit scoring solution | Custom credit scoring solution |
|---|---|
| Lower upfront cost | Higher upfront investment |
| Fast integration and time to market | Longer development and validation cycle |
| Vendor handles model updates and documentation | You own the model, data pipeline and documentation |
| Limited control over features, data sources and logic | Full control over data sources, features and decision rules |
| Same model as competitors using the vendor | Scoring tuned to your segment becomes a competitive advantage |
Many lenders start with a vendor score and bureau data, then add a custom layer once they have enough repayment history of their own. A hybrid approach keeps time to market short while building a proprietary model over time.
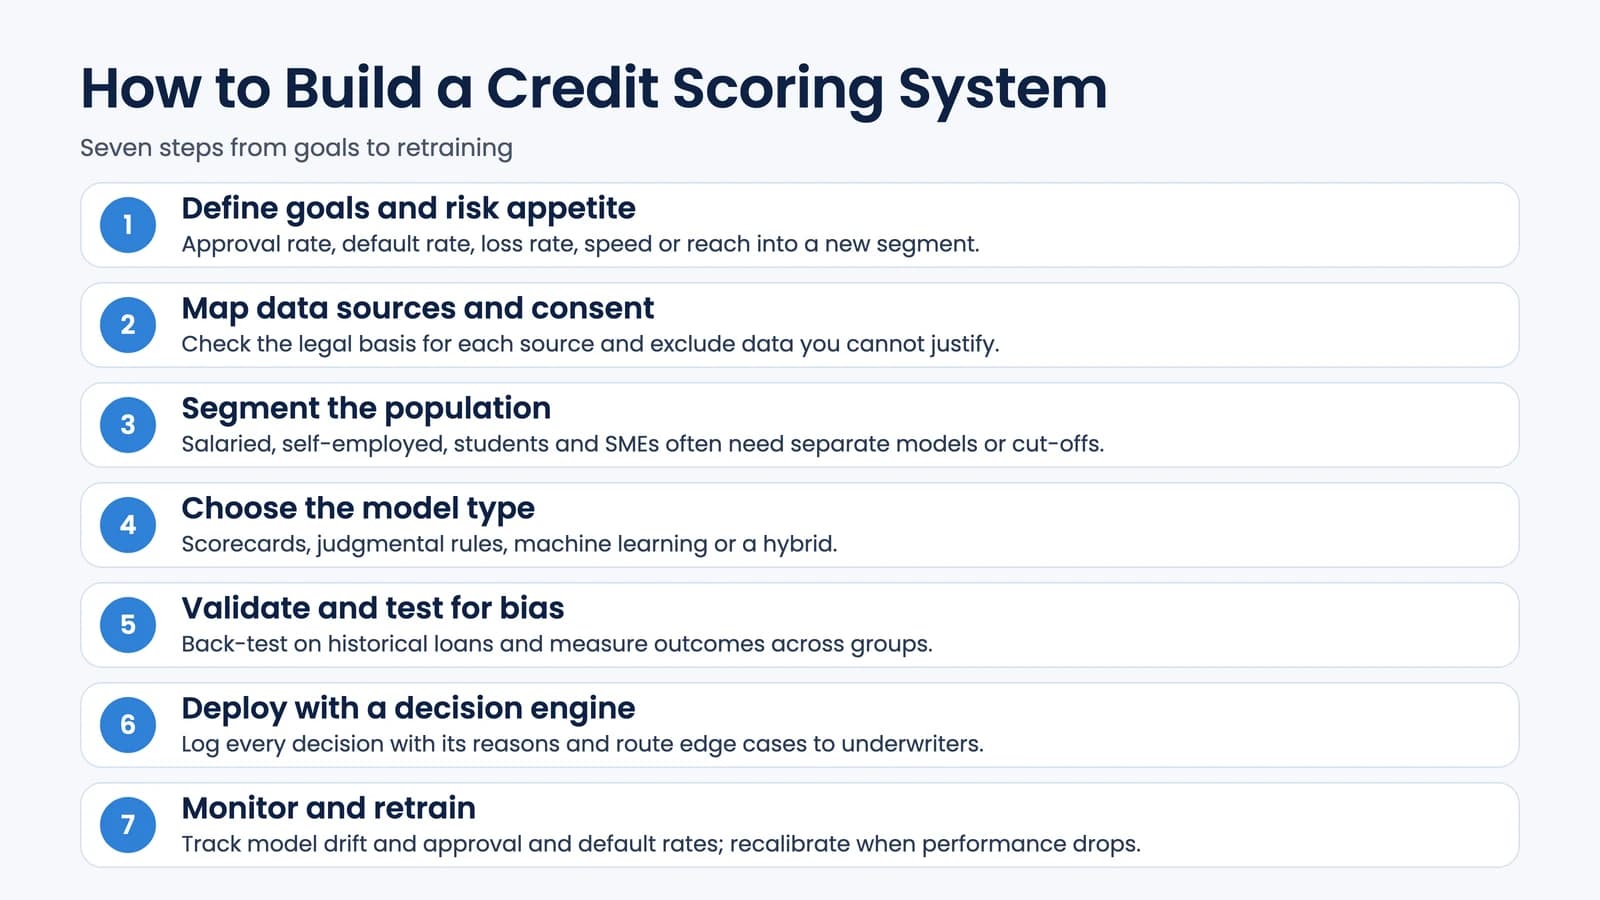
How to Build a Credit Scoring System
- Define goals and risk appetite. Decide what the system must optimize: approval rate, default rate, loss rate, speed, or reach into a new segment.
- Map data sources and consent. List bureau, application, open banking and internal data, check the legal basis for each source, and exclude data you cannot justify.
- Segment the population. Salaried employees, the self-employed, students and SMEs behave differently and often need separate models or cut-offs.
- Choose the model type. Statistical scorecards, judgmental rules, machine learning, or a hybrid, balancing accuracy against explainability.
- Validate and test for bias. Back-test on historical loans, check stability over time and measure outcomes across groups before going live.
- Deploy with a decision engine and human review. Connect the model to your loan origination system, log every decision with its reasons, and route edge cases to underwriters.
- Monitor and retrain. Track model drift, approval and default rates monthly or quarterly, and recalibrate when performance drops.
Include these requirements in the technical brief for your financial software development partner, so the model, data pipeline and audit trail are built together rather than bolted on.
Benefits of Automated Credit Scoring
- Faster decisions, often in seconds instead of days
- More consistent decisions and fewer manual errors
- Access to new customer segments without taking on uncontrolled risk
- Better pricing and limit setting based on individual risk
- A full audit trail that supports regulators, auditors and customer complaints
- Lower operating costs in underwriting
How Credit Scoring Affects Bank Profits
Better scoring improves profitability in three ways. It reduces credit losses by declining or repricing applicants who are likely to default. It increases revenue by approving good borrowers that a cruder model would reject. And it lowers the cost of underwriting through automation, which improves the cost-to-income ratio (lower is better). For credit-led fintechs, scoring quality is often the difference between a profitable book and a failed one; our case study on building a neobank like Plata shows how a credit-first model shapes the whole product.
Conclusion
A reliable credit scoring system in 2026 is accurate, explainable and compliant by design. AI and open banking data can widen access to credit and sharpen risk decisions, but only if the data is justified, the model is tested for bias, and every decision can be explained to the customer and the regulator.
4IRE's AI developers and fintech engineers build scoring models, data pipelines and decision engines for lenders and neobanks. If you are launching a lending product, our guide on how to launch a neobank shows where credit scoring fits in the wider roadmap.
Learn more from us
 AI06 Oct 2026
Lovable AI App Builder in 2026: The Vibe Coding Risks Behind 1 Million Projects a Week
Lovable reports 1M new projects a week and $500M ARR. A CTO's view on what that means for startups, and the security risks of vibe coding to plan for.
Oleksandr Vlasenko
 Bank23 Apr 2026
How to Build a Mobile Wallet App in 2026: A Step-by-Step Guide
How to build a mobile wallet app: choose the wallet model and licence, plan core features, design the architecture, then secure, test and launch.
Olena Petrashchuk
 Fintech news28 Sept 2026
Best Open Banking APIs for Digital Banks: Top 7 Providers
Compare 7 open banking API providers for digital banks: coverage, products and licensing, plus where PSD3, UK and US 1033 rules stand in 2026.
Vladislav Malynovskyi
Build Your AI Credit Scoring System
Planning a lending product or a smarter scoring model? Our AI and fintech engineers will help you design explainable, compliant credit decisioning. Book a free consultation.
FAQ
In the US, mortgages sold to Fannie Mae and Freddie Mac have traditionally relied on Classic FICO scores, and both now also accept VantageScore 4.0. Other countries use their own bureau scores, often combined with the lender's internal models.
Alternative credit scoring uses data beyond the credit bureau file, such as bank transaction data shared through open banking, rent and utility payments, to assess people with thin or no credit history. In the EU, data from social networks may not be used for consumer creditworthiness assessments from 20 November 2026.
Yes. The EU AI Act classifies AI systems used to assess the creditworthiness of individuals as high-risk, with obligations applying from 2 December 2027. GDPR and the Consumer Credit Directive also give consumers rights around automated credit decisions.
It depends on data availability and scope. Integrating a vendor score can take weeks; a custom model with its own data pipeline, validation and decision engine usually takes several months, followed by ongoing monitoring.