


AI in finance has moved from pilot projects to core infrastructure. Banks, payment companies, lenders and insurers now run machine learning in fraud screening, credit decisions, customer support and compliance, and generative AI is spreading from internal copilots to customer-facing products.
This guide from the 4IRE team covers where AI solutions deliver measurable value in the financial sector today, what agentic AI actually looks like in payments, how regulators in the EU, UK and US are responding, and what it takes to put an AI feature into production without creating new risks.
Where AI adoption in finance stands
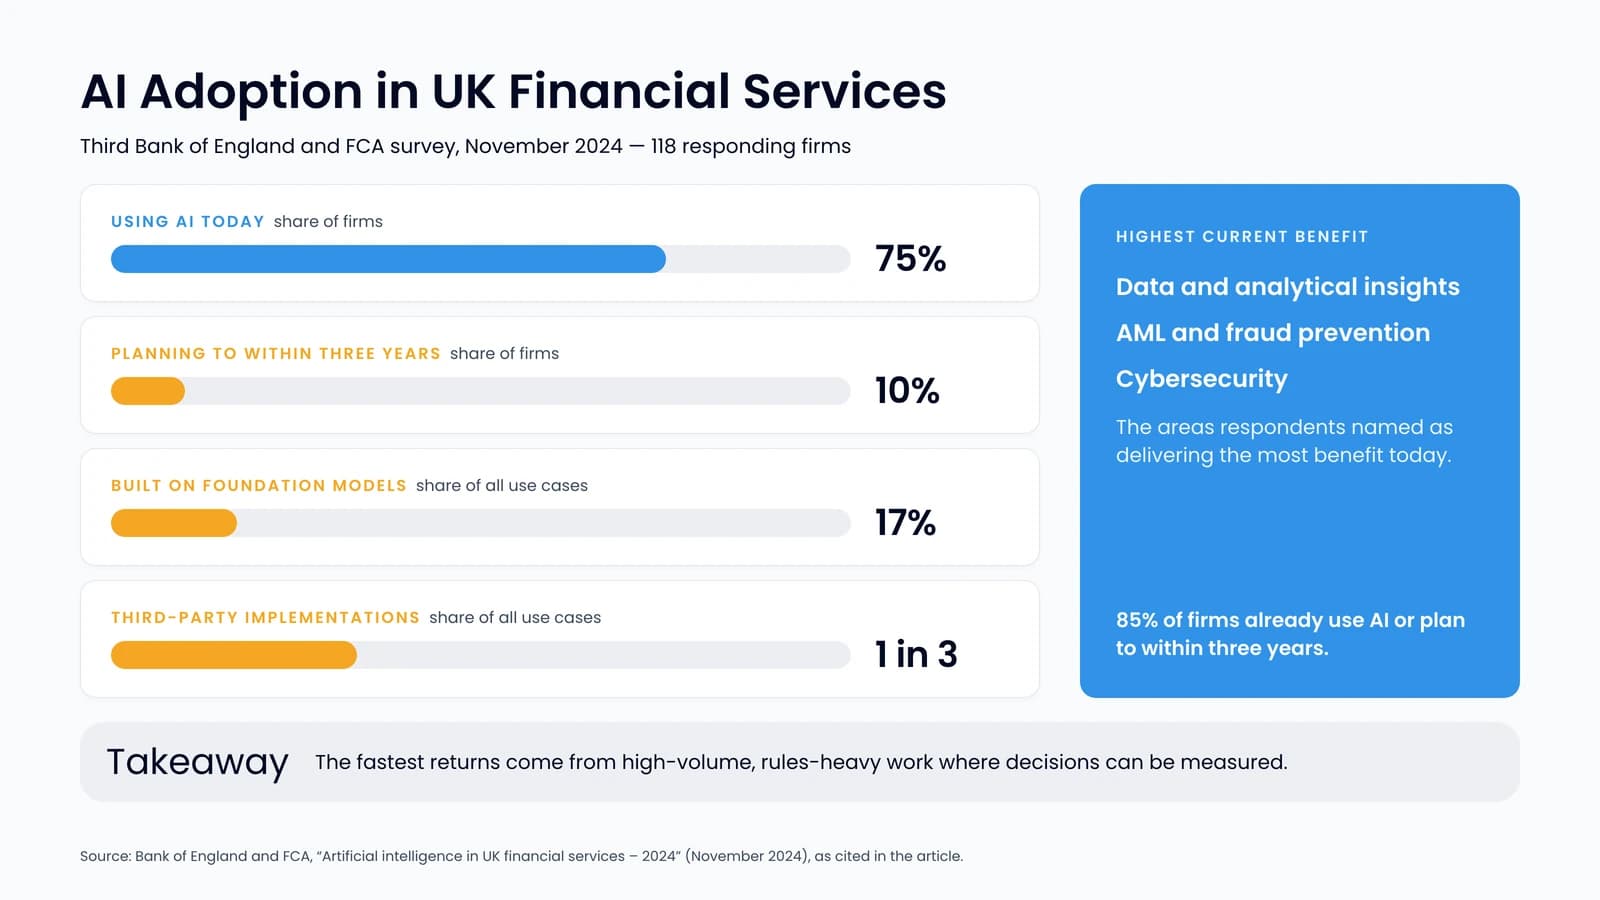
The most reliable adoption data comes from supervisors rather than vendors. In the third Bank of England and FCA survey (November 2024), 75% of the 118 UK financial firms that responded were already using AI, and another 10% planned to do so within three years. Foundation models accounted for 17% of all reported use cases, and a third of use cases were third-party implementations.
Large banks are scaling internal generative AI as well. JPMorganChase says its proprietary LLM Suite, released in summer 2024, onboarded around 200,000 employees within eight months, and the bank plans to connect it to internal data and workflows so that AI agents can complete multi-step tasks.
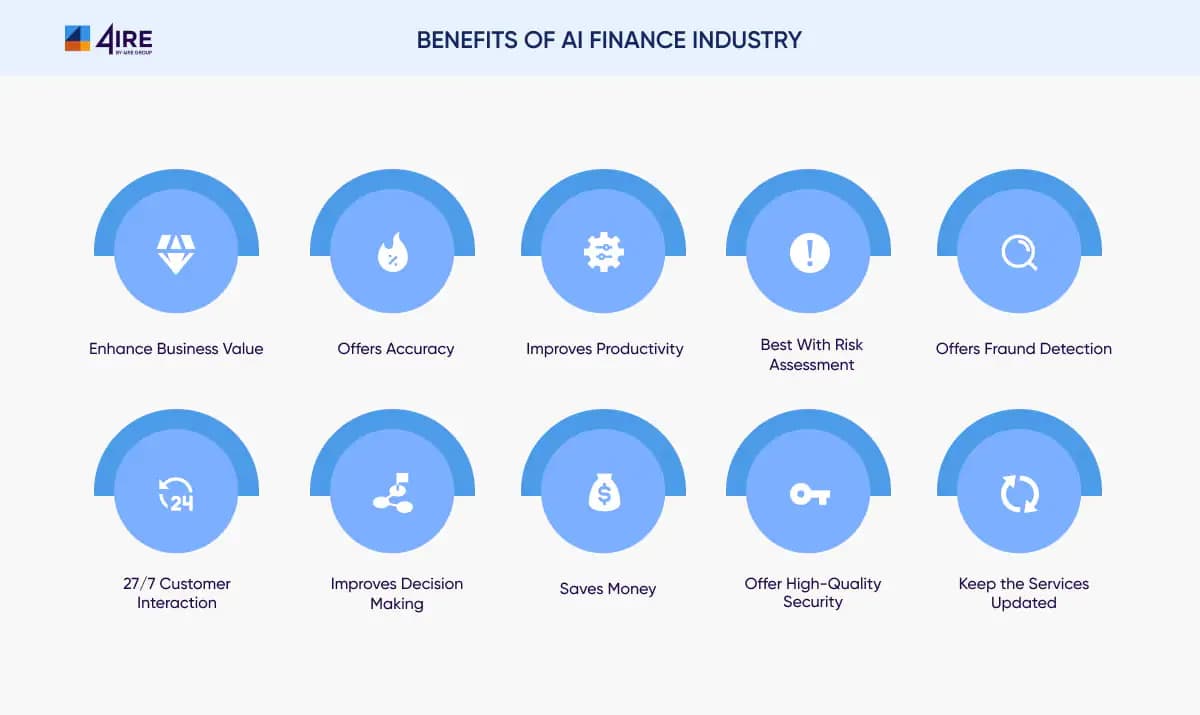
Respondents to the UK survey named data and analytical insights, anti-money laundering and fraud prevention, and cybersecurity as the areas with the highest current benefit. That matches what we see in client projects: the fastest returns come from high-volume, rules-heavy work where decisions can be measured.
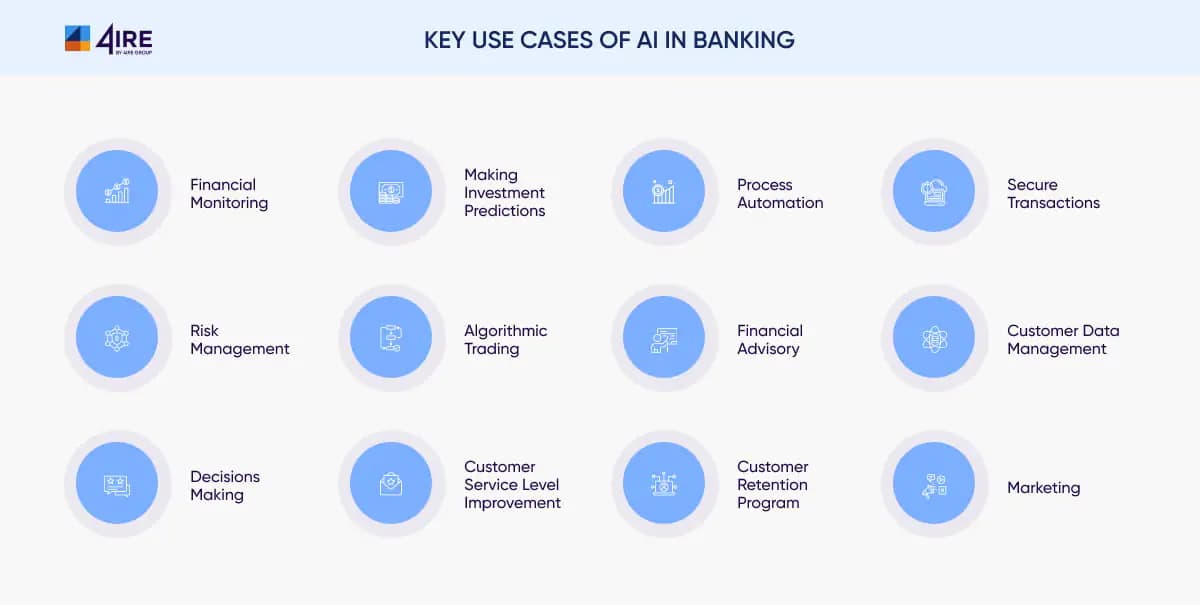
Core use cases of AI in finance
Fraud detection, AML and transaction monitoring
Rule-based monitoring produces large volumes of false positives. Machine learning models score each transaction against behavioural patterns such as device, location, amount and counterparty history, and graph analytics can surface networks of mule accounts that single-transaction rules miss. The practical gain is fewer alerts of higher quality, so analysts spend time on cases that matter.
Credit scoring and underwriting
AI models can use cash-flow data, transaction history and other alternative signals to assess applicants with thin credit files. We break down the methods in our guide to building a credit scoring system, and the Mexican neobank Plata is a good example of the approach in practice, as shown in our analysis of building a neobank like Plata. Credit scoring is also the use case regulators watch most closely, as the regulation section below explains.
Customer service and GenAI assistants
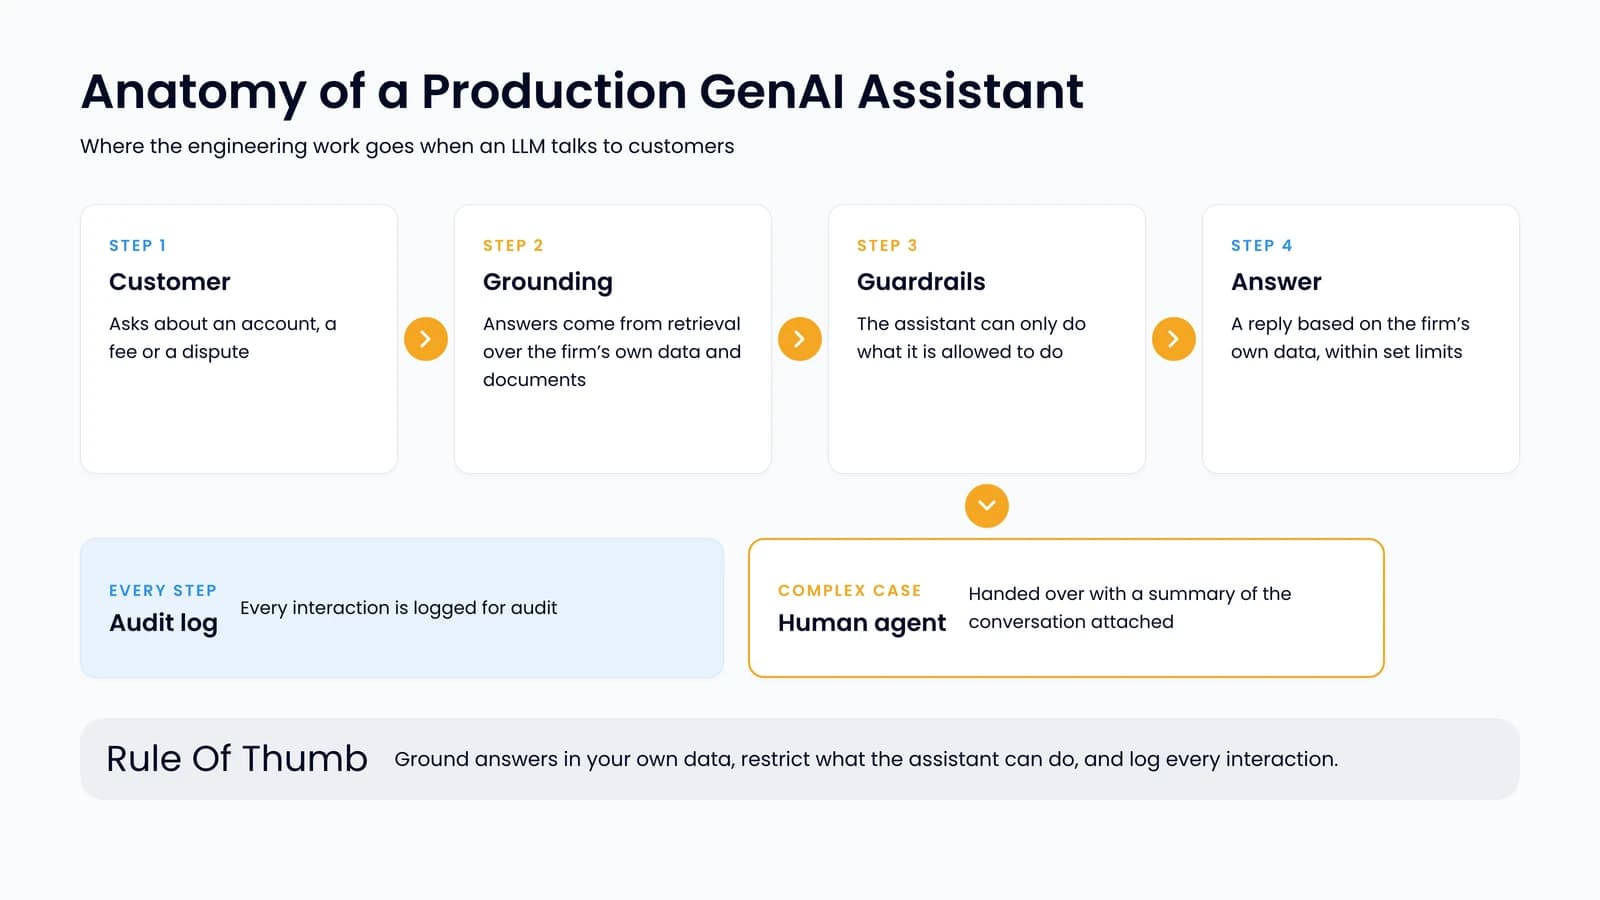
LLM-based assistants now answer account questions, explain fees, help with disputes and hand complex cases to human agents with a summary attached. The engineering work is in grounding answers in the firm’s own data, restricting what the assistant can do, and logging every interaction for audit. Our ChatGPT integration services cover this pattern, from retrieval over internal documents to guardrails and human escalation.
Compliance and RegTech
AI helps compliance teams screen customers and payments against sanctions lists, monitor communications, map new regulations to internal controls and prepare regulatory reports. Models do the first pass; compliance officers keep the final decision and the accountability.
Trading, portfolio and risk analytics
Machine learning supports market-risk forecasting, liquidity management, portfolio rebalancing and trade execution. Firms also use natural language processing to turn news, filings and earnings calls into structured signals. Here, model risk management matters more than raw accuracy: a strategy that works in back-tests can fail in a regime change.
Document processing and back-office automation
Loan files, KYC documents, invoices, claims and contracts are still largely unstructured. AI extraction and classification cut manual data entry and speed up onboarding and underwriting. The same techniques apply to collecting external data, which we compare in AI-enhanced vs conventional web scraping.
Agentic AI in finance: what is real today
Agentic AI refers to systems that plan and carry out multi-step tasks rather than only answering questions. In finance, the most concrete progress is in payments:
- Visa Intelligent Commerce. Launched in April 2025 to connect AI agents to Visa’s network. In December 2025, Visa reported that hundreds of agent-initiated transactions had been completed with partners and that pilots in Asia Pacific and Europe were planned for early 2026.
- Mastercard Agent Pay. Announced on 29 April 2025. It uses Agentic Tokens, which build on Mastercard’s existing tokenization so that a payment credential can be tied to an AI agent.
- Bank operations. Banks such as JPMorganChase are extending internal generative AI platforms towards agents that complete multi-step workflows, with humans approving the outcome.
In crypto markets, agents already interact with wallets and smart contracts directly, which we cover in AI agents in crypto. For regulated finance, the open questions are liability, authentication of the agent, and how to prove that the customer actually authorised what the agent did.
Regulation of AI in finance
Regulators are not banning AI in finance, but they expect it to be governed like any other material risk.
- EU AI Act. In force since 1 August 2024. Prohibited practices apply from 2 February 2025, and obligations for general-purpose AI models from 2 August 2025. AI used to assess the creditworthiness or credit score of natural persons, and to assess risk and pricing in life and health insurance, is classified as high-risk (Annex III). AI used only to detect financial fraud is excluded. The Digital Omnibus amendment, adopted in June 2026, moved the start of these Annex III obligations from 2 August 2026 to 2 December 2027.
- EBA. Its November 2025 factsheet on the AI Act found no significant contradictions between the AI Act and EU banking and payments law, and described the Act as complementary to existing rules on lending and internal governance.
- FSB and BIS. The Financial Stability Board points to third-party dependencies and provider concentration, market correlation, cyber risk and model risk as the main AI-related vulnerabilities, and in October 2025 set out how authorities should monitor them. The BIS has urged central banks to build their own AI expertise.
- US SEC. In June 2025, the SEC withdrew its 2023 proposal on conflicts of interest in broker-dealers’ and advisers’ use of predictive data analytics. Existing fiduciary, anti-fraud and disclosure rules still apply to AI-driven services.
Implementation challenges
- Data quality and access. Models are only as good as the transaction, customer and document data behind them, and that data is usually spread across legacy systems.
- Explainability. A lender must be able to tell a customer and a supervisor why an application was declined. Complex models need explanation tooling and documentation from day one.
- Model risk. Models drift as customer behaviour and markets change. Validation, monitoring and a rollback plan belong in the design, not after launch.
- Vendor lock-in and concentration. Relying on one model provider or cloud creates operational and pricing risk. An abstraction layer that lets you switch models reduces it.
- Security and privacy. LLM features add new attack surfaces such as prompt injection and data leakage, alongside GDPR and banking secrecy obligations.
How to start with AI in a financial product
- Pick one measurable problem, such as false-positive fraud alerts or manual onboarding time, and define the metric before building.
- Audit the data you already have and fix access and quality issues first.
- Classify the use case against the EU AI Act and your local rules to know whether high-risk requirements will apply.
- Build a narrow pilot with human review, logging and explainability, then measure it against the current process.
- Plan production: monitoring, model validation, fallback paths and integration with core systems.
A fast AI prototype is not a production system; our look at Lovable dev trends in 2026 explains where that gap usually appears. For regulated products, the 4IRE team combines financial software development with AI-driven development to take a use case from pilot to a monitored, auditable service.
Build AI-powered fintech with 4IRE and Datrics
4IRE partners with Datrics, an AI platform from our sister company, for data science and ML automation. The video below shows how the platform works.
Learn more from us
 AI06 Oct 2026
Lovable AI App Builder in 2026: The Vibe Coding Risks Behind 1 Million Projects a Week
Lovable reports 1M new projects a week and $500M ARR. A CTO's view on what that means for startups, and the security risks of vibe coding to plan for.
Oleksandr Vlasenko
 Data science29 Sept 2026
Top 5 DeFi Lending Platforms in 2026
Aave, Morpho, SparkLend, Compound and Venus: the top DeFi lending platforms by TVL in 2026, how crypto lending works, and its risks.
Olena Petrashchuk
 AI29 Sept 2026
AI Agents in Crypto: 7 Use Cases for Exchanges, DAOs and DeFi
Where AI agents actually run in crypto today: exchanges, DAOs, launchpads and DEXs, what guardrails they need, and how to scope a pilot.
Vladislav Malynovskyi
Unlock Financial Freedom with DeFi Innovators
Ready to redefine finance? Empower your business with decentralized finance solutions crafted by our seasoned team. Schedule a free consultation with our seasoned expert today!
FAQ
The most common uses are fraud detection and AML transaction monitoring, credit scoring and underwriting, customer service assistants, compliance screening, risk and trading analytics, and document processing. In the 2024 Bank of England and FCA survey, 75% of responding UK financial firms were already using AI.
Yes. Under the EU AI Act, AI systems that assess the creditworthiness or credit score of natural persons are high-risk. Following the 2026 Digital Omnibus amendment, these high-risk obligations apply from 2 December 2027. Existing banking and consumer credit rules already apply today.
Agentic AI systems plan and execute multi-step tasks, such as completing a purchase or preparing a case file, instead of only answering questions. Visa and Mastercard launched agentic payment programmes in 2025 that let AI agents initiate transactions with tokenized credentials.
Poor data quality, limited explainability, model drift, dependence on a few technology providers, and new security threats such as prompt injection. Supervisors including the FSB and EBA expect firms to manage these through existing governance and model risk frameworks.