

 Payment Gateway

Builders who need regulated stablecoin infrastructure usually end up comparing Circle and Paxos. Both run reliable, regulated stablecoin rails (Circle's USDC, Paxos's USDP, PayPal's PYUSD and the consortium-backed USDG), but they solve different problems: Circle's strength is a deep, self-serve developer platform; Paxos's is a regulatory wrapper that lets other companies issue their own branded stablecoin under Paxos's charter.
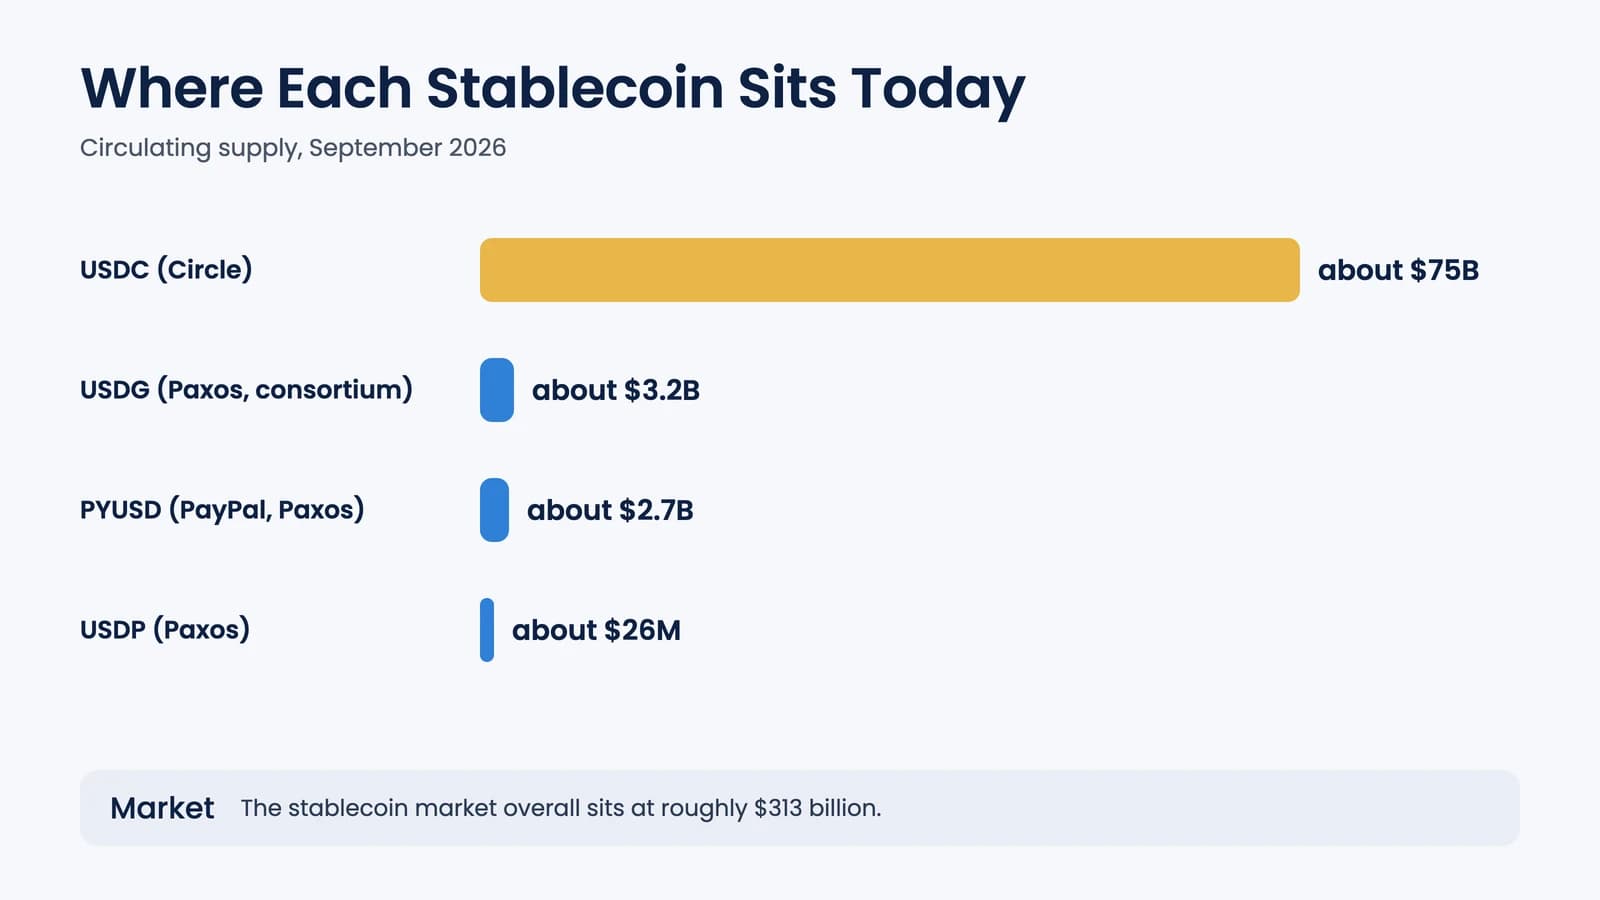
The stablecoin market overall sits at roughly $313 billion as of September 2026, with USDC alone accounting for about $75 billion of it. Picking the wrong infrastructure layer here is expensive to unwind, so this comparison works through API architecture, licensing, reserves, chain coverage, and white-label issuance: the dimensions that actually change a build.
What Circle and Paxos actually are
Circle is a payments technology company built around USDC and a layered developer platform, Circle Web3 Services: an Accounts API, a Payments API, Programmable Wallets, and Circle Mint for institutional minting and redemption via the Cross-Chain Transfer Protocol (CCTP). Paxos is a regulated trust company: it has held a New York Department of Financial Services (NYDFS) trust charter since 2015, and in December 2025 the OCC approved Paxos Trust Company's conversion to a nationally chartered trust company, adding federal oversight on top of its NYDFS charter. Paxos issues USDP directly, operates the infrastructure behind PayPal's PYUSD, and issues the consortium-backed Global Dollar (USDG) through regulated entities in Singapore and the EU.
The circulating numbers tell you where each product actually sits today, as of September 2026: USDC is roughly $75 billion, PYUSD is around $2.7 billion, USDG is around $3.2 billion, and Paxos's own USDP has shrunk to roughly $26 million, a fraction of its size before BUSD wound down. Paxos's business case today rests on PYUSD, USDG, and its white-label issuance platform, not on USDP itself.
API architecture and developer experience
Circle ships a conventional developer platform: REST APIs, a full sandbox that mirrors production, official and community SDKs, and a product philosophy built around a fast time-to-first-transaction. Paxos's stack is enterprise-first: minting and redemption workflows, institutional settlement, and guided onboarding rather than self-serve docs. A useful shorthand: Circle is built for a consumer-product build cycle, Paxos for an institutional one. If you're unsure which model your project needs, blockchain consulting services can settle it before you've written code against the wrong one.
| Circle | Paxos | |
|---|---|---|
| API style | REST, full sandbox, official SDKs | REST, enterprise onboarding, limited public SDKs |
| Wallet infrastructure | Programmable Wallets (custodial + MPC) built in | No native wallet product |
| Multi-chain reach | USDC natively live on a wide and still-growing set of chains via CCTP mint-and-burn | USDP is Ethereum-only; PYUSD spans Ethereum and Solana; USDG adds Paxos's EU/Singapore rails |
| Typical use case | Consumer payments, wallets, B2B transfers, DeFi integrations | White-label issuance, institutional settlement, regulated treasury |
Regulatory licensing and compliance posture
Circle holds money transmission licenses across most US states, a NYDFS BitLicense, and an e-money institution authorization in the EU under MiCA, enough for most consumer-facing payment and stablecoin products, though institutional integrations (banks, broker-dealers, custodians) tend to need extra legal review on top of an MSB license.
Paxos's NYDFS trust charter requires client assets to sit in full reserve in segregated accounts, examined under NYDFS supervision, and its OCC-approved move to a national trust charter, announced in December 2025, adds federal-level standing on top of that. For products where a procurement or compliance team specifically wants a regulated trust structure rather than an MSB license, that combination is the reason to default to Paxos.
Reserve structure and transparency
| USDC (Circle) | USDP / USDG (Paxos) | |
|---|---|---|
| Reserve assets | Cash, short-term US Treasuries, overnight Treasury repo, via the BlackRock-managed Circle Reserve Fund custodied at BNY Mellon | Cash and cash equivalents in segregated, bankruptcy-remote accounts |
| Attestation | Monthly, by Deloitte & Touche, under AICPA attestation standards, plus a weekly public reserve breakdown | Monthly attestation; KPMG has been engaged for Paxos reserve reporting |
| Oversight | NYDFS (BitLicense), FinCEN (MSB), SEC (registered reserve fund), EU (MiCA) | NYDFS (trust charter), OCC (national trust charter approved Dec 2025) |
An attestation is not the same thing as a full financial audit: it confirms reserves matched circulating supply at a point in time, not the issuer's complete financial health. Both Circle and Paxos publish attestations, not full audits, which is worth flagging to any enterprise risk team evaluating either provider. For a deeper look at what a compliant reserve and custody stack needs, see our stablecoin infrastructure guide.
Use-case fit
| Use case | Circle | Paxos | Notes |
|---|---|---|---|
| Consumer payments app | Strong | Weak | Circle ships Payments API + Programmable Wallets; Paxos has no wallet product |
| B2B / institutional settlement | Strong | Strong | Circle via CCTP; Paxos via its Settlement Network for regulated counterparties |
| White-label stablecoin issuance | Weak | Strong | Only Paxos lets another company issue its own branded token under its charter |
| Regulated financial product | Moderate | Strong | Paxos's trust charter satisfies requirements an MSB license may not |
| On-chain treasury / DeFi-adjacent rails | Strong | Moderate | CCTP's chain coverage and liquidity depth is the wider net today |
White-label issuance: where Paxos leads outright
Circle Mint handles USDC minting and redemption but does not let a client issue its own standalone token; you build on top of USDC. Paxos is the opposite: it lets institutions issue a branded stablecoin under its NYDFS/OCC trust charter, so the client never needs a charter of its own. PayPal's PYUSD is the clearest production example; USDG, issued through Paxos's regulated entities in Singapore and the EU, is the multi-institution version of the same model. Combined, PYUSD, USDG and USDP add up to roughly $5.9 billion in circulating supply as of September 2026, a real but still much smaller footprint than USDC's.
Enterprises issuing a regulated stablecoin this way tend to reuse the same compliance stack behind RWA tokenization projects; our guide to real-world asset tokenization walks through where the two overlap. Banks weighing whether to issue a token at all versus adopt a tokenised deposit instead should read that comparison before picking a stablecoin partner.
Decision framework
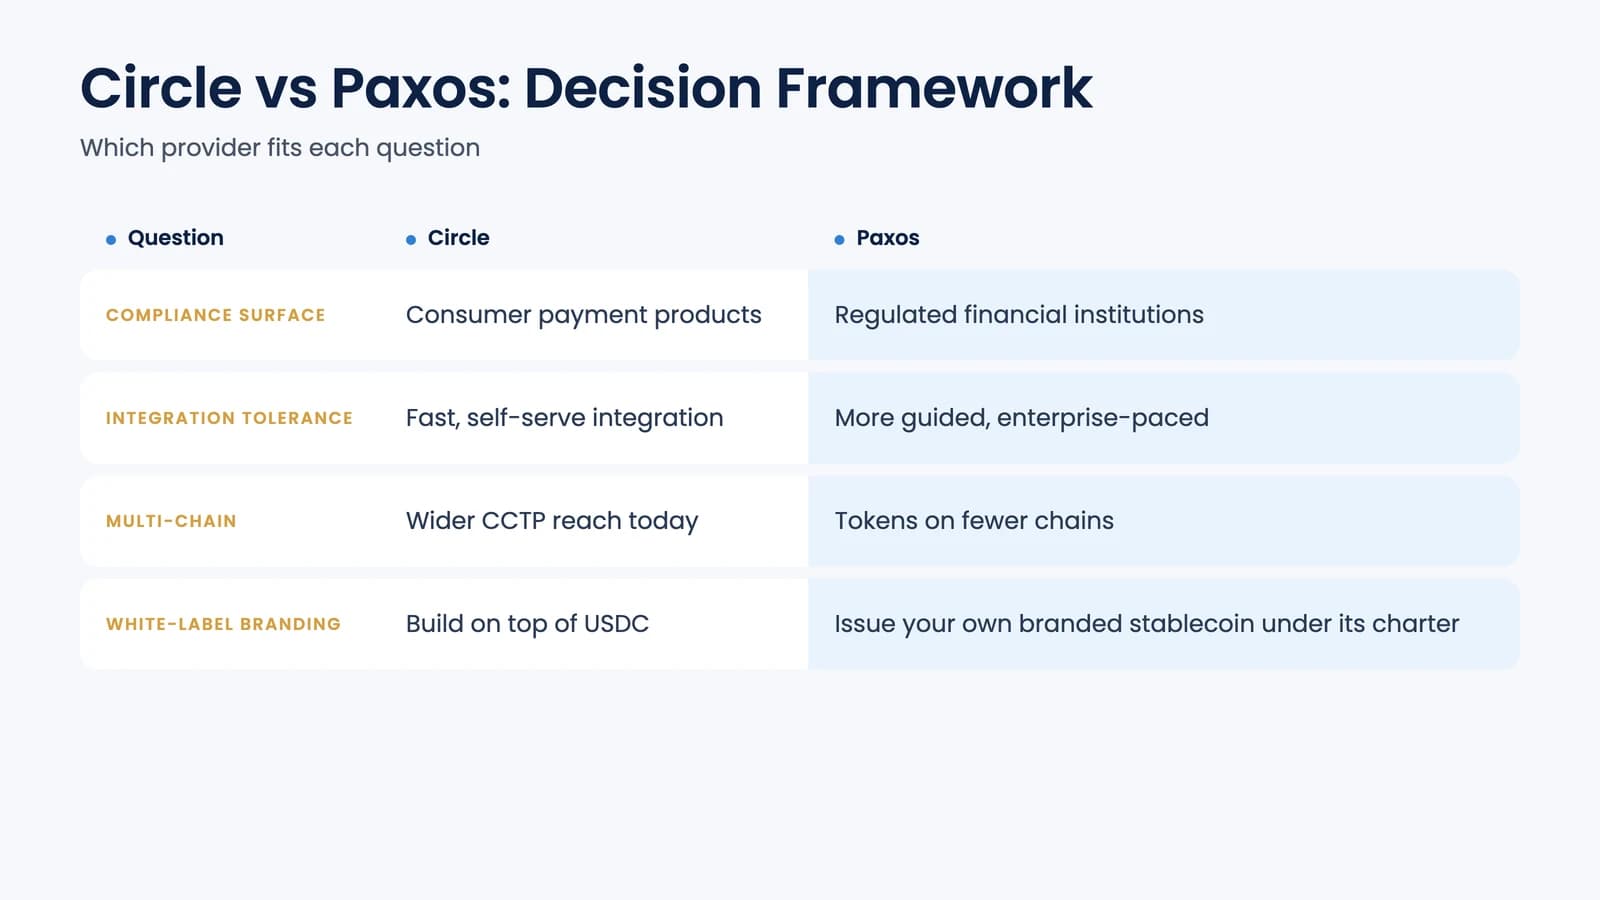
- Compliance surface area. Paxos for regulated financial institutions; Circle for consumer payment products.
- Team size and integration tolerance. Circle's toolkit is built for fast, self-serve integration; Paxos's is more guided and enterprise-paced.
- Multi-chain requirements. Circle's CCTP reach is wider today; Paxos's tokens are concentrated on fewer chains.
- White-label branding. Only Paxos supports issuing your own branded stablecoin under its charter.
- Pre-built application layer. Teams that want to skip raw API integration and ship a stablecoin payment product directly can use 4IRE's neobank engine as the application layer over either provider.
Teams consistently underestimate the compliance surface area a stablecoin integration carries. 4IRE's blockchain consulting team scopes this before it becomes a costly mid-build correction.
Integration risks to plan for
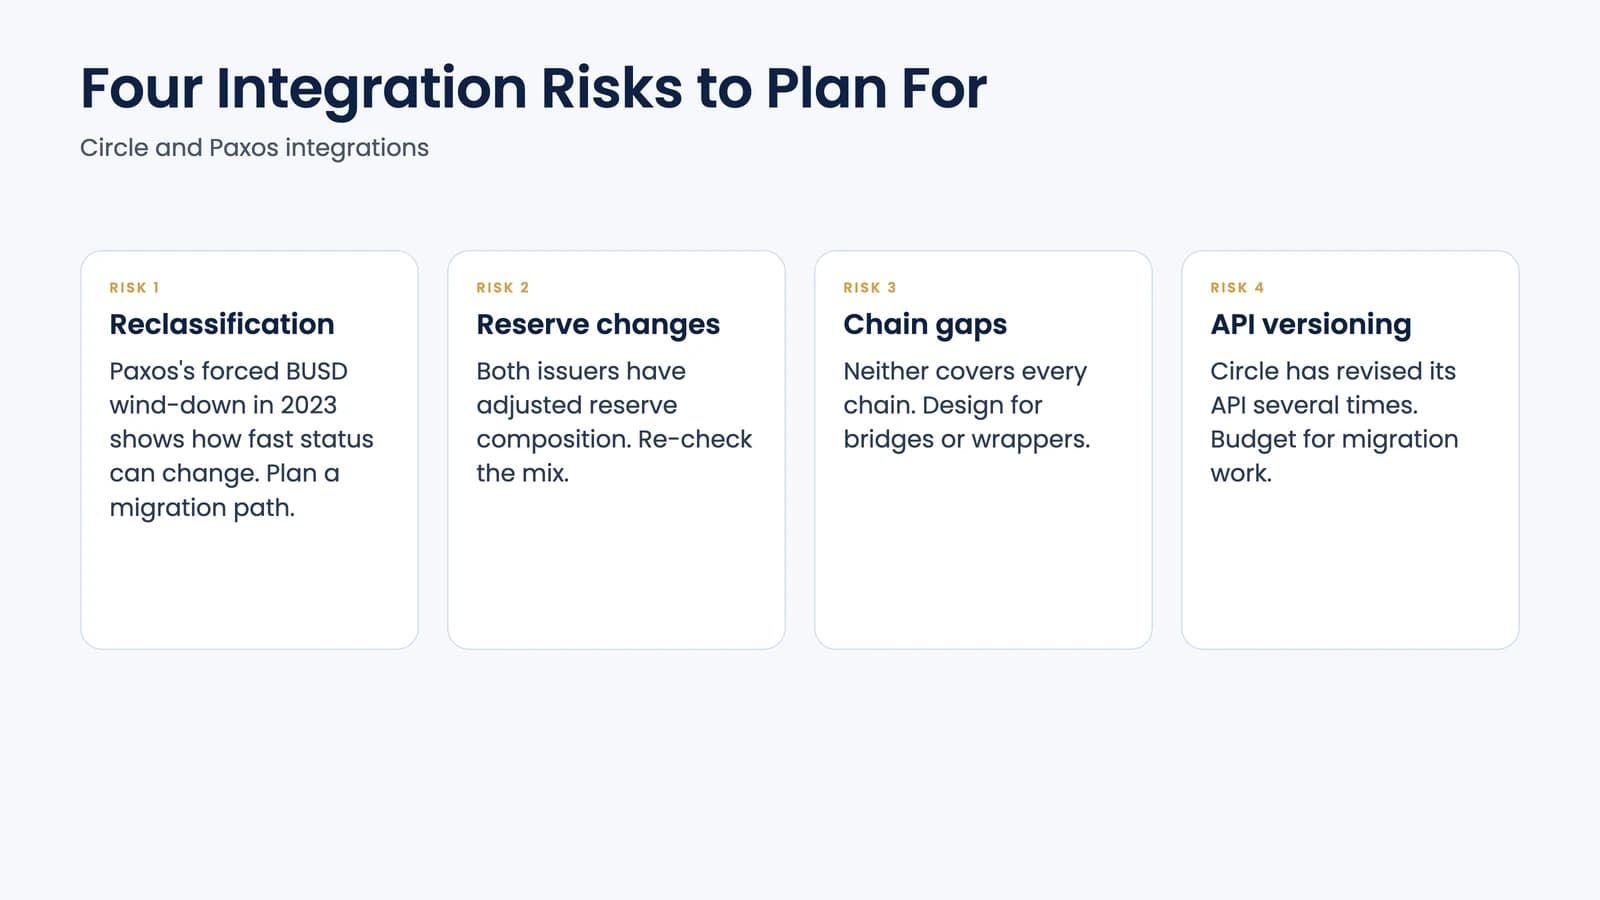
- Regulatory reclassification. Paxos's own forced wind-down of BUSD in 2023, after an NYDFS order, shows how quickly a stablecoin's status can change; plan a migration path for any single-issuer dependency.
- Reserve composition changes. Both issuers have adjusted reserve composition over time; re-check the current mix before treating a stablecoin as cash-equivalent on your own balance sheet.
- Chain coverage gaps. Neither provider covers every chain your users may want; design for bridges or wrappers on unsupported chains rather than assuming native support will arrive on your timeline.
- API versioning. Circle has revised its API surface multiple times as its platform has grown; budget for migration work over a multi-year integration.
Conclusion
Circle is the stronger default for developer-first teams building consumer-facing products; Paxos is the stronger default when the product itself needs to sit inside a regulated trust structure or ship under its own brand. Both platforms keep changing, so treat this as a starting framework, not a final answer. 4IRE's blockchain consulting team can help weigh the current state of either platform against your specific compliance and timeline constraints.
FAQ on Circle vs. Paxos Comparison
Circle is a developer-first platform built around USDC, with deep self-serve APIs, wallets, and wide multi-chain reach. Paxos is a regulated trust company that lets other institutions issue their own branded stablecoin under its NYDFS/OCC charter, and operates the infrastructure behind PYUSD and USDG.
Circle issues USDC. Paxos issues USDP directly, operates the infrastructure behind PayPal's PYUSD, and issues the consortium-backed Global Dollar (USDG) through its regulated entities in Singapore and the EU.
The OCC approved Paxos Trust Company's conversion to a national trust charter in December 2025, adding federal-level oversight on top of the NYDFS trust charter Paxos has held since 2015. For products where a procurement or compliance team specifically requires a chartered trust structure rather than a money-transmitter license, that combination is often the deciding factor.
Yes, that is Paxos's core white-label offering. Because the token issues under Paxos's own trust charter, you don't need to obtain a charter yourself. Circle does not offer an equivalent standalone-issuance product; Circle Mint is built around minting and redeeming USDC, not issuing a separate token.
USDP has shrunk to a small fraction of its former size: roughly $26 million in circulation today, well below PYUSD and USDG. Builders evaluating Paxos should treat PYUSD, USDG, and the white-label issuance platform as the relevant products today, not USDP.