

 GreenFi
Carbon pricing has grown from a handful of pilot schemes in the 1990s (the US Clean Air Act's cap-and-trade provisions, the Kyoto Protocol's International Emissions Trading and Clean Development Mechanism) into a global patchwork of emissions trading systems, carbon taxes and voluntary markets. This piece looks at how big that market actually is in 2026, what's driving it, and which platforms and trends to watch, using only figures the 4IRE team could verify directly rather than repeating whichever forecast ranks best on Google.
Market size: what's actually verifiable
Carbon market sizing is a genuinely confusing area to research, because "market size" gets used for at least three different things: the notional trading value of allowances changing hands (turnover), the face value of credits issued, and forward-looking forecasts from market-research firms that rarely agree with each other by more than a factor of two. Rather than quote one of those forecasts as fact, here's what's directly checkable:
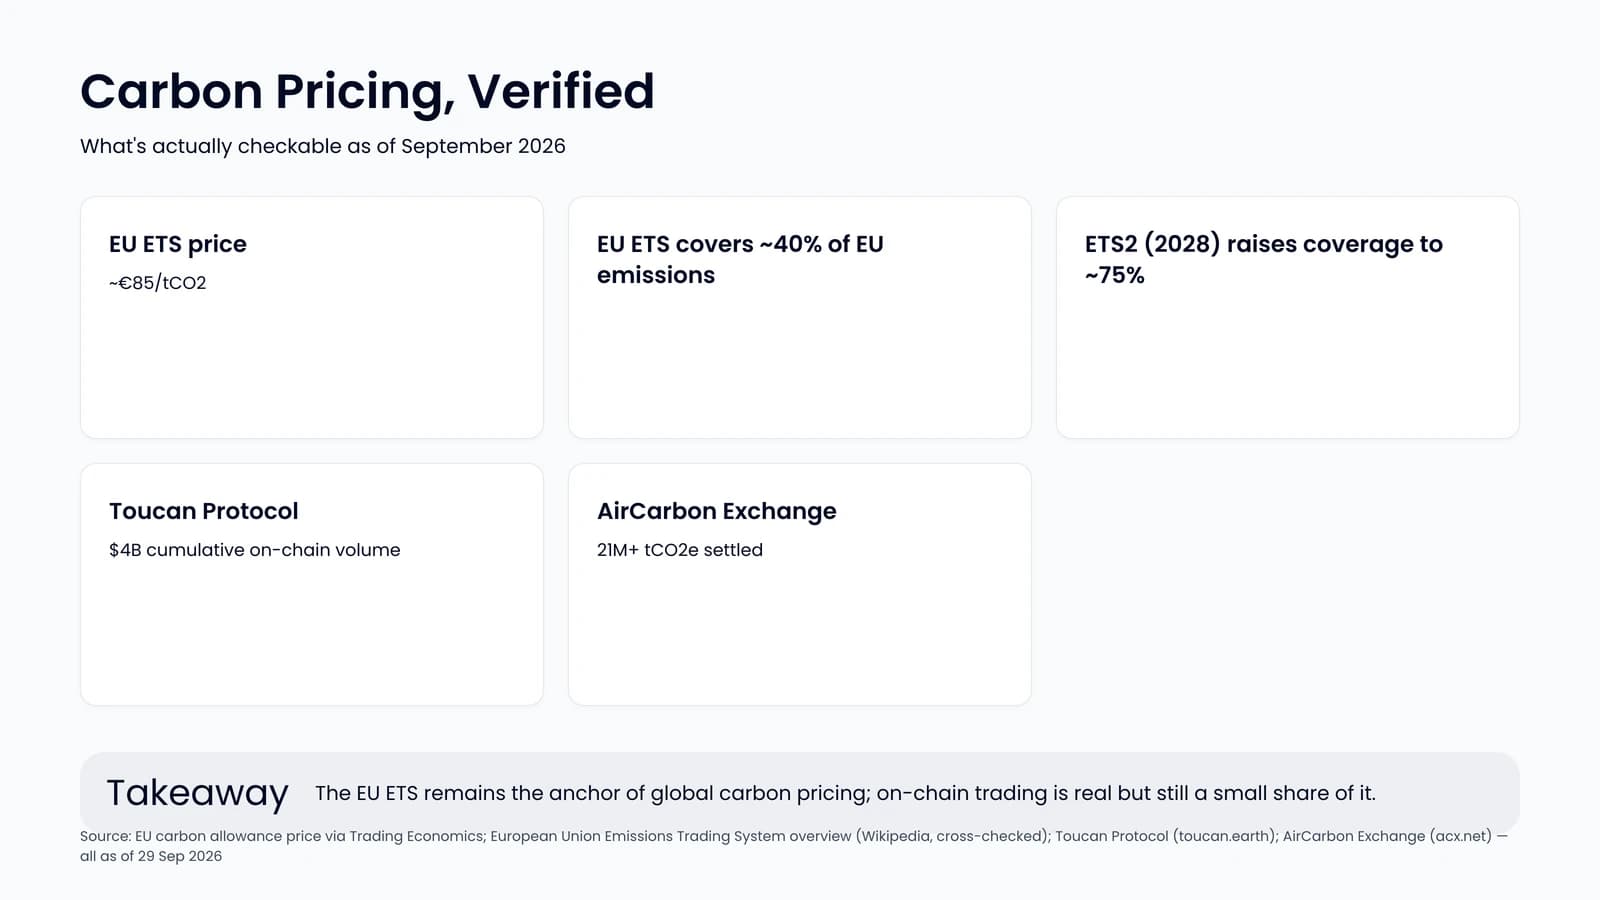
- EU ETS price. The EU Emissions Trading System, by far the largest carbon market by both volume and value, priced allowances at roughly €85 per tonne of CO2 as of 29 September 2026.
- EU ETS coverage. The system currently covers around 40% of EU greenhouse gas emissions. ETS2, extending the cap to buildings, road transport and additional fuels, is currently scheduled to start in 2028 (delayed from an original 2027 target); once live, combined coverage is expected to reach roughly 75% of EU emissions.
- On-chain carbon trading volume. Toucan Protocol, the largest blockchain-native carbon infrastructure provider, has processed a cumulative $4 billion in carbon credit trading volume since its 2021 launch, a useful proxy for how much of the voluntary market has actually moved on-chain, which remains a small fraction of the total voluntary market.
Beyond these, treat any single-figure "market will reach $X trillion by 2030/2032/2050" claim with real skepticism. These forecasts routinely disagree with each other by 3-5x depending on which segments (compliance only, or compliance plus voluntary plus adjacent carbon-capture and REC markets) they bundle together.
What's driving growth
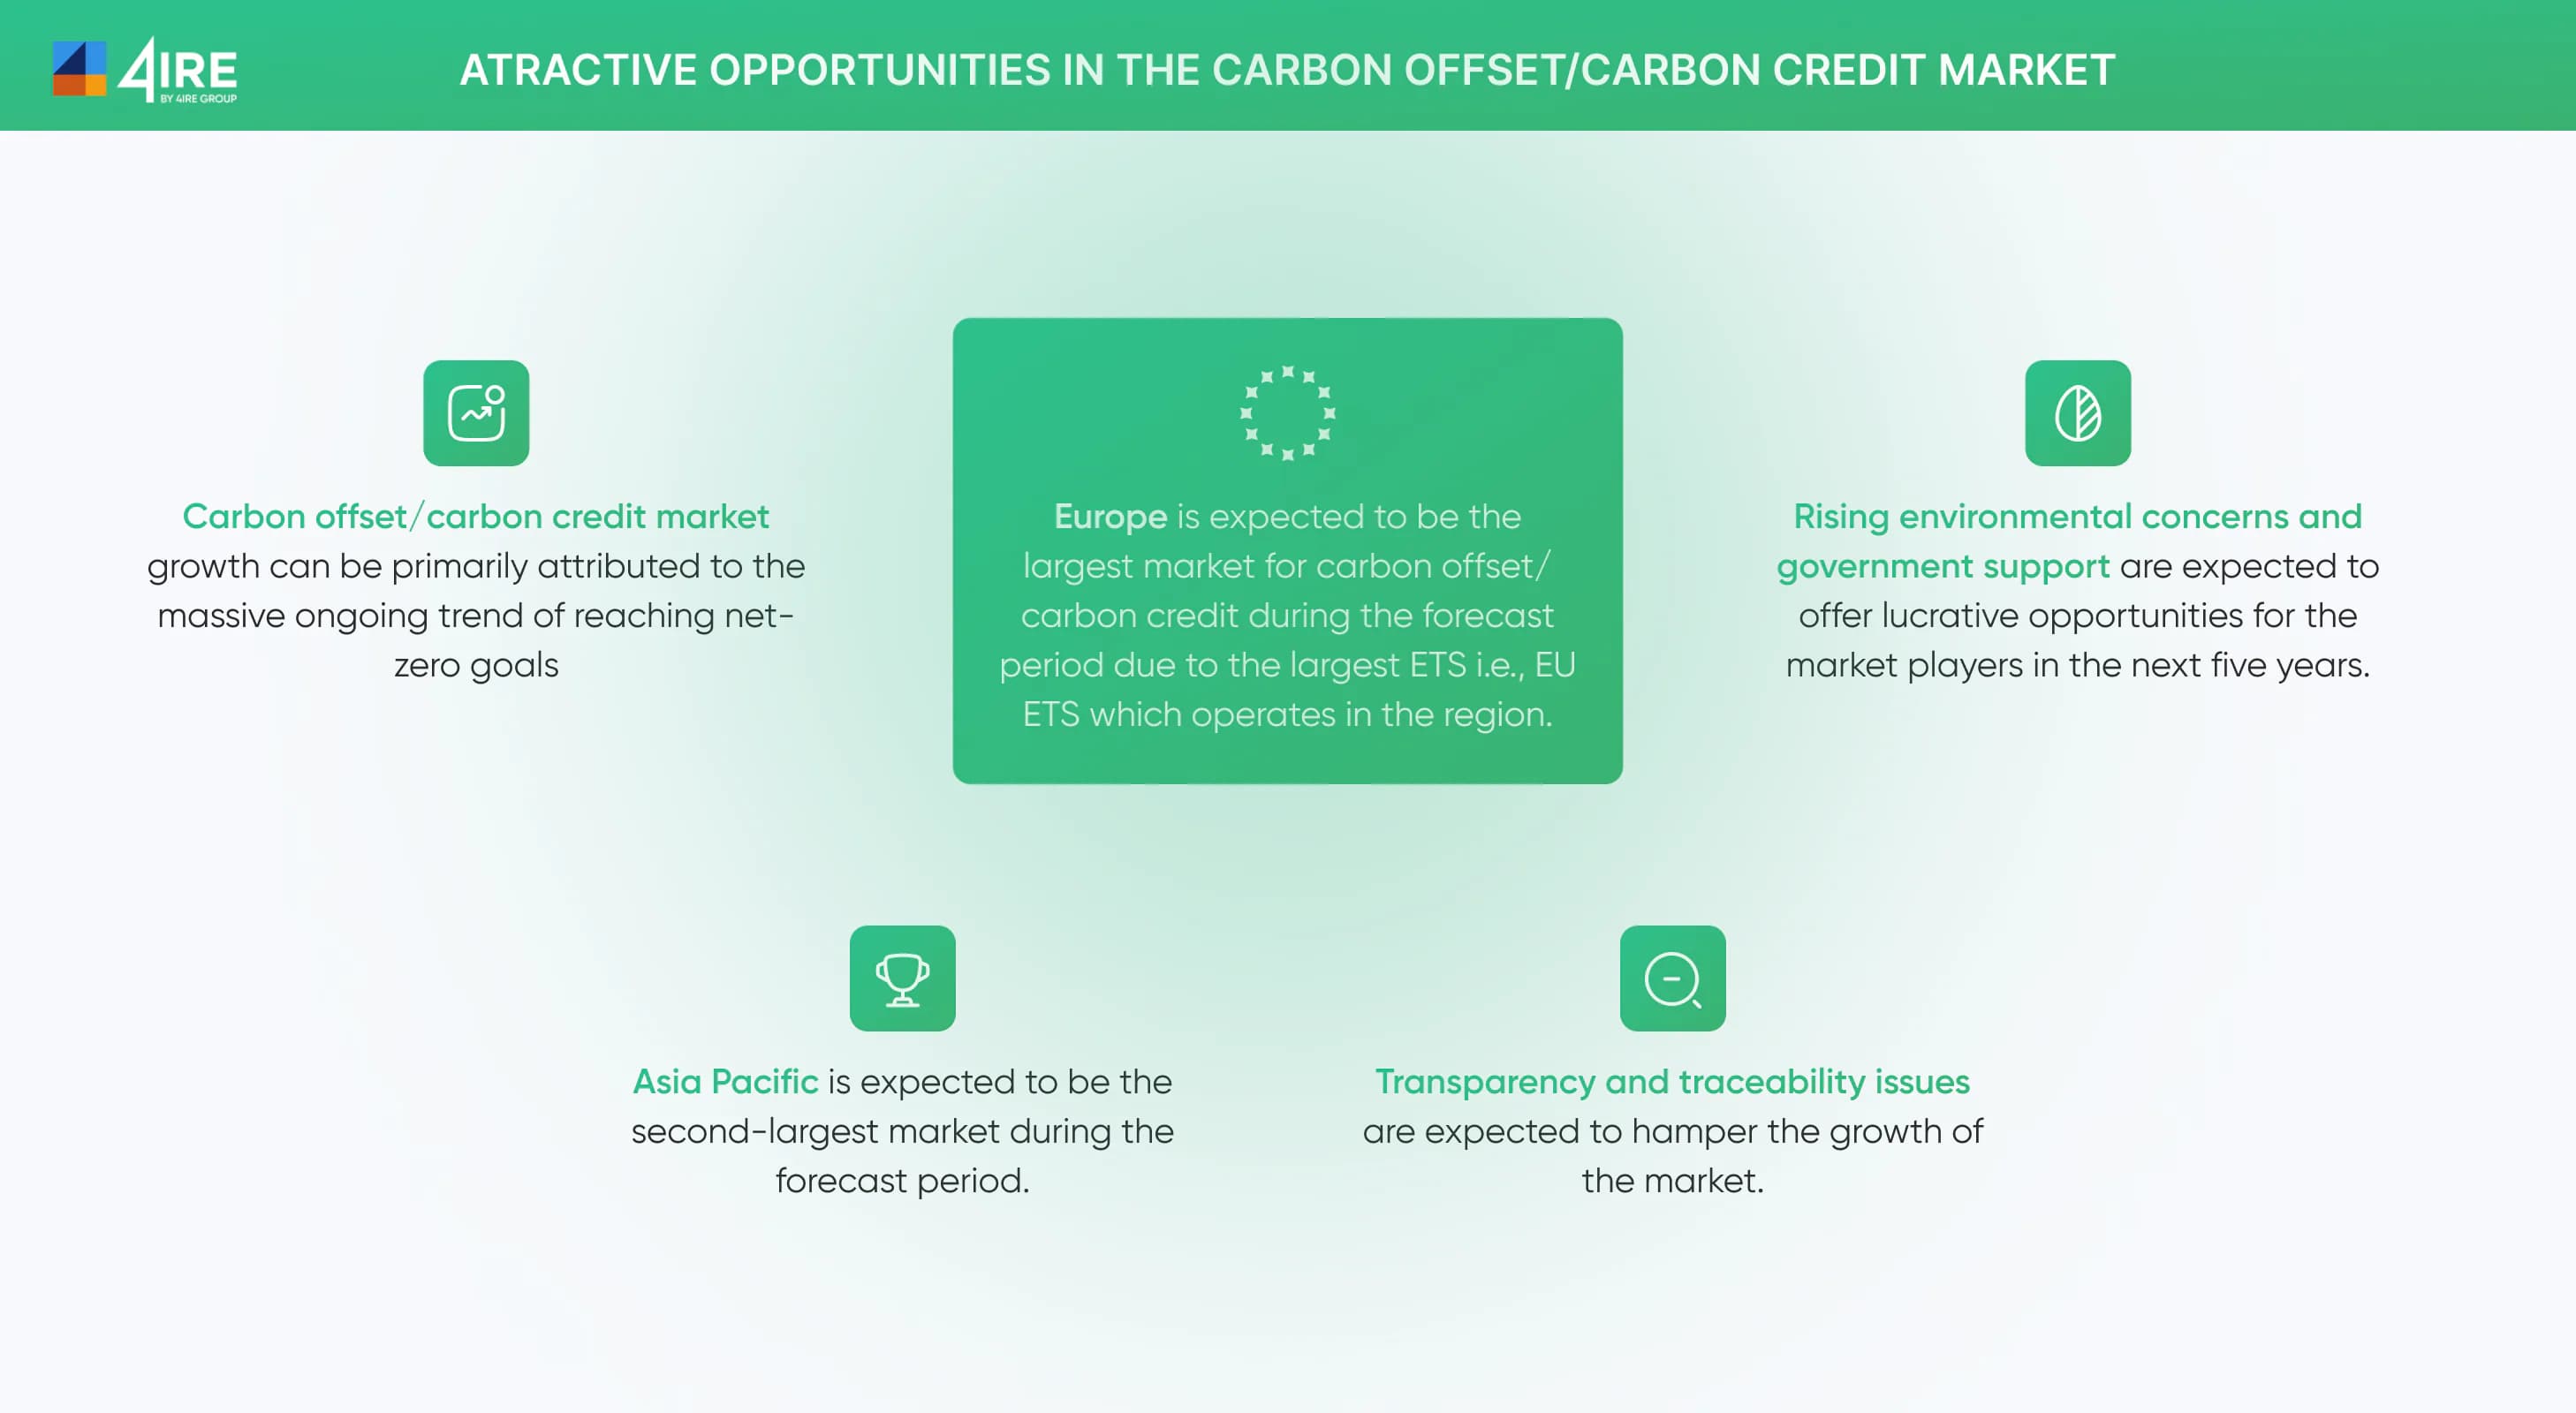
- Tightening regulation. More jurisdictions are adding or expanding carbon pricing schemes each year, and existing schemes like the EU ETS are extending their coverage (ETS2) rather than shrinking it.
- Corporate net-zero commitments. A large and growing share of major corporations have published net-zero or carbon-neutral targets, which structurally requires either buying credits or funding removal projects for whatever emissions can't be eliminated directly.
- Nature-based and removal projects. Investment continues shifting toward reforestation, soil carbon and direct air capture projects, which tend to command a price premium over cheaper avoidance-based credits because buyers increasingly want verified removal, not just avoided emissions.
- Blockchain-based infrastructure. Tokenized credits and on-chain registries reduce the operational friction (settlement time, duplicate counting, opaque pricing) that has historically made carbon trading slow and expensive. See our carbon credit market overview for how this plays out in practice.
Where the trading infrastructure actually is
A handful of platforms account for most of the verifiable on-chain and licensed-exchange volume: Toucan Protocol (carbon-specific infrastructure, $4B cumulative volume), AirCarbon Exchange (21M+ tCO2e settled, 190+ members across 30+ countries), and Xpansiv (CBL and related exchanges plus registry infrastructure covering roughly 300 GW of renewable capacity). Klima Protocol, the 2026 rebrand of KlimaDAO, has narrowed to zero-fee, registry-agnostic credit retirement rather than running its own reserve-backed token. None of these has fully displaced the underlying registries (Verra, Gold Standard, the American Carbon Registry) that still certify whether a credit's underlying project delivered the reduction it claims.
Trends shaping the market
Growing interest in carbon removal
The market has shifted from purely avoidance-based credits (don't cut down this forest) toward removal-based credits (pull CO2 out of the air and store it), which command higher prices because they're harder to game and more directly address the physical problem.
Carbon credit price fluctuations
Voluntary credit prices vary enormously by project type, vintage and registry: a difference of 10x or more between a cheap avoidance credit and a premium, third-party-verified removal credit is common. Standardized pricing benchmarks are still immature compared to compliance markets like the EU ETS, where price discovery happens on a regulated exchange.
Regional divergence
US demand leans on voluntary corporate offsetting rather than a nationwide cap-and-trade system. The EU runs the opposite model: a hard compliance cap under the ETS, with the voluntary market playing a smaller supporting role. Anyone building or entering a carbon trading platform needs to design for whichever regulatory model their target users actually operate under, not a generic global one.
Registries moving toward blockchain
Verra tightened its rules on bridging VCS credits onto public blockchains after the 2021-2022 controversy over older, lower-quality credits flooding into DeFi through Toucan. That tightening didn't kill on-chain carbon trading. It pushed it toward platforms (ACX, Xpansiv, Klima Protocol) that work more closely with registries rather than around them. See our deep dive on why carbon credit registries are entering blockchain.
4IRE's carbon trading platform
If you're building in this space, 4IRE offers a white-label carbon credit marketplace with token issuance, registry integration hooks and role-based access for offset sellers, compliance buyers and traders already built in. See our cost breakdown and carbon credit tokenization guide for what a project like this typically involves.
Conclusion
The carbon trading market is real, growing, and increasingly running through blockchain-based infrastructure, but the honest version of that story is narrower than the trillion-dollar headlines suggest. The EU ETS remains the anchor of the compliance side at roughly €85/tonne, the on-chain voluntary side is still a small (if fast-growing) fraction of the total, and the platforms with real, checkable volume are a shorter list than most market reports imply. 2026 remains a reasonable moment to enter this market, provided you build against verified numbers rather than whichever forecast sounds most impressive.
Enter the Carbon Trading Market
4IRE's white-label carbon credit marketplace gets you trading, tokenization and registry integration without a from-scratch build.
FAQ on the carbon trading market
It depends what you're measuring. The EU ETS, the largest compliance market, trades allowances at roughly €85/tonne as of September 2026 and covers about 40% of EU emissions today. The voluntary market is smaller and harder to size precisely because pricing and volume are fragmented across dozens of registries; treat any single "total market size" figure with caution unless it states exactly what it's counting.
Tightening regulation (expanding compliance schemes like ETS2), corporate net-zero commitments that require offsetting residual emissions, growing demand for verified carbon removal over cheaper avoidance credits, and blockchain-based infrastructure that reduces settlement friction and improves traceability.
Toucan Protocol ($4B cumulative on-chain volume), AirCarbon Exchange (21M+ tCO2e settled), and Xpansiv (environmental-commodity exchanges plus registry infrastructure) all have verifiable, dated volume as of late 2026. Klima Protocol focuses on retirement infrastructure rather than trading volume specifically.
Regulatory pressure and corporate offsetting demand are both trending toward more carbon trading activity, not less, and the technical building blocks (registry integrations, tokenization patterns, white-label platforms) are more mature than they were even two years ago. The main risk isn't market timing, it's building on unverified registry integrations or credit-quality claims.