

Green finance in 2026 looks less like a marketing category and more like a set of specific, dated changes: a reporting law that got smaller, a bond market that started settling on-chain, and a carbon-credit registry that spent three years working out how tokenization can and cannot be done safely. This guide covers what actually changed, with dates, not another round of generic sustainability trend predictions.
The Regulatory Reset: Europe's Omnibus Simplification
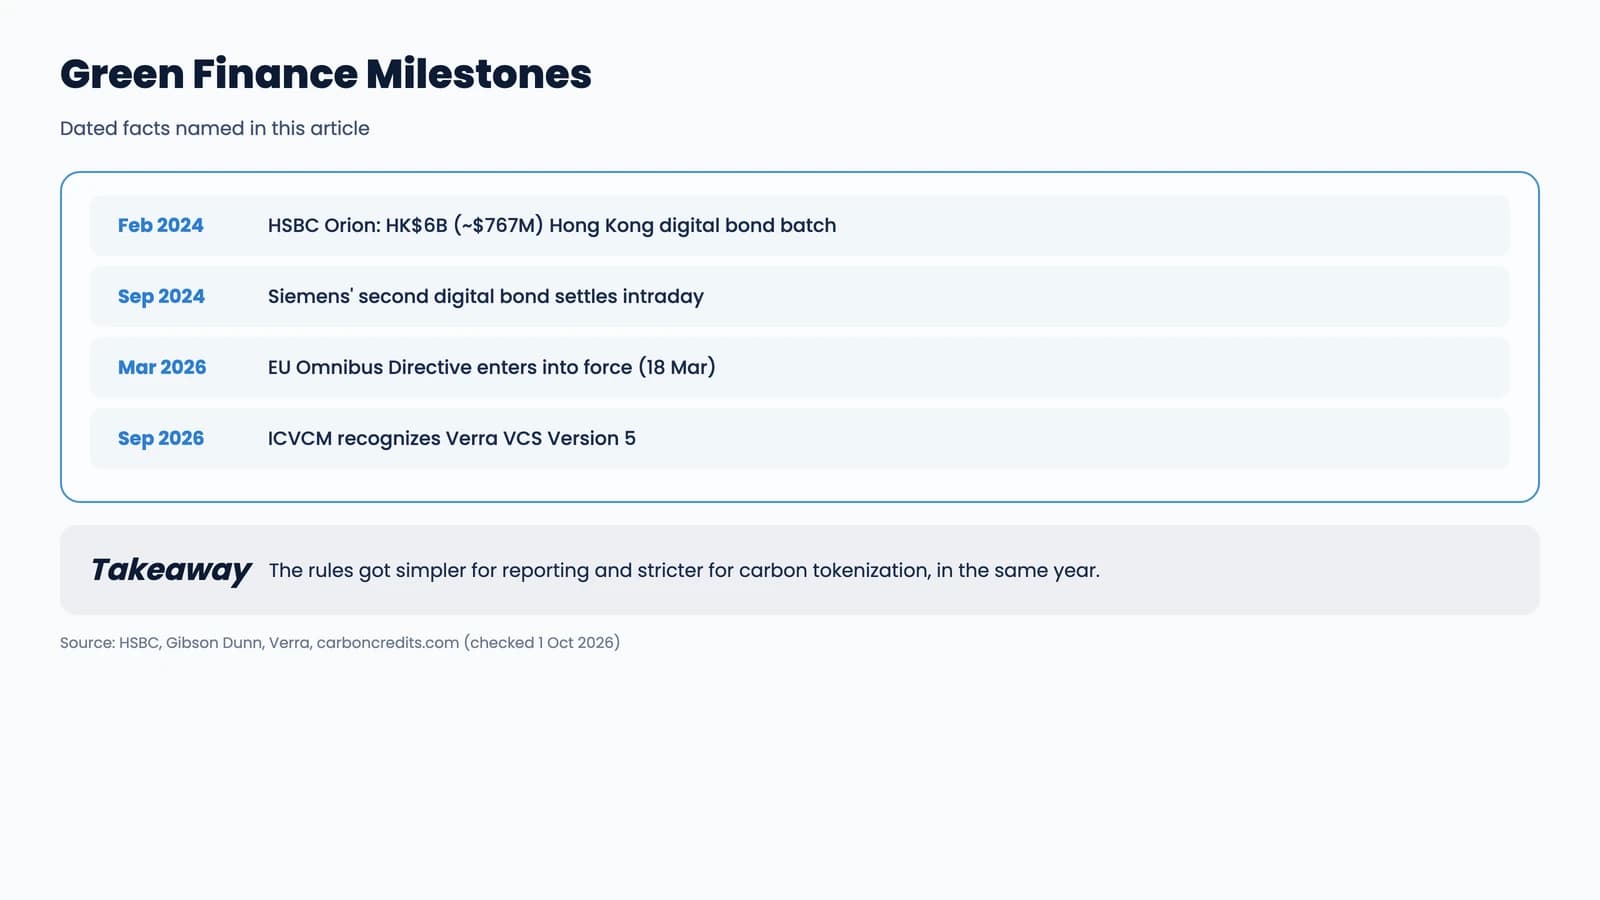
The biggest 2026 development in sustainability reporting was a rollback, not an expansion. The EU's Omnibus Simplification Package, first proposed in February 2025, was finalized as Amendment Directive (EU) 2026/470, published in the Official Journal on 26 February 2026, and entered into force on 18 March 2026. It cuts the number of companies required to report under the Corporate Sustainability Reporting Directive by narrowing the qualifying test to undertakings that exceed both 1,000 employees and €450 million in net turnover, down from a broader two-out-of-three test that used to catch far more mid-sized firms. The Commission's own stated goal was a 25% cut in reporting burden for large companies and 35% for SMEs. For any fintech or asset manager that built CSRD-compliance tooling assuming the original scope, this is a direct, dated change to plan around, not background noise.
Tokenized Green Bonds Moved From Pilot to Repeat Issuance
Digital bond issuance stopped being a one-off experiment in 2024 and has continued as a repeat format since. Hong Kong's government issued its second batch of multi-currency digital bonds on HSBC's Orion platform in February 2024, equivalent to roughly HK$6 billion ($767 million), which HSBC described as the largest digital bond issued to date. Siemens followed its 2023 digital bond with a second issuance in September 2024 that settled intraday in central bank money via delivery-versus-payment, an improvement on the standard T+2 settlement cycle. The European Investment Bank issued two separate €100 million tokenized bonds in November 2024. None of these were green bonds exclusively, but the same settlement infrastructure is now the basis several institutions use specifically for green and sustainability-linked issuance.
Carbon Credit Tokenization Under Stricter Rules
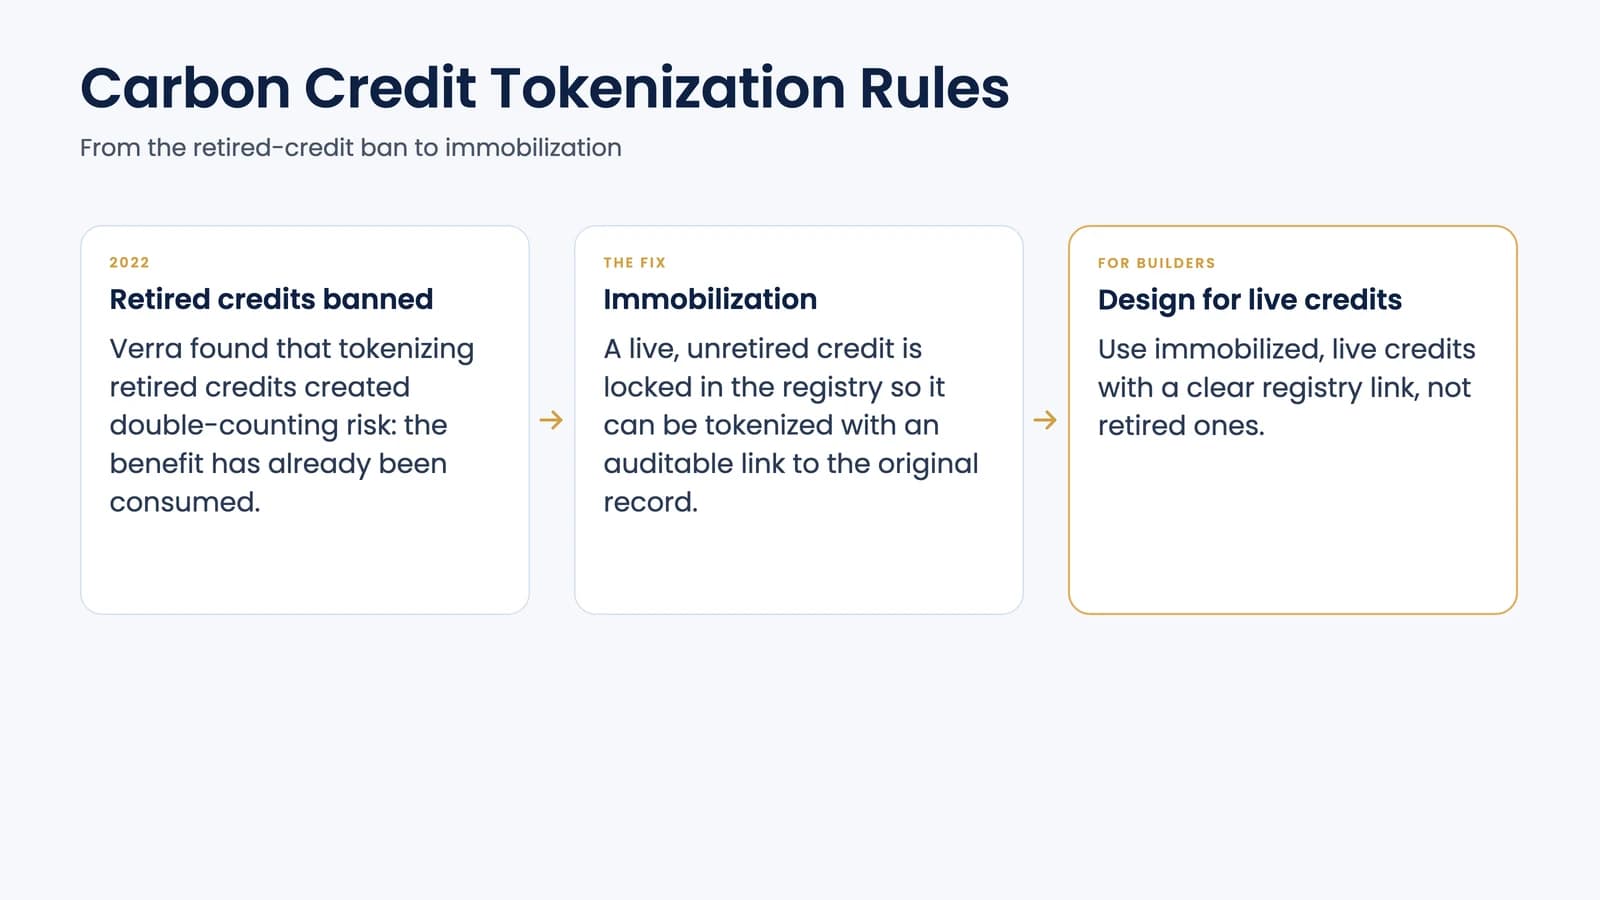
Carbon-credit tokenization has a messier history than bond tokenization, and anyone building in this space should know it. Verra, the largest voluntary carbon registry, banned tokenizing already-retired credits in 2022 after finding the practice created double-counting risk: once a credit is retired, its environmental benefit has been consumed, so wrapping it as a tradable token misrepresents what it still backs. Verra's response was not to ban tokenization outright but to work on an "immobilization" framework, which locks a live, unretired credit in the registry so it can be tokenized with an auditable link back to the original record. In September 2026, the Integrity Council for the Voluntary Carbon Market recognized Verra's newest standard, VCS Version 5, as meeting its core carbon principles, and Verra has been migrating its full project registry, more than 5,900 projects, onto a new platform during 2026. A tokenized carbon-credit product built today should be designed around immobilized, live credits with a clear registry link, not retired ones.
Why the Rules Keep Pointing at the Same Problem
Both changes trace back to the same underlying complaint: too many sustainability claims could not be checked. The original CSRD tried to fix that by asking almost every mid-sized company in Europe to report in detail, which produced volume without necessarily producing verifiable data, and the Omnibus rollback is a response to that trade-off rather than a retreat from sustainability reporting as a goal. Carbon markets had the same problem from the opposite direction: a credit could be sold, tokenized and resold in ways that were technically compliant but practically impossible to trace back to one real tonne of carbon. Verra's immobilization rule and ICVCM's core carbon principles are both attempts to make that link checkable again, not to slow the market down for its own sake.
ESG Data Needs an Audit Trail, Not Just a Dashboard
The practical effect of a smaller CSRD scope and a stricter carbon registry is the same: regulators and registries are both pushing toward verifiable, traceable data, not self-reported claims. A blockchain-based record does not replace the underlying verification work, whether that is a carbon-credit validator or a financial auditor, but it does give that verified data a tamper-evident trail that multiple parties can check against the same source, which is the property both CSRD-style assurance and carbon-market double-counting rules are ultimately asking for.
What This Means for a Build in 2026
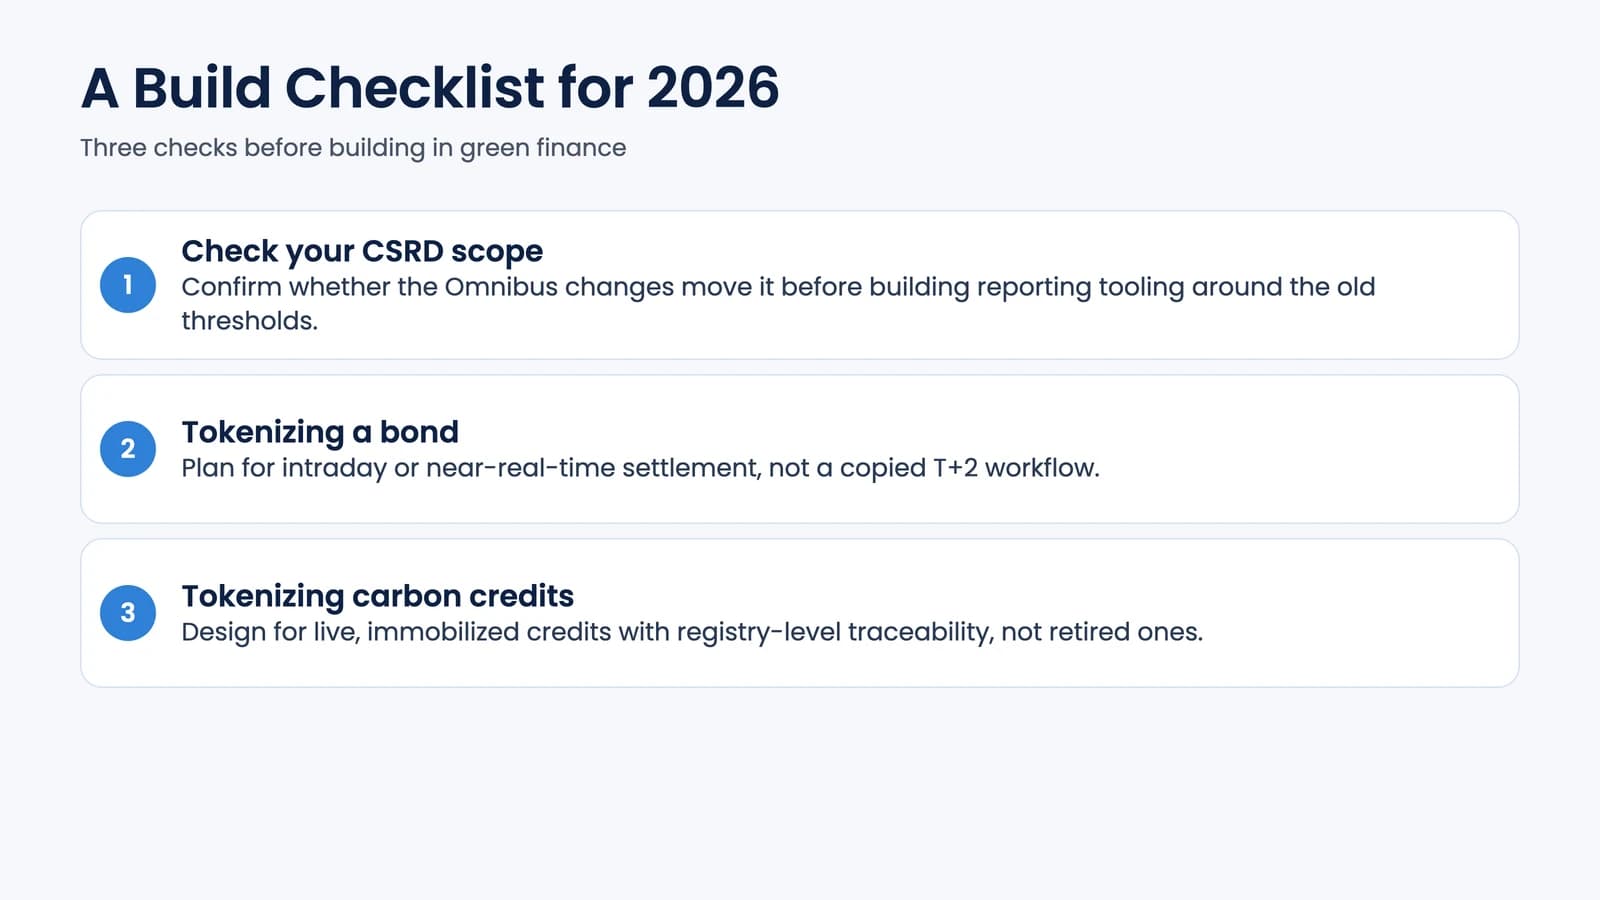
For a fintech, bank or asset manager actually building in this space, the practical checklist looks different from last year's: confirm whether the Omnibus changes move your CSRD scope before building reporting tooling around the old thresholds; if you are tokenizing a bond, plan for intraday or near-real-time settlement, not a copied T+2 workflow; and if you are tokenizing carbon credits, design for live, immobilized credits with registry-level traceability, not retired ones. 4IRE's green finance development and carbon credit marketplace teams build exactly this kind of infrastructure, and our broader real-world asset tokenization guide covers the token-design questions that apply to any tokenized bond or credit, not only green ones.
Conclusion
2026's green finance story is regulatory simplification on one side and stricter tokenization rules on the other, both aimed at the same thing: data and instruments that can actually be verified, not just taken on faith. A team building in this space now has more clarity than it had two years ago about what regulators and registries will and will not accept.
If you are scoping a green bond, carbon-credit or ESG-data product, 4IRE can help you design it around the current rules, not the 2022-era assumptions still floating around the space.
Building a Green Finance Product?
4IRE designs tokenized bonds, carbon-credit infrastructure and ESG data pipelines around the current rules.
Frequently asked questions
A set of changes to the Corporate Sustainability Reporting Directive and related rules, finalized in February 2026 and in force since 18 March 2026, that narrows which companies must report and reduces the required data points, aiming for a 25-35% cut in reporting burden.
Yes, but Verra, the largest voluntary carbon registry, banned tokenizing already-retired credits in 2022 due to double-counting risk. Its current approach is to "immobilize" live, unretired credits in the registry so they can be tokenized with a traceable link back to the original record.
Real and repeating. HSBC's Orion platform, the European Investment Bank and Siemens have all issued multiple digital bonds since 2024, with some settling intraday rather than on the standard two-day cycle.
No. It can make verified data traceable and harder to alter after the fact, but the underlying verification, whether by a financial auditor or a carbon-credit validator, still has to happen off-chain first.