

 GreenFi
Energy infrastructure (solar farms, wind turbines, power purchase agreements, renewable energy certificates) shares a set of traits that make it unusually well suited to tokenization: long asset lifecycles, contracted and fairly predictable cash flows, and historically limited access for anything but large institutional investors. Energy tokenization turns ownership, cash-flow or usage rights in these assets into blockchain-based tokens, opening them to fractional ownership and faster, more transparent trading. Here's how the 4IRE team sees the technical, regulatory and business sides of it in 2026.
What energy tokenization is and isn't
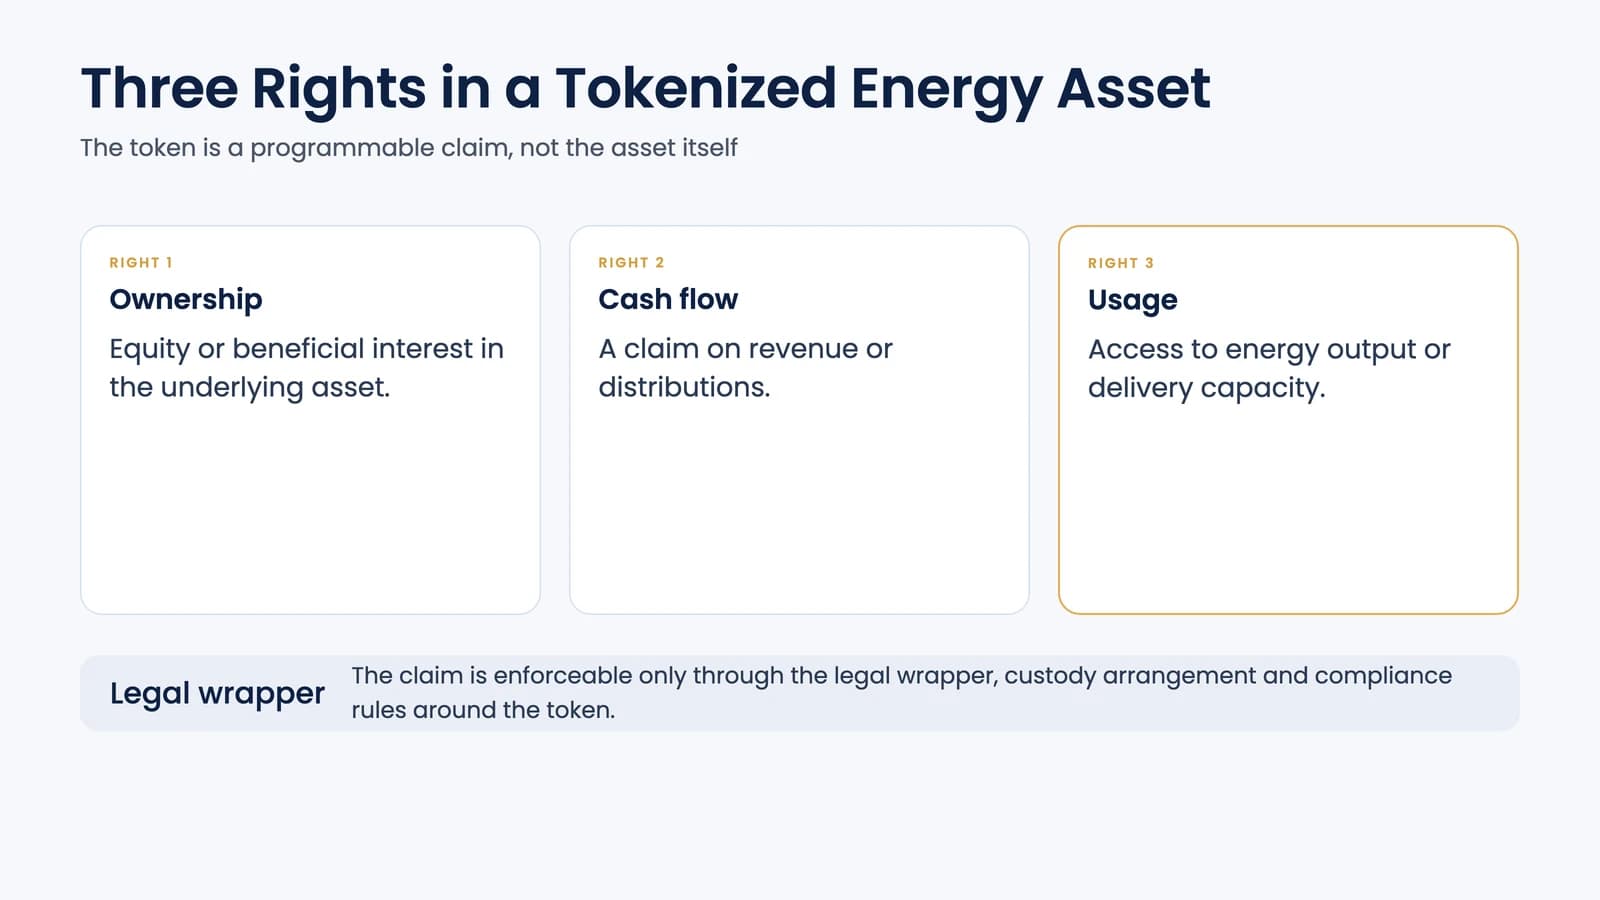
A tokenized energy asset gives its holder one or more of three rights: ownership rights (equity or beneficial interest in the underlying asset), cash-flow rights (a claim on revenue or distributions), or usage rights (access to energy output or delivery capacity). The token is not the asset itself: it's a programmable claim, enforceable only through the legal wrapper, custody arrangement and compliance rules built around it. Our broader real world asset tokenization guide covers this legal-wrapper-plus-token model in more depth.
The parts of the energy value chain being tokenized today include physical infrastructure (solar farms, wind assets, batteries, microgrids), energy output and production rights, power purchase agreements (PPAs), renewable energy certificates (RECs), carbon credits and offsets, and standalone energy revenue streams like capacity payments and grid-service fees.
Why energy assets are a structural fit
- Secondary market liquidity. Energy infrastructure investors have traditionally had to wait years for an exit through refinancing or fund maturity. Tokenization enables smaller, more frequent transfers of fractional stakes instead.
- Accessibility. Fractional ownership opens large energy projects to smaller institutions, family offices and accredited investors who couldn't previously write a check for the full project.
- Transparency. REC and carbon-credit markets suffer from registry fragmentation and inconsistent reporting; a shared, tamper-evident ledger record improves auditability.
- Settlement. Cross-border energy finance runs on slow, manual settlement rails today; smart-contract-based settlement standardizes onboarding, payment routing and event logging.
The technical stack
Asset structuring
A legal wrapper (usually an SPV, project company or trust) holds the underlying asset or contractual rights, giving token holders an enforceable claim through shares, notes or units in that vehicle rather than a direct, undefined claim on the physical asset. Oracle integrations then link the on-chain token to real-world data: metering output, NAV, or contract performance.
Token standards
ERC-20 is the simplest, most widely supported fungible-token standard, but it has no native identity or compliance hooks, which makes it a poor fit for regulated energy securities on its own. ERC-3643 (T-REX), which reached Final status in December 2023, and the older ERC-1400 family both add identity-aware transfer restrictions, whitelisting and compliance modules, which is the more common choice for tokenizing anything that behaves like a security.
Compliance and identity
KYC/AML and investor-eligibility checks need to be enforced at the contract level, not just in the platform's UI, or a technically compliant project becomes practically unbankable: institutional investors won't touch a token whose compliance depends on a website behaving correctly.
Settlement and custody
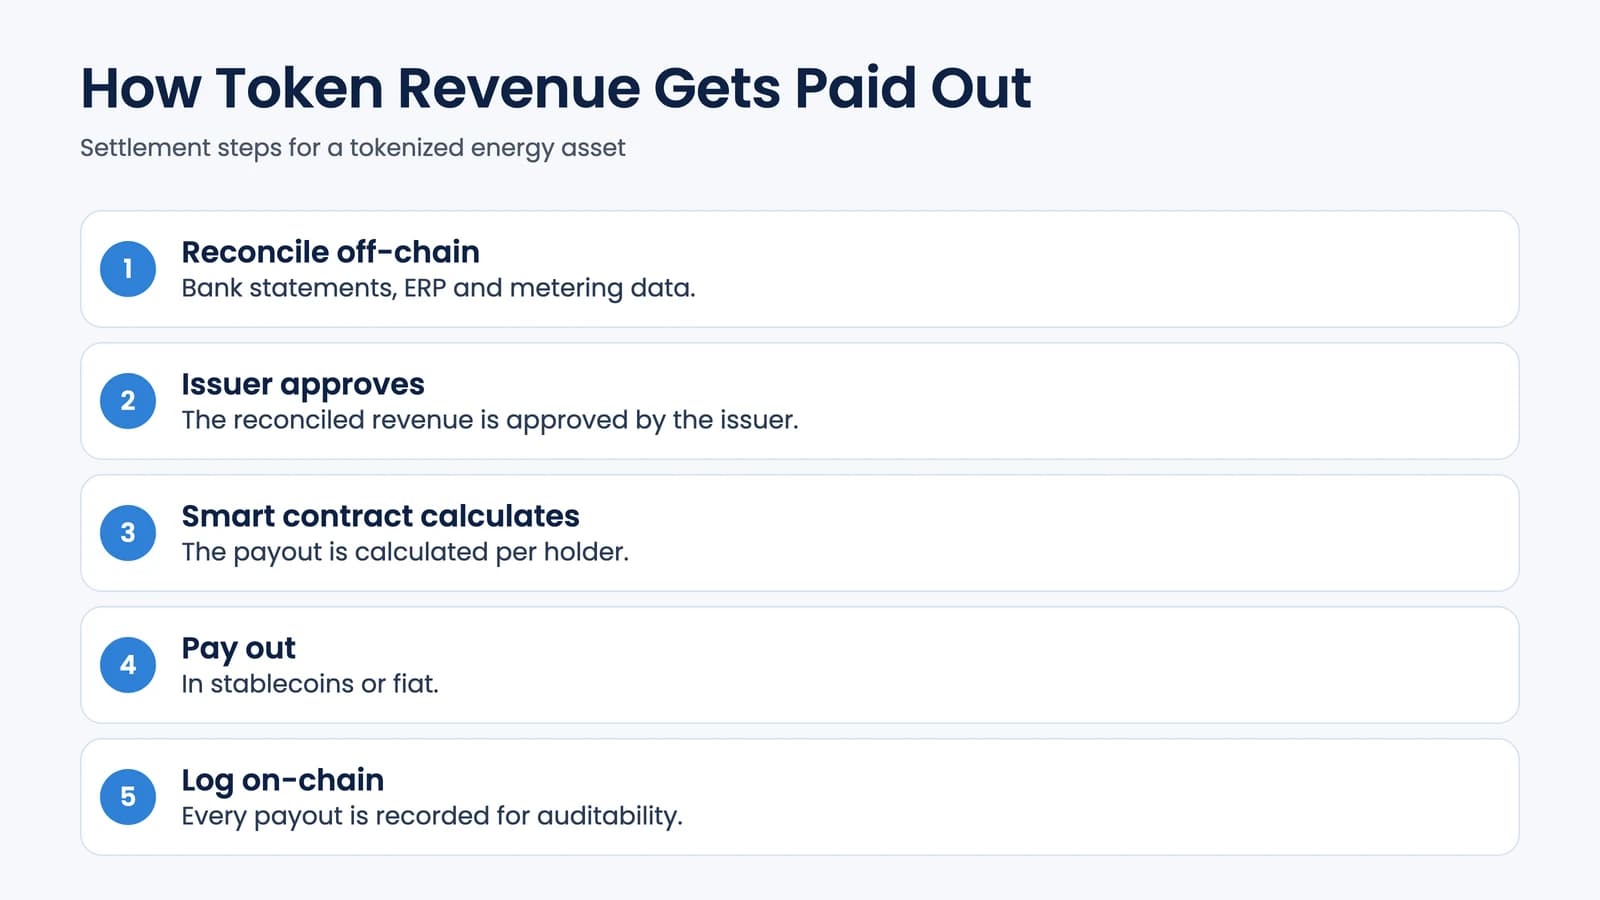
Revenue typically gets reconciled off-chain (bank statements, ERP, metering data), approved by the issuer, calculated per-holder by a smart contract, paid out in stablecoins or fiat, and logged on-chain for auditability. Custody runs through self-custody, institutional custodians, or multi-sig arrangements requiring multiple sign-offs for sensitive actions. Because most energy assets still earn in fiat, a credible platform needs solid fiat-to-crypto reconciliation rails, not just a wallet.
Secondary markets
Permissioned on-chain order books, permissioned DEX-style venues, and request-for-quote models are all in use for low-liquidity energy assets, with pricing benchmarked against NAV, yield comparables, market-maker quotes, or scheduled auction windows.
Regulation by region
- European Union. MiCA covers crypto-assets that are not financial instruments; a tokenized energy asset with investment rights typically falls outside MiCA and under MiFID II instead, the same split that applies to other tokenized securities.
- United States. Energy tokens with investment characteristics are generally evaluated under SEC securities rules, following the same issuer-sponsored vs. third-party distinction the SEC staff laid out for tokenized securities generally.
- UAE. Dubai's VARA framework and the ADGM/DIFC regimes give tokenization projects a defined licensing path, which is part of why the UAE has become a common jurisdiction for RWA and energy tokenization pilots.
Licensing and legal structuring are usually the longest item on the critical path for an energy tokenization project, so plan for that up front rather than treating it as a late-stage formality.
Build vs. buy
Building an energy tokenization platform from scratch typically means a 12-18 month timeline and a budget in the low millions once legal, compliance, audits and custody integrations are all accounted for, on top of the ongoing maintenance and regulatory risk of owning the full stack. A white-label foundation, like 4IRE's RWA tokenization solution, shortens that considerably by starting from audited, pre-built modules for issuance, KYC/AML and investor onboarding, while still giving you source-code ownership rather than SaaS-style vendor lock-in. See the hidden risks of SaaS tokenization platforms for why that ownership question matters.
Where this sits in the broader RWA market
As of late September 2026, RWA.xyz tracked roughly $38.6 billion in distributed tokenized real-world assets across dozens of networks, with tokenized commodities (mostly gold) at about $5.2 billion. Energy-specific tokens (solar and wind project tokens, tokenized PPAs, on-chain RECs) remain a small niche within that total rather than a major, separately tracked category on the leading RWA dashboards today, which is worth knowing before building a business case around this segment: the infrastructure and legal patterns are mature, but on-chain volume specifically in energy tokens is still early. Carbon credits, a closely related asset class, are covered in depth in our carbon credit tokenization guide.
Real-world activity
Powerledger and Energy Web are two of the more established players building blockchain infrastructure for renewable energy certificate issuance, tracking and trading, with deployments across multiple markets including parts of Asia-Pacific. Toucan Protocol remains the largest blockchain-native infrastructure specifically for carbon credits, the energy-adjacent asset class with the most verifiable on-chain volume today ($4 billion cumulative, per Toucan's own reporting). Community and cooperative energy models (local groups pooling capital to own and govern shared solar or wind assets) are an active area of interest among European blockchain sandboxes and pilots, though most individual projects are still too early-stage to cite specific, durable statistics on.
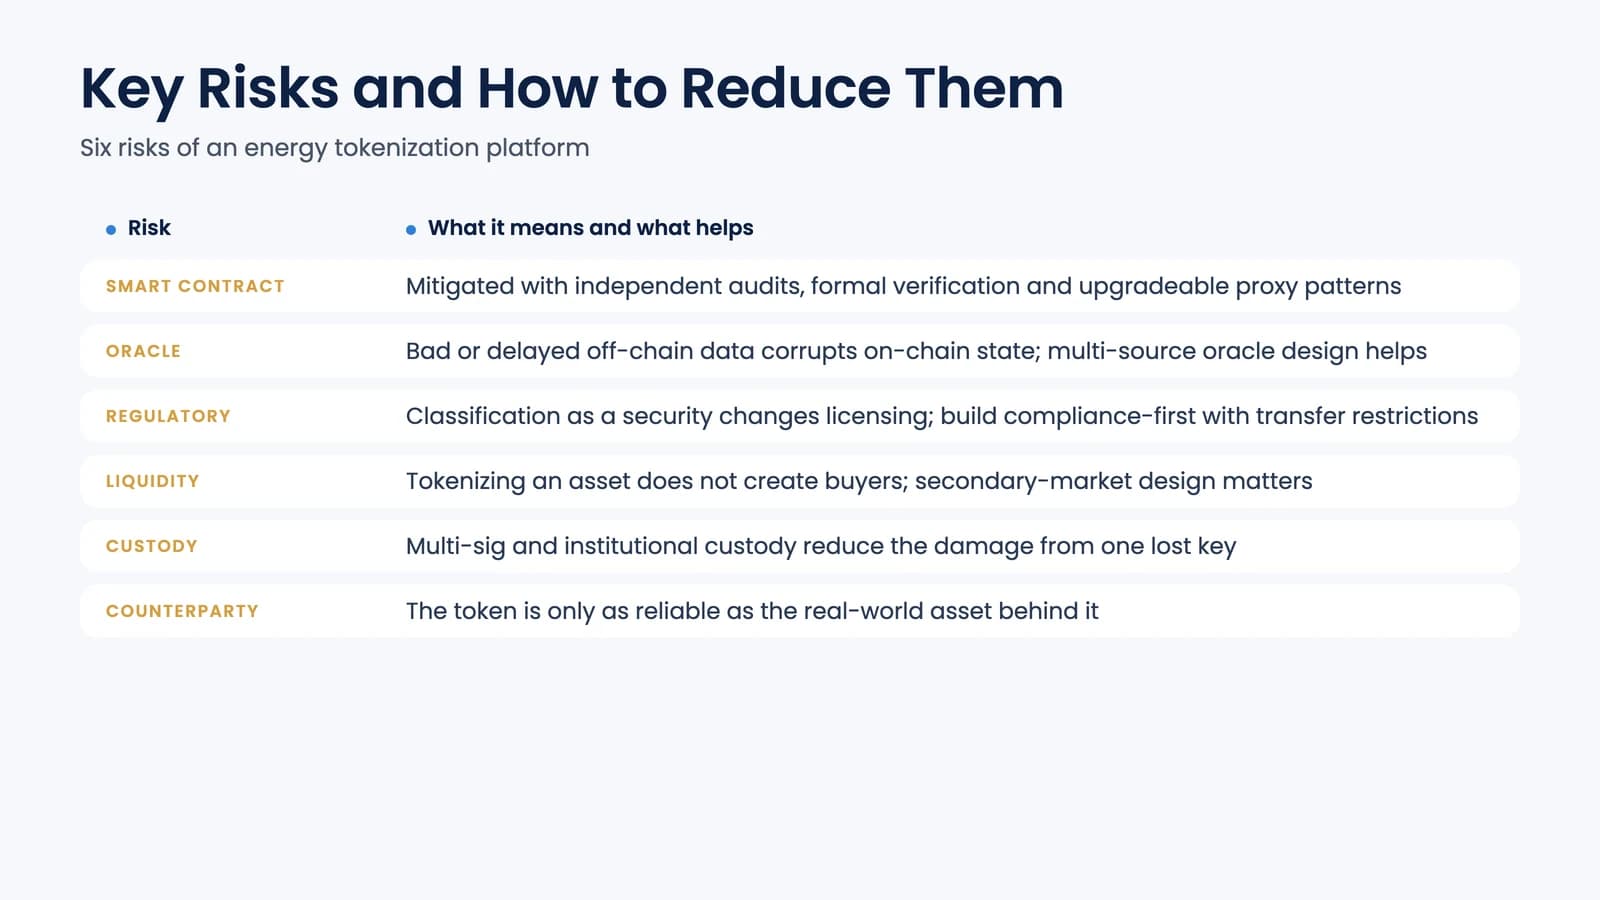
Key risks
- Smart contract risk. Mitigated with independent audits, formal verification, and upgradeable proxy patterns.
- Oracle risk. Bad or delayed off-chain data corrupts on-chain state; multi-source oracle design reduces single-point failure.
- Regulatory risk. Classification as a security changes licensing and disclosure requirements; a compliance-first architecture with transfer restrictions built in avoids costly retrofits.
- Liquidity risk. Tokenizing an asset doesn't create buyers for it; secondary-market design and liquidity incentives matter as much as the token itself.
- Custody risk. Multi-sig and institutional custody integrations reduce the damage from a single lost or compromised key.
- Counterparty risk. The token is only as reliable as the real-world asset behind it; on-chain settlement automation reduces intermediary dependency but doesn't eliminate this risk.
Conclusion
Energy assets are a structural fit for tokenization (predictable cash flows, high capital intensity, and a long history of limited investor access), but a working platform is a full legal-and-technical build, not a smart contract deployment. Compliance-first architecture, solid custody design, and a realistic read on how much genuine secondary-market liquidity your specific asset will attract matter more than the token standard you pick. The same infrastructure questions apply to adjacent asset classes like gold tokenization; talk to our blockchain consulting team if you're scoping an energy tokenization project.
Scope Your Energy Tokenization Project
From legal structuring to token issuance and secondary-market design, our team can help you build a compliant, deployable energy tokenization platform.
FAQ about energy tokenization in 2026
The process of turning ownership, cash-flow or usage rights in energy assets (infrastructure, PPAs, RECs, carbon credits) into blockchain-based tokens backed by a legal wrapper and, where relevant, a regulated custodian.
It enables fractional ownership of large, historically illiquid energy assets, improves transparency and auditability of RECs and carbon credits, and automates settlement through smart contracts, though it doesn't create secondary-market demand or fix a weak underlying asset.
ERC-20 for simple, non-regulated fungible tokens; ERC-1400 or ERC-3643 for anything that behaves like a security, since both add identity-aware transfer restrictions and compliance hooks that ERC-20 lacks natively.
Set up a legal wrapper (typically an SPV) that owns the physical asset, define investor rights and the token standard, integrate KYC/AML at the contract level, issue compliant tokens to verified investors, and connect a secondary-market venue once there's real demand to trade on.
Yes, when structured to the requirements of the relevant jurisdiction, which vary: MiCA generally doesn't cover investment-type energy tokens in the EU (MiFID II does), the SEC evaluates them under securities law in the US, and the UAE has a defined licensing path through VARA/ADGM/DIFC.