


Traditional banks adopting crypto used to be a headline. In 2026, it is a line item on the product roadmap. US regulators have withdrawn the restrictive guidance of 2022–2023, and the EU’s MiCA regime is now fully in force. As a result, a bank can add crypto custody, trading or stablecoin payments as crypto modules inside its existing app, instead of launching a separate crypto bank.
This guide covers what changed in regulation, what a crypto module for banks actually consists of, how to choose between building, partnering and white-label, and which compliance and security controls the module needs from day one. If you need the basics first, start with our explainer on what crypto banks are and how they work.
What Is a Crypto Module for Banks?
A crypto module is a set of digital-asset services plugged into a bank’s existing core banking system, mobile app and compliance stack. The customer keeps one account, one KYC profile and one app; the module adds new features on top. The typical building blocks are:
- Custody. Safekeeping of the private keys that control client assets, either in-house (MPC or HSM-based wallets) or through a regulated sub-custodian.
- Trading and brokerage. Buying, selling and holding a short list of assets, usually routed to a partner for liquidity and execution.
- Stablecoin and tokenized deposit rails. Holding, sending and receiving payment stablecoins or bank-issued deposit tokens for 24/7 settlement.
- On/off-ramp. Conversion between the customer’s fiat balance and crypto, with the fiat leg settled on the bank’s own ledger.
- Compliance layer. Wallet screening, transaction monitoring and Travel Rule messaging connected to the bank’s existing AML case management.
Most banks start with one or two of these, typically trading through a partner or custody for institutional clients, and extend the module later.
Why Banks Are Adopting Crypto Now
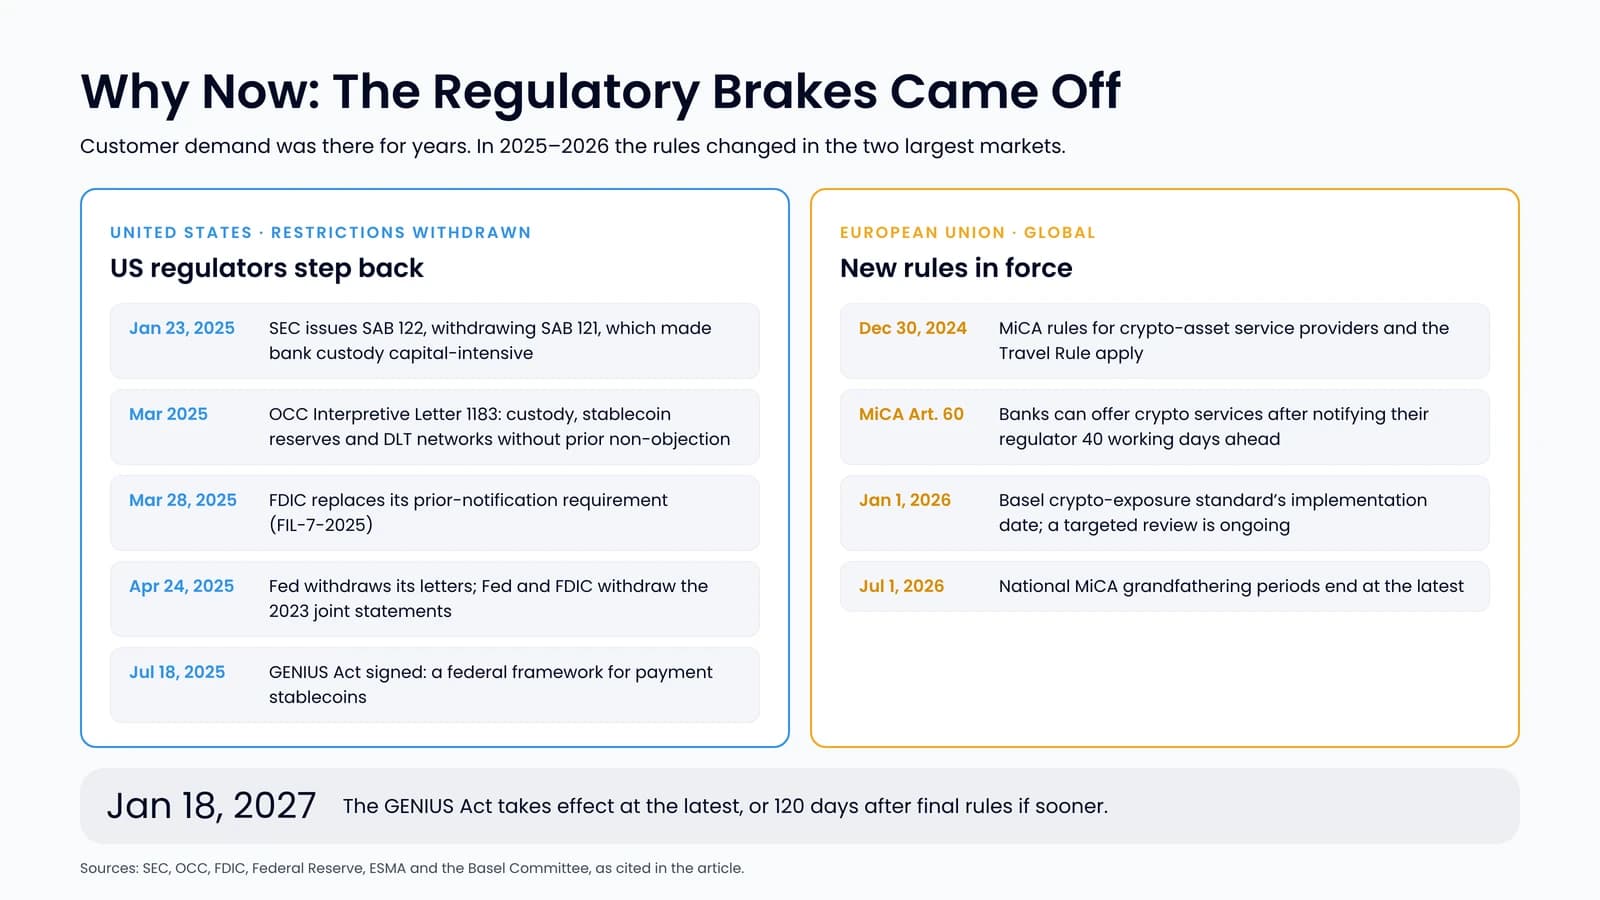
Customer demand has been there for years. What changed in 2025–2026 is that the regulatory brakes came off in the two largest markets.
United States
- SAB 121 rescinded. On January 23, 2025, the SEC issued Staff Accounting Bulletin 122, withdrawing SAB 121. The old guidance required firms safeguarding client crypto to record its full value as a liability, which made bank custody capital-intensive. U.S. Bank, for example, paused its custody service under SAB 121 and restarted it in September 2025.
- OCC Interpretive Letter 1183. In March 2025, the OCC confirmed that national banks may provide crypto custody, hold stablecoin reserves and take part in distributed ledger networks without first obtaining supervisory non-objection.
- Fed and FDIC withdrawals. The FDIC replaced its prior-notification requirement with FIL-7-2025 on March 28, 2025. On April 24, 2025, the Federal Reserve withdrew its own notification and non-objection letters, and the Fed and FDIC withdrew their 2023 joint statements on crypto-asset risks.
- The GENIUS Act. Signed on July 18, 2025, it creates a federal framework for payment stablecoins. The OCC (February 2026), the FDIC (April 2026), Treasury and the Federal Reserve (September 2026), among others, have proposed implementing rules; as of September 2026 none is final. The Act takes effect on January 18, 2027, or 120 days after final regulations are issued, whichever comes first.
European Union
- MiCA is fully live. The regime for crypto-asset service providers has applied since December 30, 2024, and national grandfathering periods ended no later than July 1, 2026, as ESMA reminded the market.
- A shorter route for banks. Under MiCA Article 60, a credit institution does not need a separate CASP authorisation. It can offer crypto-asset services after notifying its home regulator at least 40 working days in advance.
- Travel Rule. The recast Transfer of Funds Regulation (EU) 2023/1113 has applied to crypto-asset transfers since December 30, 2024.
Global Capital Rules
The Basel Committee’s prudential standard for banks’ cryptoasset exposures had a January 1, 2026 implementation date. In November 2025, the Committee expedited a targeted review, largely because assets on permissionless blockchains, including most stablecoins, cannot qualify for the lower-risk Group 1 treatment. In May 2026, it said the review was progressing and an update would come later in the year. Check how your supervisor applies it before taking balance-sheet exposure.
The commercial drivers are unchanged: customers already hold crypto elsewhere, trading and custody earn fees, and corporate clients want faster settlement. Now those benefits outweigh the regulatory cost for many banks.
Who Is Already Doing It
- PNC. In December 2025, PNC launched direct spot bitcoin trading for PNC Private Bank clients inside its own digital banking platform, powered by Coinbase’s Crypto-as-a-Service infrastructure. Coinbase handles custody and execution.
- Morgan Stanley. In July 2026, E*TRADE completed the rollout of spot trading in bitcoin, ether and solana through a linked zerohash account.
- U.S. Bank. In September 2025, it resumed bitcoin custody for institutional investment managers, with NYDIG as sub-custodian.
- J.P. Morgan. In November 2025, Kinexys made JPM Coin (JPMD), a USD deposit token, available to institutional clients on the Base blockchain. We compare this model with bank-issued stablecoins in stablecoins vs deposit tokens.
- Société Générale-FORGE. It issues EUR CoinVertible and, since June 2025, USD CoinVertible, both e-money tokens under MiCA.
- DBS. DBS Digital Exchange, announced in December 2020, offers crypto trading, custody and tokenisation to institutional and accredited investors.
Note the pattern: almost every client-facing launch runs on a partner’s custody and execution, while the bank keeps the customer relationship, the app and the fiat leg.
Build, Partner or White-Label
- Partner (Crypto-as-a-Service). The fastest route. The provider runs custody, execution and part of the compliance, and the bank integrates through APIs. The trade-offs are vendor dependency, revenue sharing and limited control over the product.
- Build in-house. Full control over custody, ledger and user experience, but the longest timeline, a dedicated security team and, depending on the jurisdiction, additional licences. Our overview of licences for fintech and crypto businesses covers the main options. This route makes sense for custody-led institutional businesses.
- White-label. A pre-built crypto banking core, rebranded and integrated with the bank’s systems. 4IRE’s white-label crypto bank solution includes integrated KYC providers and a custodial wallet, with a one-time licence fee and full ownership of the source code.
Compliance and Security Requirements
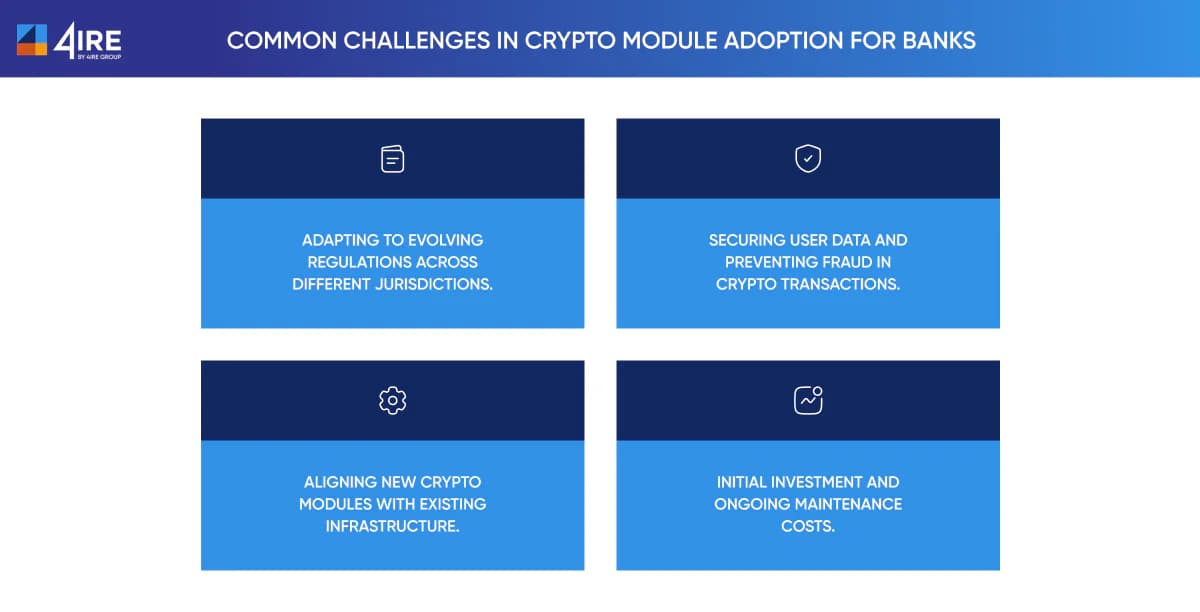
- Travel Rule. Originator and beneficiary data must accompany transfers between crypto service providers, in line with FATF Recommendation 16 and, in the EU, the Transfer of Funds Regulation. The module needs counterparty discovery and a policy for self-hosted wallets.
- Know-your-transaction (KYT). Screen deposit and withdrawal addresses for sanctions and illicit-activity exposure, and route alerts into the bank’s existing AML workflow.
- Key management. MPC or HSM-based signing, segregation of client assets and a policy engine for withdrawals. This is where experienced crypto wallet development matters most.
- Smart contract risk. If the module interacts with stablecoin or tokenized deposit contracts, the contracts and integration logic need an independent smart contract audit.
- Accounting and capital. After SAB 122, US issuers assess custody obligations under the contingency guidance in ASC 450; capital treatment follows the local implementation of the Basel standard.
Key Risks to Plan For
- Vendor concentration. If a partner has an outage or loses a licence, your product goes down with it. Negotiate exit terms and asset portability up front.
- Operational and cyber risk. Hot wallet compromise remains the main loss scenario. Use withdrawal limits, cold storage and tested incident plans.
- Regulatory drift. GENIUS Act rules are not final and the Basel review is ongoing. Keep asset lists, limits and compliance rules configurable rather than hard-coded.
- Market and suitability risk. Volatility creates complaints and reputational exposure. Start with a short asset list, clear disclosures and eligibility checks.
How to Roll Out a Crypto Module
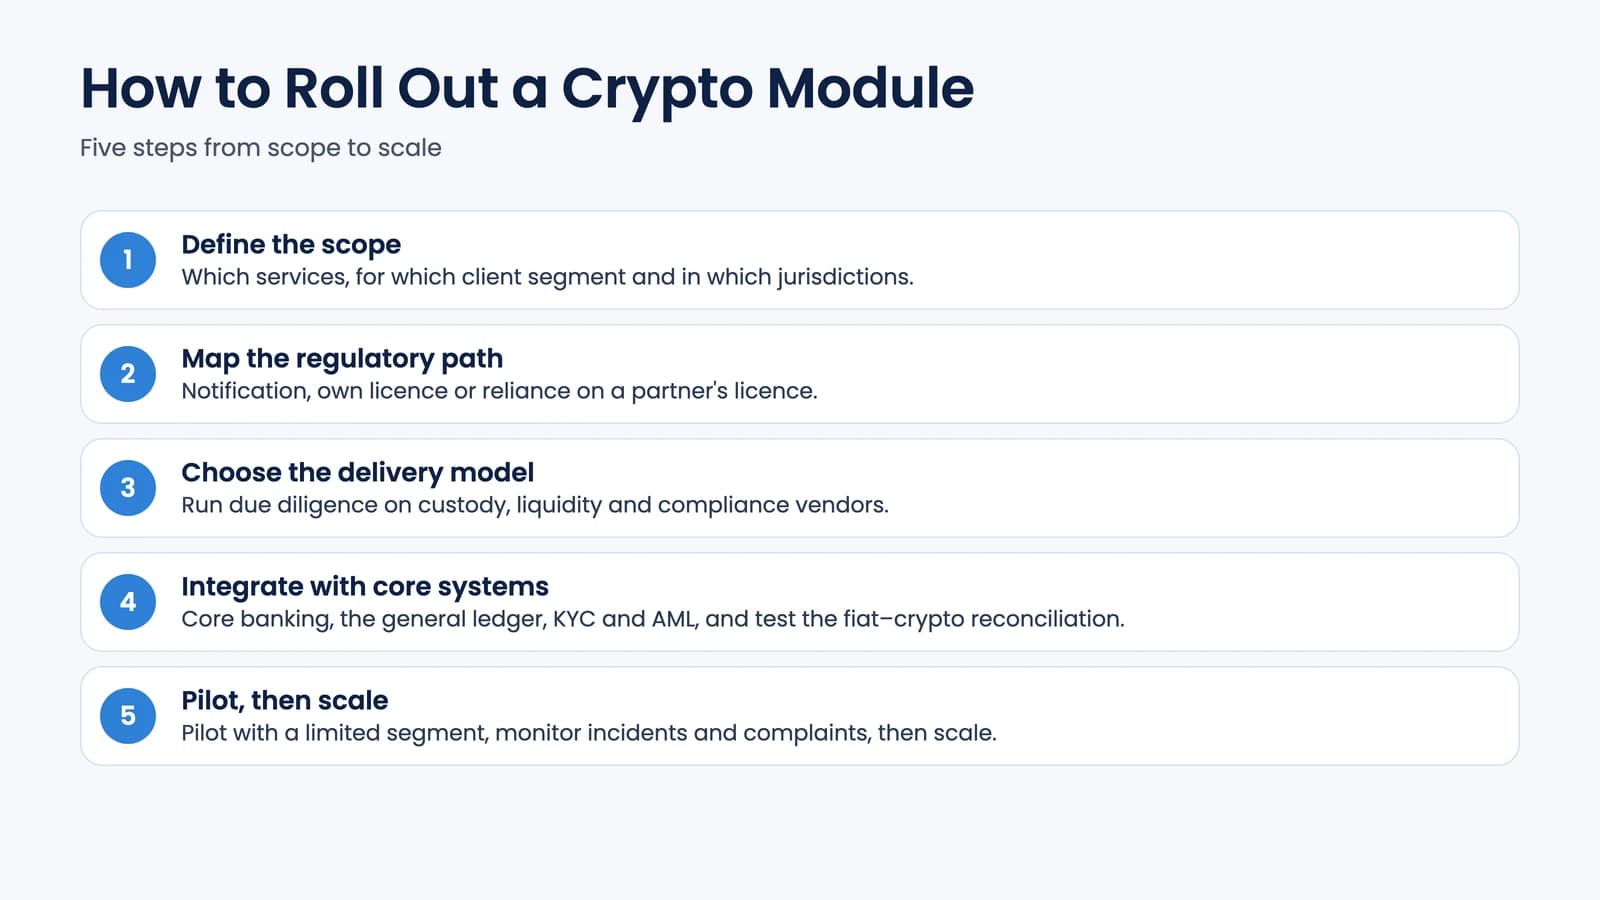
- Define the scope: which services, for which client segment and in which jurisdictions.
- Map the regulatory path: notification, own licence or reliance on a partner’s licence.
- Choose the delivery model and run due diligence on custody, liquidity and compliance vendors.
- Integrate with core banking, the general ledger, KYC and AML systems, and test the fiat–crypto reconciliation.
- Pilot with a limited segment, monitor incidents and complaints, then scale.
If you are planning a standalone institution rather than a module, see our step-by-step guide on how to build a crypto bank.
Conclusion
For most banks, the question is no longer whether crypto services are allowed, but which ones to offer and how to run them safely. A modular approach lets a bank start small, keep control of the customer relationship and add stablecoin or tokenized deposit rails as the rules settle.
The 4IRE team works on crypto banking software development, from custodial wallets and payment integrations to white-label crypto bank cores. If you are scoping a crypto module, we can help you choose the right model and build it around your existing infrastructure.
Learn more from us
 AI06 Oct 2026
Lovable AI App Builder in 2026: The Vibe Coding Risks Behind 1 Million Projects a Week
Lovable reports 1M new projects a week and $500M ARR. A CTO's view on what that means for startups, and the security risks of vibe coding to plan for.
Oleksandr Vlasenko
 Blockchain news28 Sept 2026
Crypto Wallet Development Cost in 2026: A Full Breakdown
How much does crypto wallet development cost in 2026? 4IRE's estimates by tier, platform and feature, plus running costs and what drives the budget.
Olena Petrashchuk
 Blockchain news28 Sept 2026
Real World Asset Tokenization in 2026: A Practical Guide to RWA
Real world asset tokenization explained: asset classes, how the stack works, 2026 RWA market data, US, EU, Singapore and UAE rules, and how to launch.
Olena Petrashchuk
FAQ
Because the main regulatory obstacles were removed in 2025. In the US, SAB 121 was rescinded, the OCC confirmed that national banks may provide crypto custody, and the Fed and FDIC withdrew their restrictive guidance. In the EU, MiCA gives credit institutions a notification route to offer crypto-asset services. A module lets banks meet existing customer demand without launching a separate institution.
It depends on the jurisdiction. In the EU, a credit institution can provide crypto-asset services under MiCA Article 60 after notifying its home regulator at least 40 working days in advance. In the US, national banks may provide crypto custody under OCC Interpretive Letter 1183, while state-chartered banks follow their state and federal supervisors. In the UK, firms carrying out cryptoasset activities must currently register with the FCA for anti-money-laundering purposes. Partnering with a licensed provider can shift part of this burden.
A crypto bank is an institution built around digital assets from the start. A crypto module adds specific services, such as custody, trading or stablecoin payments, to an existing bank’s app and core system, reusing its customer base, KYC and compliance processes.
Yes, within the rules. The GENIUS Act allows subsidiaries of insured depository institutions to become permitted payment stablecoin issuers once the implementing regulations are in place. In the EU, e-money tokens under MiCA can be issued by credit institutions and e-money institutions. Some banks choose tokenized deposits instead, which remain a claim on the bank itself.
The 4IRE team develops crypto banking software, custodial wallets and payment integrations, and offers a white-label crypto bank solution. We can help you choose between building, partnering and white-label, then integrate the module with your core banking, KYC and AML systems.