

 Cryptocurrency
Crypto cashback works like the cashback on any card or shopping app, with one difference: the reward arrives as a crypto-asset, such as bitcoin, a stablecoin or the provider's own token, instead of cash or points. For wallets, crypto banks and card issuers, it has become a common way to win users and give them a reason to spend through the app.
This guide explains how crypto cashback works, who pays for it, what real programmes look like today, and the product and compliance decisions to make before you add it to your own wallet or card.
What Is Crypto Cashback?
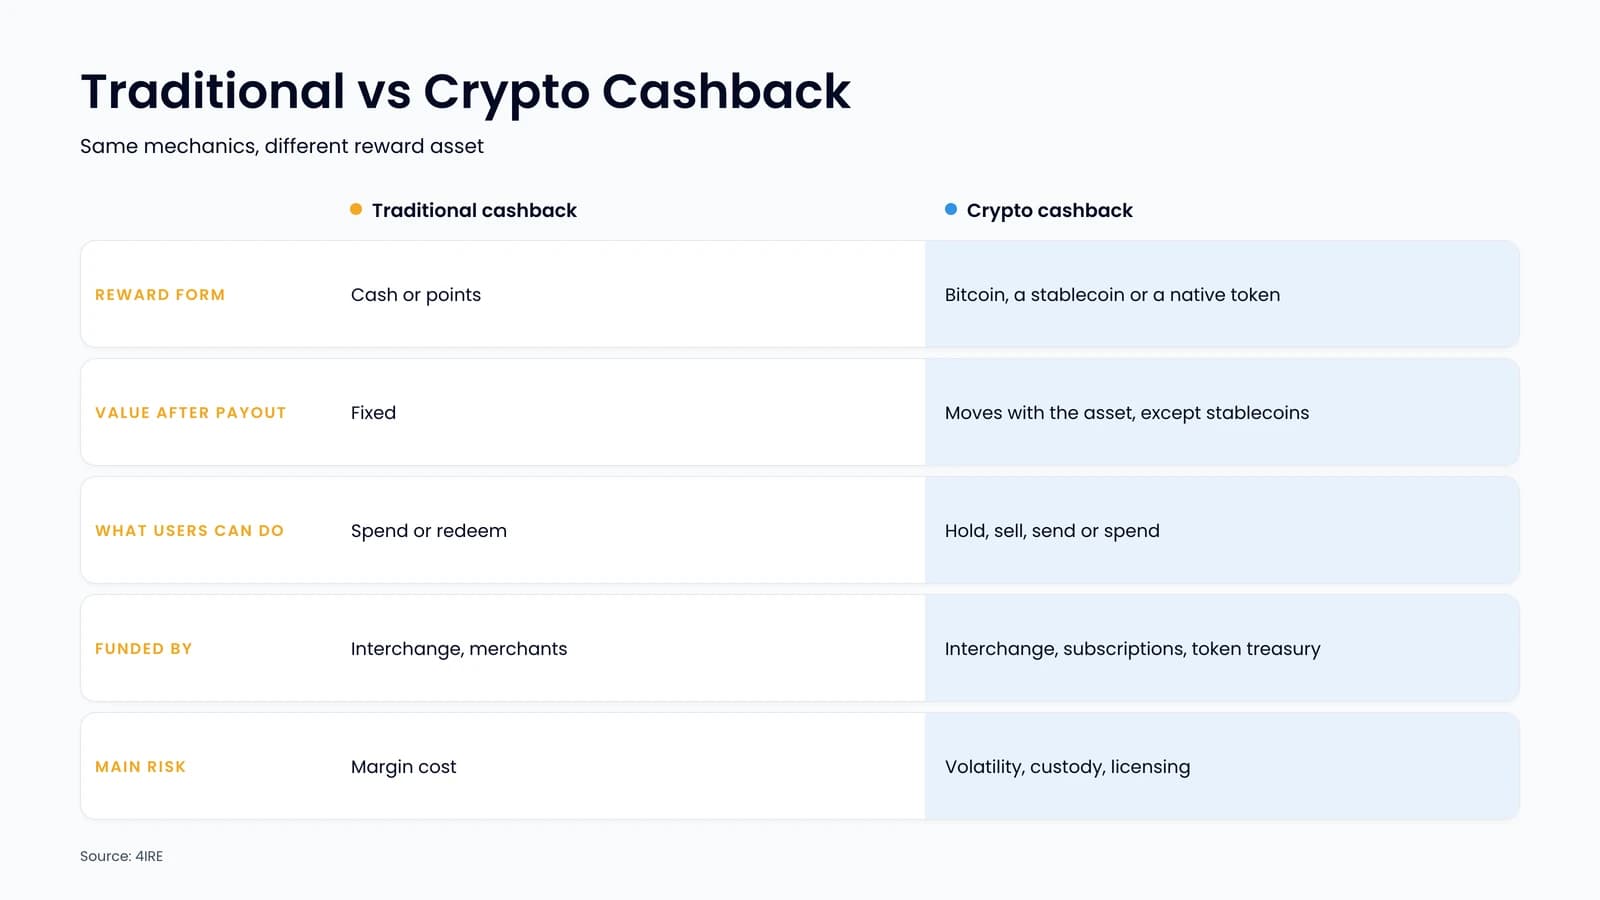
With traditional cashback, a provider returns part of what a customer spends: a flat rate on everything, a higher rate in chosen categories, or tiers that depend on spending or balance. Crypto cashback keeps these mechanics but credits the reward in a crypto-asset. The customer can hold it, sell it, spend it or, in some apps, stake it.
The choice of reward asset changes the product. A stablecoin reward behaves much like cash. A bitcoin reward gives users exposure to the asset's price. A reward in the provider's own token doubles as a way to distribute that token, and ties the value of the programme to it.
How Crypto Cashback Works
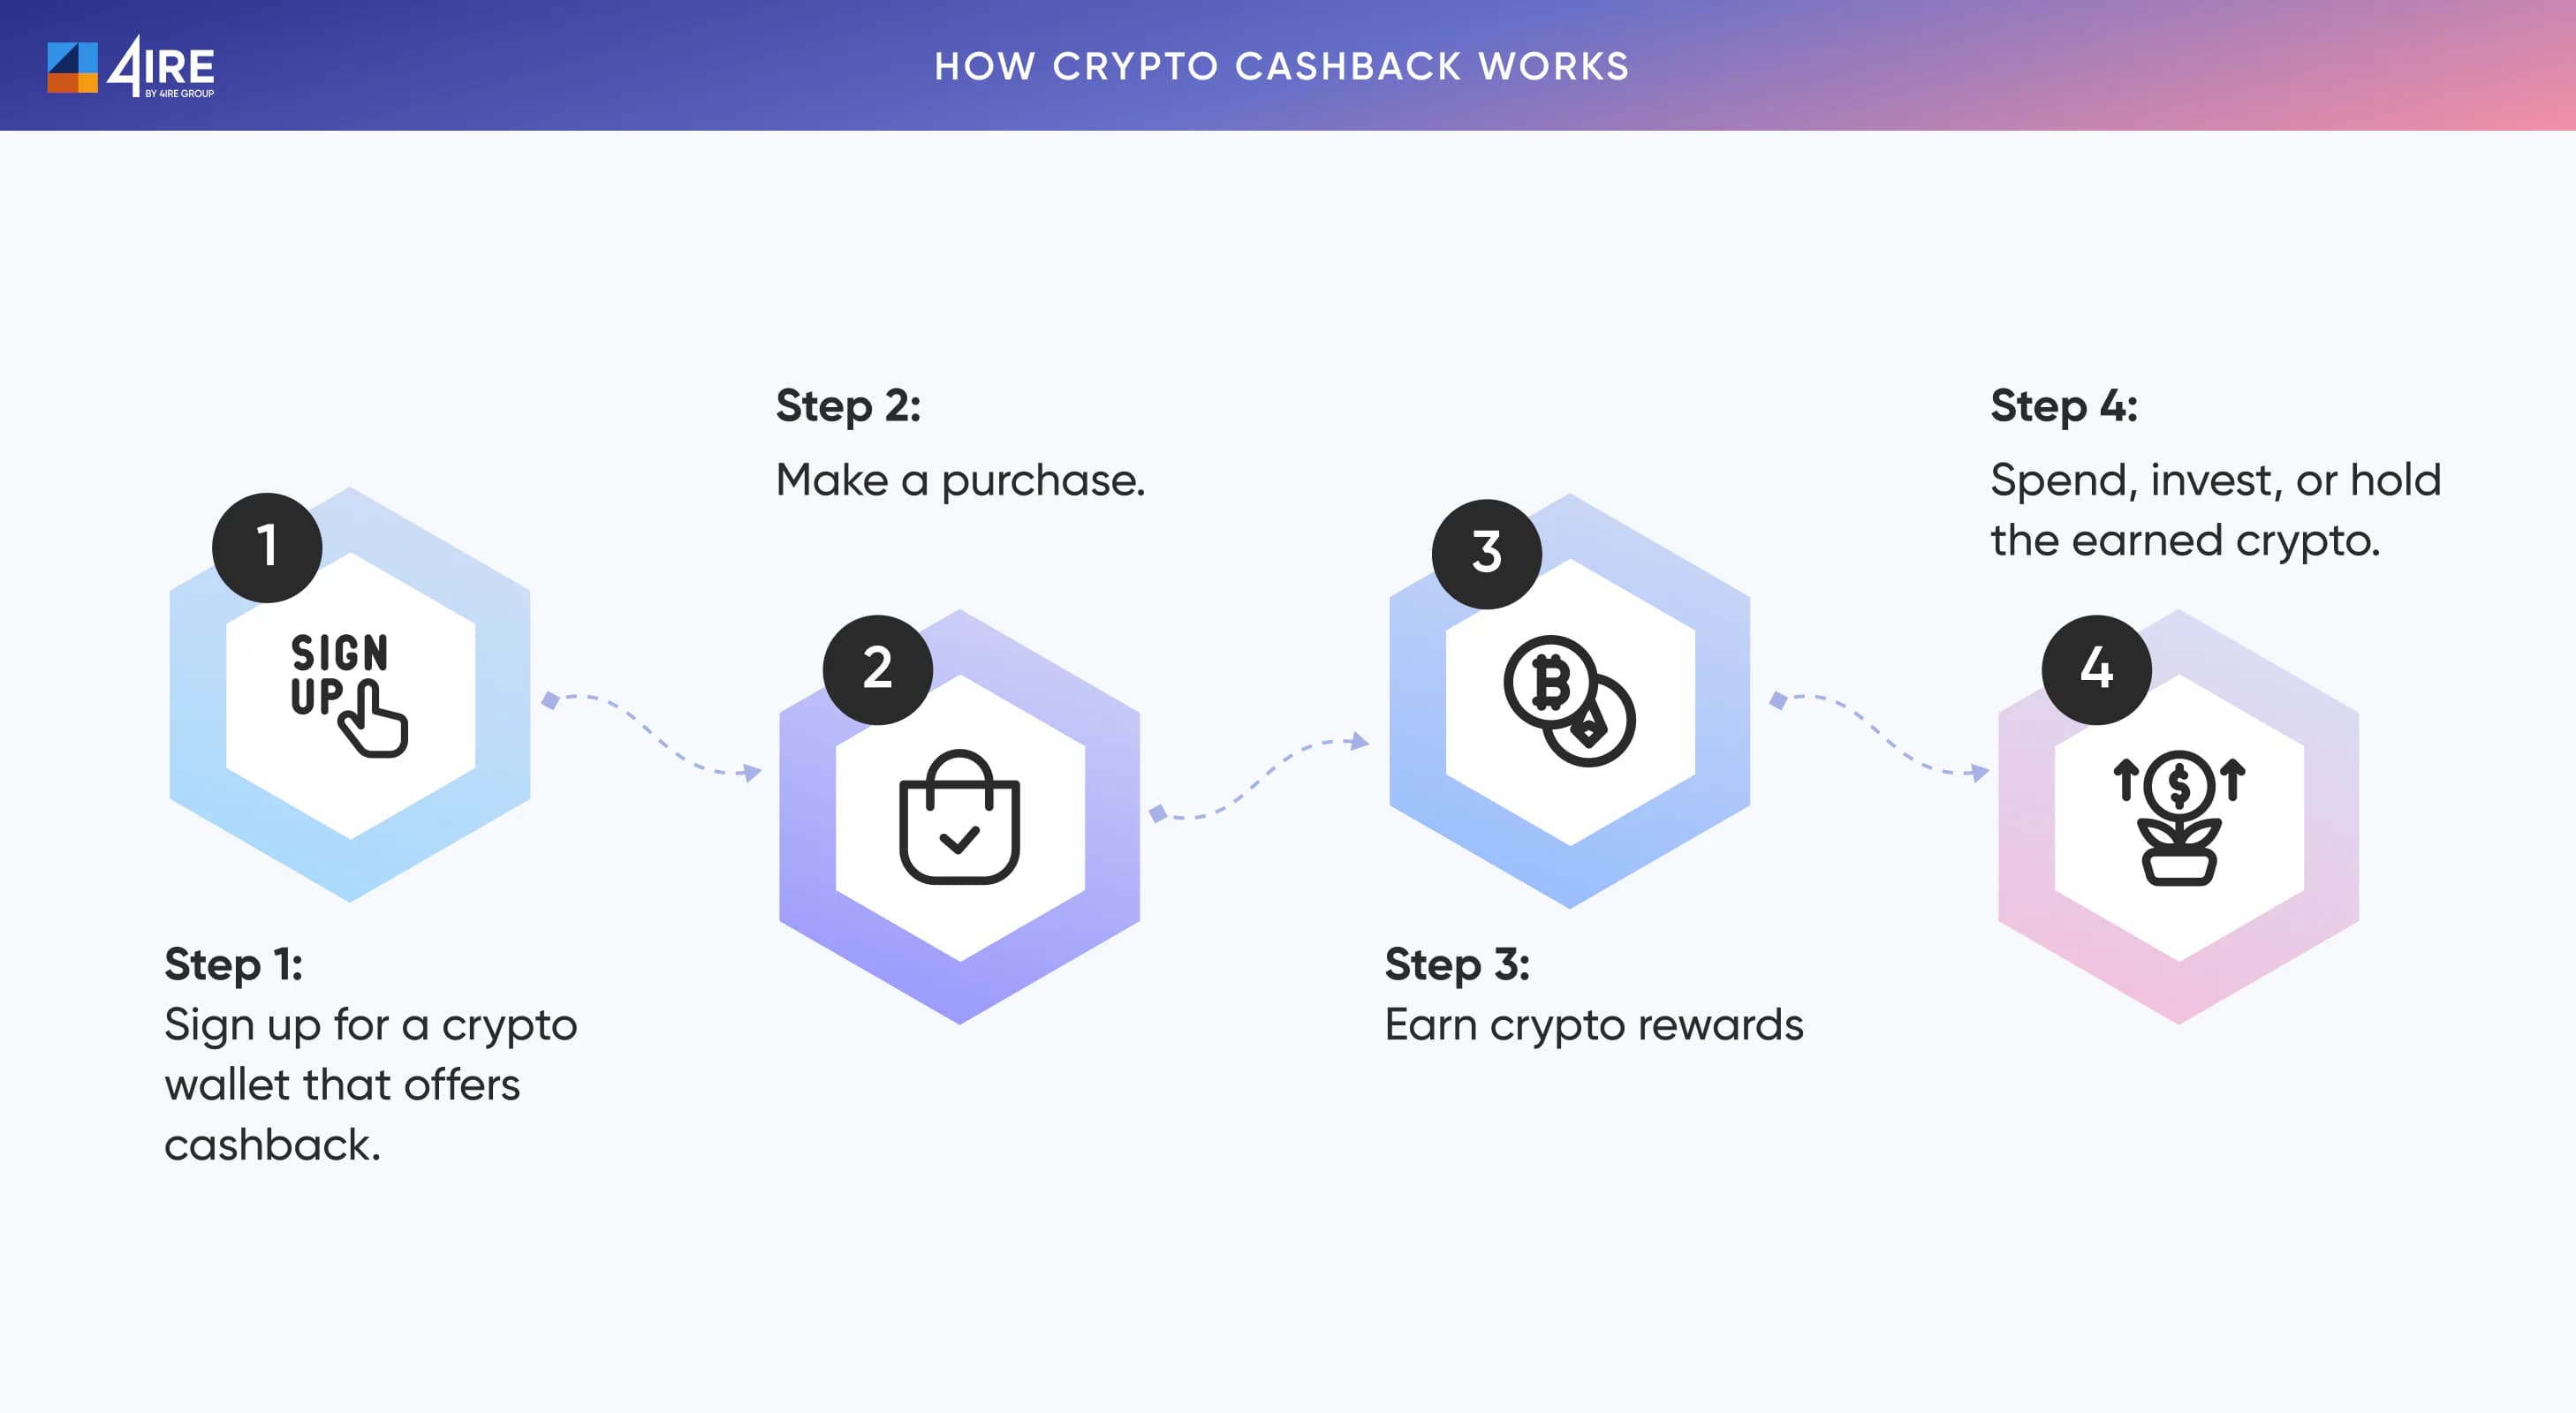
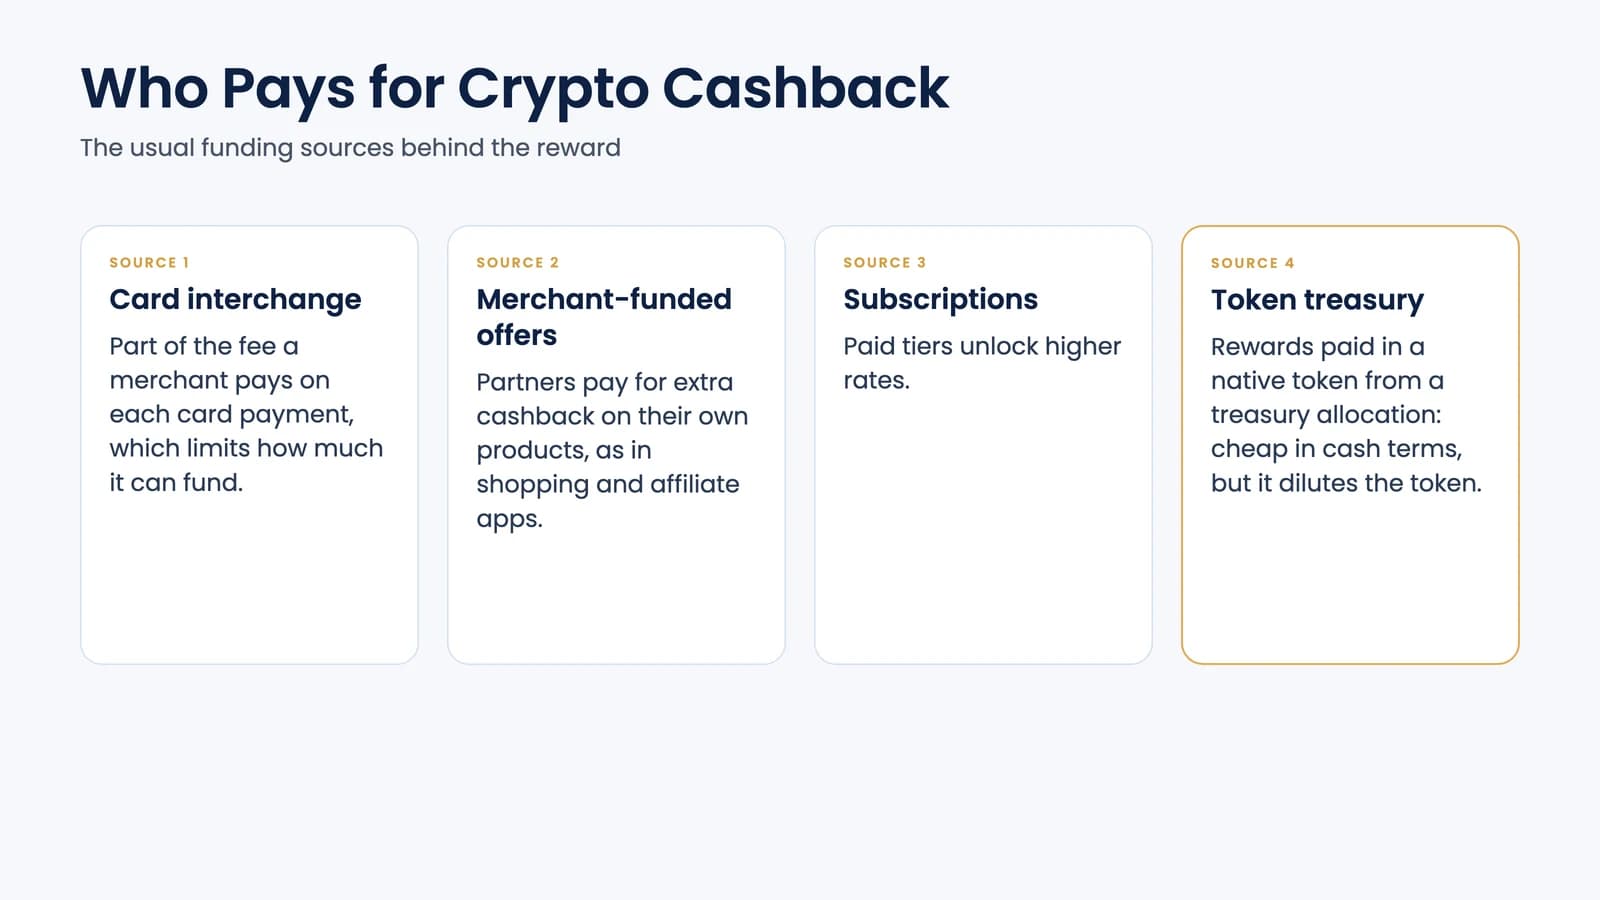
Behind these four steps, the provider has to fund the reward, buy or allocate the reward asset, credit it to the user's account, and keep custody records that stand up to an audit. The funding sources are usually one or more of these:
- Card interchange: part of the fee a merchant pays on each card payment. In the EU, the Interchange Fee Regulation caps interchange on consumer cards at 0.2% for debit and 0.3% for credit, which limits how much it can fund.
- Merchant-funded offers: partners pay for extra cashback on their own products, as in shopping and affiliate apps.
- Subscriptions: paid tiers unlock higher rates.
- Token treasury: rewards paid in a native token from a treasury allocation, which is cheap in cash terms but dilutes the token if not designed carefully.
Real-World Examples
Rates change often, so the figures below are as published on each provider's site on 30 September 2026:
- Crypto.com Visa Card: rewards paid in CRO through five "Level Up" tiers, from 0% on the free tier to 5% on the top tier. Paid tiers are subscriptions, the top tiers require a large CRO stake, and the two paid entry tiers have monthly reward caps. Details.
- Gemini Credit Card: a Mastercard issued by WebBank that pays 4% on gas, EV charging and transit (up to $300 of spending a month), 3% on dining, 2% on groceries and 1% on everything else, in bitcoin or another of the more than 50 crypto-assets available on Gemini. Details.
- Fold: a bitcoin rewards company whose parent, Fold Holdings, is listed on Nasdaq. It offers a prepaid debit card and a bitcoin credit card issued by Celtic Bank with a 1.5% base reward in bitcoin.
The pattern is clear: rewards are funded by a mix of interchange, subscriptions and token economics, and the most generous rates come with conditions.
Why Businesses Offer Crypto Cashback
- Acquisition: a visible reward rate is an easy message in a crowded market, especially for users who want to own crypto without buying it directly.
- Retention and spending: users who earn on every payment have a reason to make the card their default.
- Engagement: rewards can extend to referrals, onboarding tasks and other actions that help the product.
- Token distribution: projects with a native token use cashback to put it in the hands of active users.
For a neobank or wallet, cashback is one of the usual growth levers alongside fee-free FX and referrals, as our guide to launching a neobank describes. Like any reward, it costs money, so model the unit economics before you set the rate.
How to Add Crypto Cashback to Your Product
There are three main ways to build it:
- Partner programme: work with a card issuer and processor that already supports crypto rewards, and add the rewards view to your app. Fastest, but with the least control over rates and assets.
- Rewards engine in your own app: you run the ledger, reward rules and payouts, while licensed partners handle card issuing and custody. This is the most common path for wallets that already hold crypto for users.
- Full in-house stack: card programme, custody and rewards under your own licences. The most control and the highest cost.
The rewards engine sits on top of a wallet. Our guides on how to build a mobile wallet app and on crypto wallet development cost cover that foundation.
Key Design Decisions
- Reward asset: a stablecoin is predictable for users and for your balance sheet; bitcoin appeals to long-term holders; a native token needs sound tokenomics so rewards do not simply become selling pressure.
- Price risk: if you promise a percentage of spend but pay in a volatile asset, decide when you buy the asset and who carries the price change between purchase and payout.
- Custody: rewards held in a custodial account need secure storage, segregation and reconciliation; paying straight into a self-custody wallet shifts that burden but adds onboarding friction.
- Rules and caps: category rates, monthly caps and excluded merchants protect margins, but hidden conditions damage trust. Publish them clearly.
- Redemption: let users sell, send or spend rewards easily, and show the fiat value at the time they were earned for their records.
- Fraud controls: returns, refunds and chargebacks must claw back rewards, and referral bonuses need limits so they cannot be farmed with fake accounts.
Compliance and Tax
A crypto reward is still a financial product. If you buy, hold or transfer crypto-assets for users in the EU, that is a crypto-asset service under MiCA, and the transitional period for providers ended on 1 July 2026, so you need full authorisation or a licensed partner. Card programmes bring their own issuing and payment rules. Our overview of fintech and crypto licences covers the main regimes.
Tax treatment of crypto rewards differs by country and can differ from cash rebates, so give users clear transaction records and take local advice before launch.
Challenges to Plan For
- Volatility: rewards can lose value after payout, and users may blame the app.
- Margin pressure: generous launch rates are hard to cut later without churn.
- Regulatory change: rules on crypto-assets and card rewards keep evolving.
- Integration effort: card processing, ledgers and custody must reconcile to the cent.
How 4IRE Can Help
4IRE is a crypto wallet development company that builds wallets, crypto banking software and the rewards engines on top of them. A short discovery phase is the fastest way to settle the reward asset, funding model and licensing route before development starts.
FAQ
A reward that returns part of what a customer spends as a crypto-asset, such as bitcoin, a stablecoin or the provider's own token, instead of cash or points.
It depends on the user. Crypto rewards can grow or fall in value after payout and can be moved or spent on-chain, while cash rewards keep their value. Stablecoin rewards sit in between.
A stablecoin is the most predictable for users and for your balance sheet. Bitcoin appeals to long-term holders. A native token can support your ecosystem but needs careful tokenomics so rewards do not become constant selling pressure.
Usually you need a licence or a licensed partner. In the EU, buying, holding or transferring crypto-assets for users is a crypto-asset service under MiCA. Card programmes also need a licensed issuer. Take legal advice for each market.