

A central bank digital currency (CBDC) is digital money issued directly by a central bank, rather than by a commercial bank or a private company. It shares its underlying technology with cryptocurrencies but not their governance: a central bank fixes its value and controls issuance, so it carries none of the volatility of Bitcoin or the private-issuer risk of a stablecoin. It also sits alongside a wider shift toward digital-first banking that's already reshaping how neobanks and incumbents alike deliver financial services.
The state of play has shifted a lot since this topic first became mainstream. The US has explicitly ruled out a retail CBDC, several Asian projects are genuinely live, and the EU is still years from a launch decision. This piece covers what a CBDC actually is, where the major projects stand as of September 2026, the design choices behind any CBDC, and what it means for commercial banks either way.
What is a CBDC?
Money already exists as cash and as commercial bank deposits you access through mobile and online banking. Neither of those is quite a CBDC: cash is physical, and a bank deposit is a claim on a commercial bank, redeemable in cash on demand, and not itself a direct central bank liability. A CBDC is different again: an exclusively digital form of central bank money, with no physical equivalent, that a central bank issues and whose value it fixes directly.
A CBDC generally:
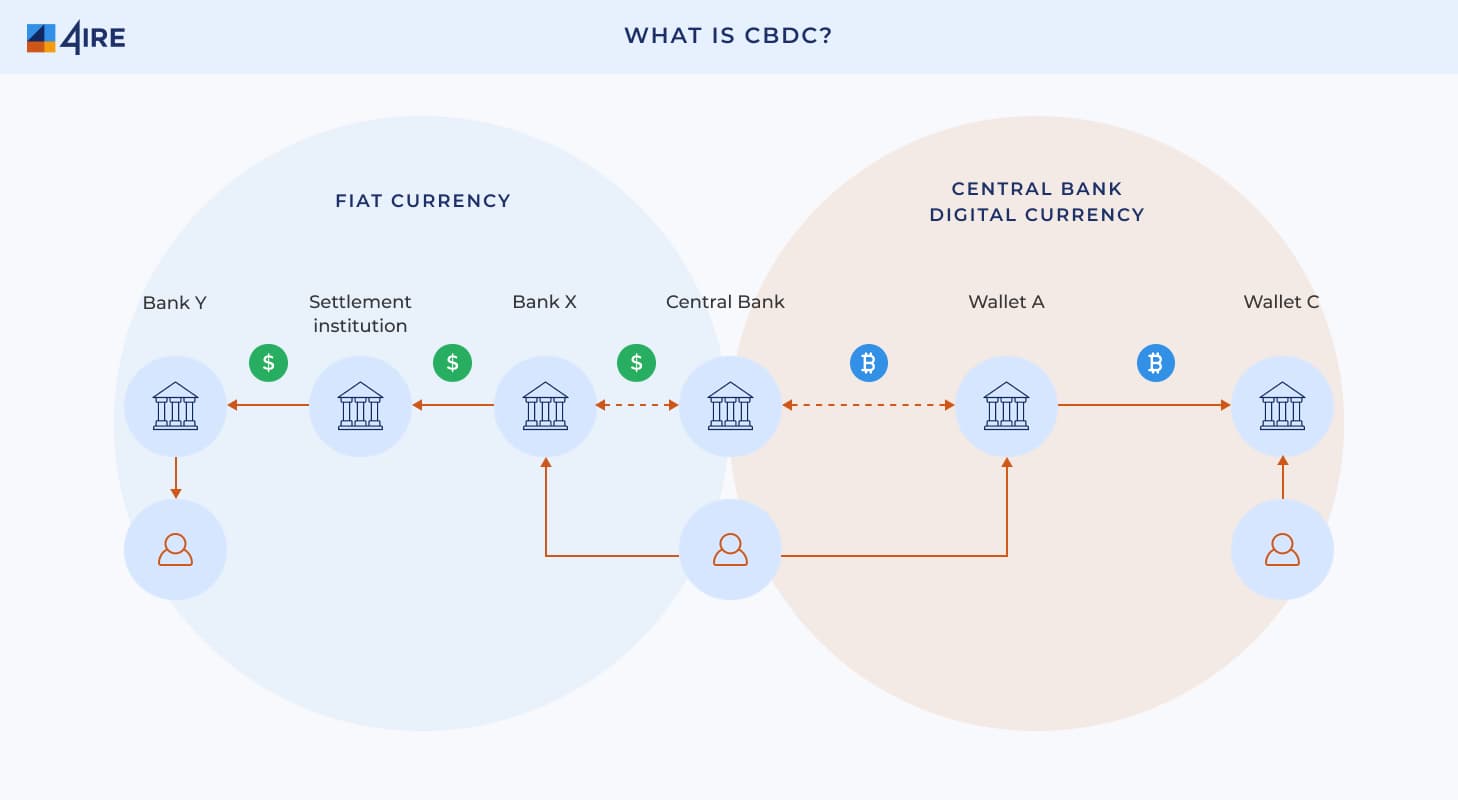
- Exists as a parallel settlement rail alongside the traditional commercial-banking system, not a replacement built on top of it.
- Moves money out of commercial bank deposits and into central bank liabilities whenever someone converts fiat into CBDC. This is a design detail every central bank has to manage carefully.
- Can settle directly between users in a retail design, without a commercial bank as intermediary, which is the source of both its efficiency claims and its disintermediation risk.
CBDC vs. cryptocurrency vs. stablecoins
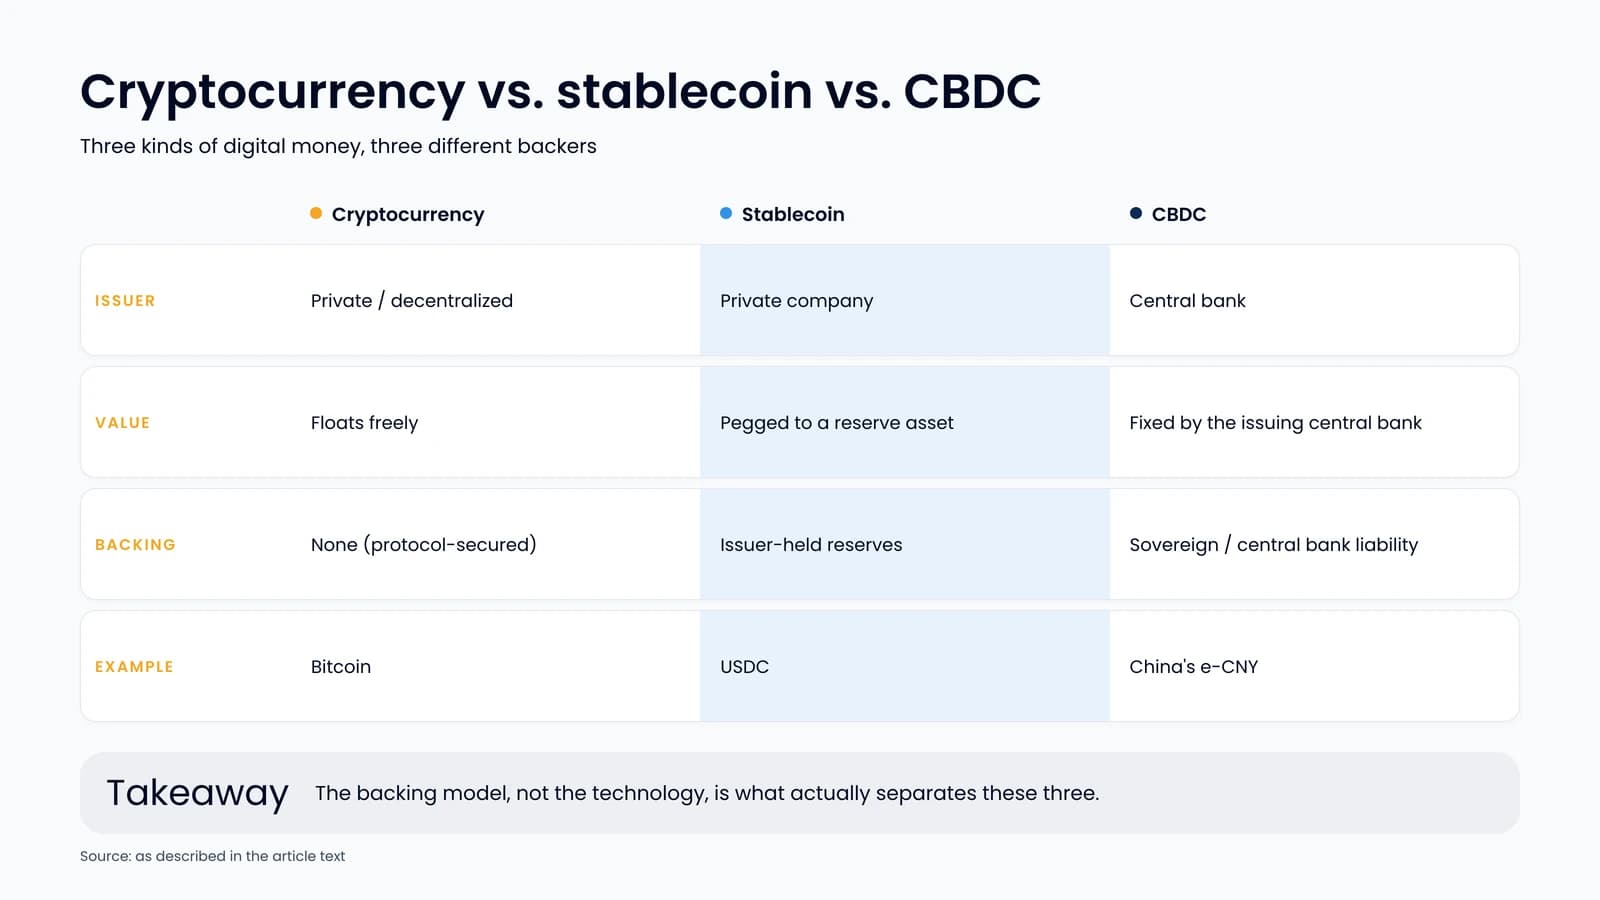
Cryptocurrencies such as Bitcoin are privately issued, not backed by any central authority, and float in price. Stablecoins are also privately issued but pegged to a reference asset, typically the US dollar, and backed by reserves the issuer holds. A CBDC sits apart from both: it is centrally issued, its value is fixed by the issuing central bank rather than pegged by a private reserve manager, and it carries sovereign backing rather than issuer credit risk.
Where CBDCs actually stand in 2026
- United States: ruled out. A January 2025 executive order directed federal agencies to terminate any CBDC development and established a policy of “prohibiting the establishment, issuance, circulation, and use of a CBDC within the jurisdiction of the United States.” The US has instead pursued the private-sector route: the GENIUS Act regulates dollar-backed payment stablecoins rather than creating a Fed-issued digital dollar.
- European Union: still years away from a decision. The ECB moved the digital euro project to its next phase in October 2025 and is targeting readiness for a potential first issuance in 2029, contingent on the EU adopting the necessary legislation during 2026; a merchant pilot is planned for 2027. No launch has been decided.
- China: the largest live retail CBDC. The e-CNY, run by the People's Bank of China, is integrated with Alipay and WeChat Pay and accepted across transport and retail, though it still runs alongside, not in place of, those dominant private payment apps.
- Smaller live projects. The Bahamas' Sand Dollar and Jamaica's JAM-DEX are both live, and Nigeria's eNaira has been running since 2021, though all three have seen adoption well below their central banks' original targets. India's digital rupee remains in pilot.
The practical takeaway for banks: a US CBDC is off the table for the foreseeable future, a euro CBDC is a multi-year-out possibility, and the more immediate competitive pressure in most markets comes from stablecoins and tokenized deposits already live today; see our comparison of stablecoins vs deposit tokens for how banks are responding to that pressure directly.
CBDC design choices
Any central bank building a CBDC has to settle three design questions, regardless of whether it ultimately launches.
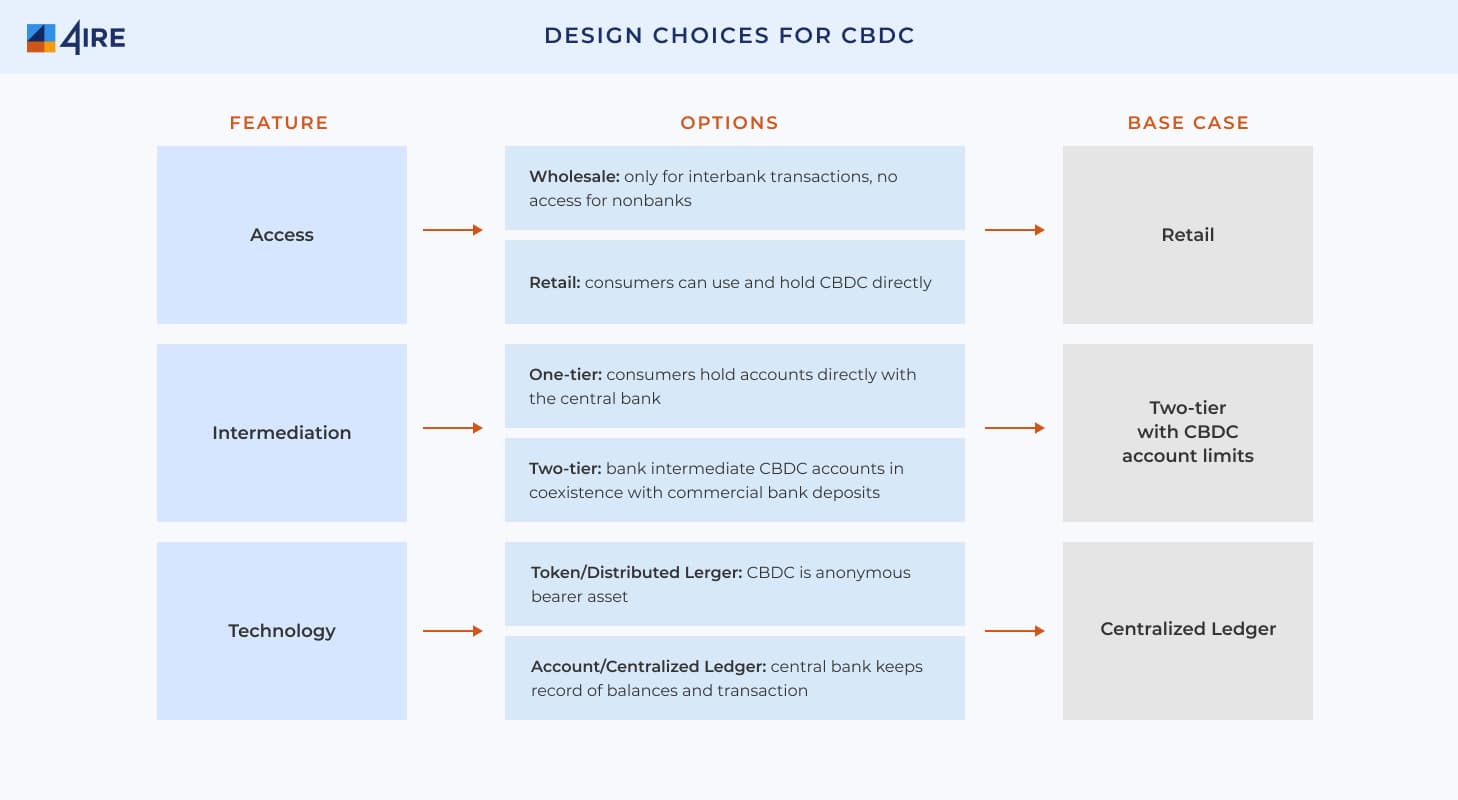
Access and intermediation
A wholesale CBDC is restricted to interbank settlement; a retail CBDC lets consumers hold and use it directly. Within a retail design, a one-tier model has consumers hold accounts directly with the central bank. It is simple, but it dumps KYC/AML, account servicing, and audit workload onto an institution not built for retail banking, and pulls deposits straight out of commercial banks. A two-tier model has commercial banks or licensed non-banks hold and service CBDC accounts while the central bank audits and guarantees the underlying liability, which is the model most active projects have converged on, since it keeps commercial banks in the loop rather than disintermediating them outright.
Technology and privacy trade-offs
A token-based design authenticates the holder of a digital wallet rather than their identity, closer to cash-like anonymity but harder to reconcile with KYC/AML obligations. An account-based design requires identity verification like a bank account, which is safer from a compliance standpoint but gives up the privacy central banks often promise. Most live and piloted projects lean account-based with privacy safeguards layered on top, rather than pure token-based anonymity.
Benefits and drawbacks
- Potential benefits: faster and cheaper wholesale and cross-border settlement, a stable digital option for people wary of volatile crypto assets, and a channel for reaching unbanked populations where mobile penetration outpaces bank branch access.
- Real drawbacks: a retail CBDC risks pulling deposits out of commercial banks, raises data-privacy questions that no design has fully solved, adds a new systemic cyberattack surface, and is genuinely expensive to build and operate, with costs that several abandoned or scaled-back pilots have run into already.
What this means for commercial banks
Whether or not a CBDC ever launches in your market, the underlying pressure is the same: money is moving onto faster, programmable digital rails, and a bank's deposit base and interchange revenue are exposed either way, whether the challenger is a central bank, a stablecoin issuer, or a fintech built on either.
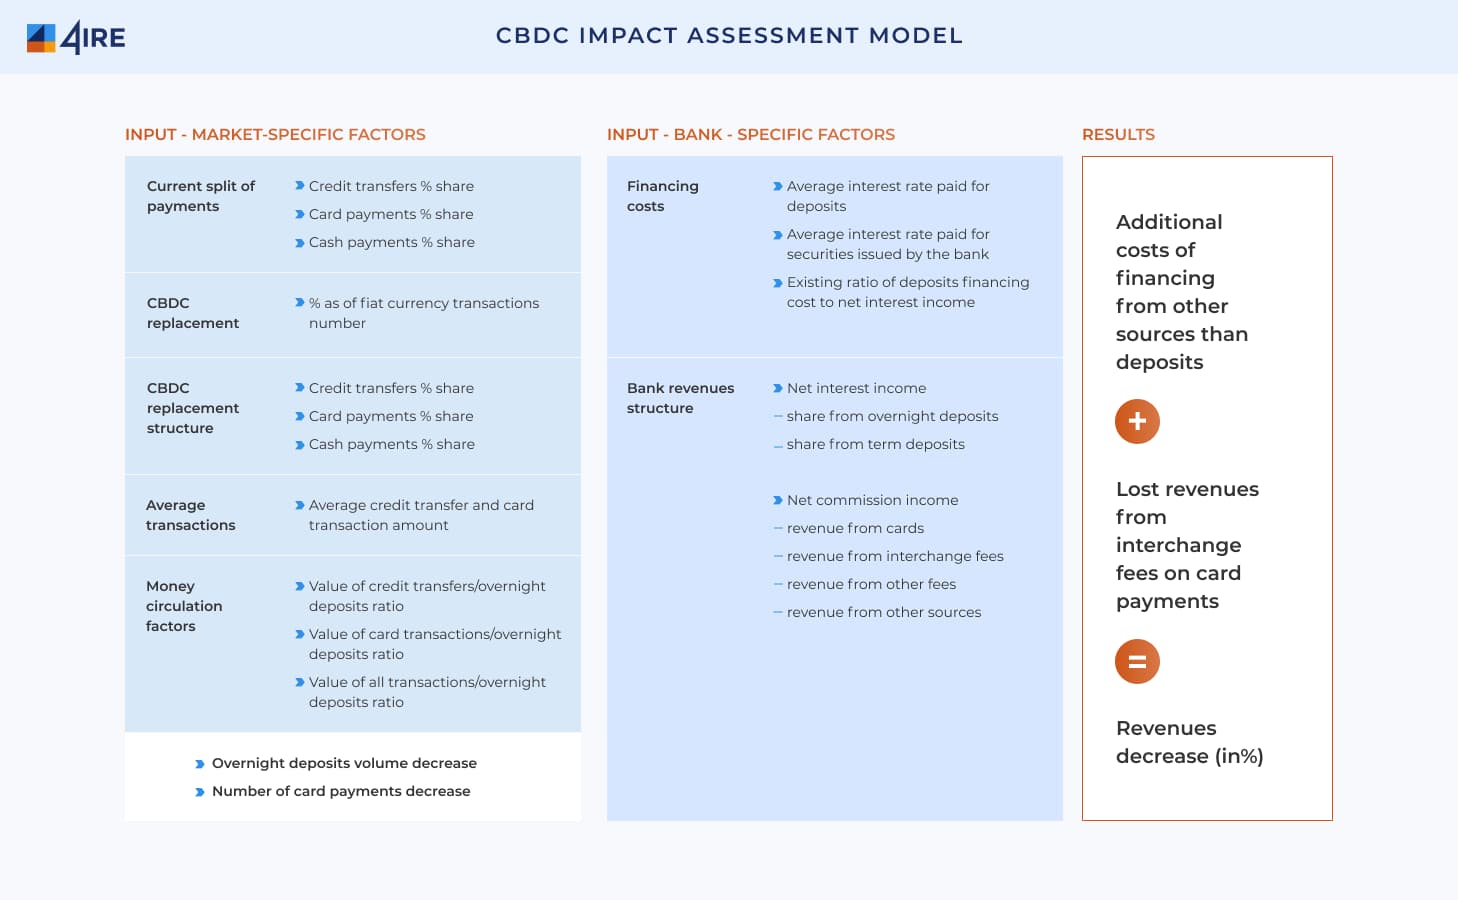
A two-tier CBDC model, where it exists, is actually an opportunity for commercial banks rather than a pure threat: it keeps them as the customer-facing account holder and compliance layer, with the central bank underwriting the liability. The banks that come out ahead, CBDC or not, are the ones modernizing payment and settlement infrastructure now rather than waiting to react; our guide on why banks are adopting crypto modules covers that shift in more depth. 4IRE's financial software development and blockchain consulting teams help banks and fintechs build that infrastructure, whether the near-term priority is a stablecoin integration, a tokenized deposit pilot, or CBDC readiness.
Learn more from us
 Stablecoin news28 Sept 2026
What Are Stablecoins? Types, Regulation and Risks in 2026
What are stablecoins? How fiat-backed, crypto-backed and synthetic stablecoins hold their peg, how they are regulated, and the risks to know.
Vladislav Malynovskyi
 Stablecoin news16 Sept 2026
Stablecoins vs Deposit Tokens: How Banks Enter Blockchain in 2026
Forward-looking banks are actively exploring digital assets as the regulatory framework matures. Learn the nuances of bank-issued assets in this guide.
Olena Petrashchuk
 Fintech news28 Sept 2026
Best Open Banking APIs for Digital Banks: Top 7 Providers
Compare 7 open banking API providers for digital banks: coverage, products and licensing, plus where PSD3, UK and US 1033 rules stand in 2026.
Vladislav Malynovskyi
Ready to Build Digital-Currency Infrastructure?
Whether it's stablecoins, tokenized deposits, or CBDC readiness, 4IRE can scope the build.
FAQ
No. A January 2025 executive order directed federal agencies to stop any CBDC development and established a policy against issuing one. The US has instead regulated private dollar-backed stablecoins through the GENIUS Act rather than building a Fed-issued digital dollar.
A CBDC is issued directly by a central bank and is a direct central bank liability with no issuer credit risk. A stablecoin is issued by a private company and backed by reserves that company holds; its stability depends on that issuer's reserve quality and redemption process, not sovereign backing.
China's e-CNY is the largest live retail CBDC by usage. The Bahamas (Sand Dollar), Jamaica (JAM-DEX), and Nigeria (eNaira) also have live retail CBDCs, though adoption in all three has run below original targets. The EU, UK, and several other jurisdictions are still in pilot or research phases.
Most live and piloted designs use a two-tier model specifically to avoid this: commercial banks continue to hold and service CBDC accounts, with the central bank auditing and guaranteeing the underlying liability, rather than consumers moving their deposits directly to the central bank.