

Trade finance is the set of instruments that lets an exporter ship goods to a buyer it has never met and still get paid: letters of credit, documentary collections, guarantees, receivables and supply chain finance. It is also one of the most paper-heavy corners of banking. A single shipment can involve a bill of lading, invoices, packing lists, certificates of origin and insurance documents, each checked by several parties.
That friction has a real cost. In its survey published in December 2025, the Asian Development Bank estimated the global trade finance gap, the value of requests banks turn down, at $2.5 trillion, the same level as in 2023. Blockchain was supposed to fix much of this. Some of that promise held up; a lot of it did not. This article looks at what the technology actually does well in trade finance in 2026, what failed, and where it makes sense to build.
How Trade Finance Works
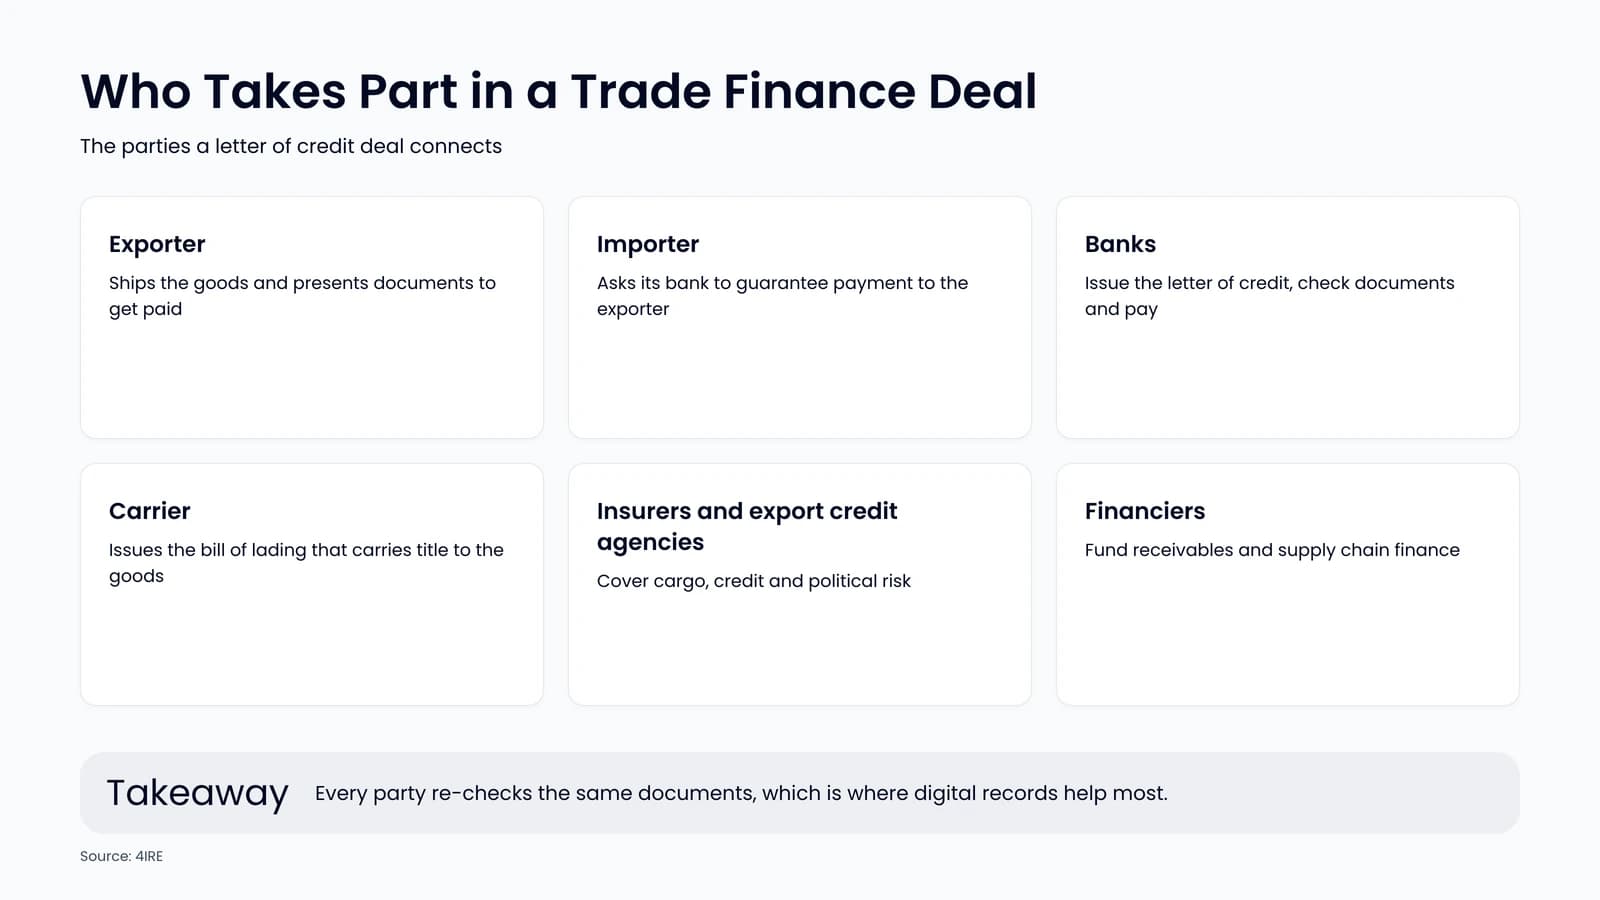
In a classic letter of credit (LC) deal, the importer's bank promises to pay the exporter once the exporter presents documents that match the LC terms, above all the bill of lading that proves the goods were shipped. The exporter's bank checks the documents and forwards them; the issuing bank checks them again and pays. The bank carries the payment risk, and the documents carry title to the goods.
The weak points are well known:
- Paper originals. Title documents such as bills of lading have to be physically handed over, so documents can arrive later than the cargo.
- Manual checking. Every bank in the chain re-checks the same documents against the same terms.
- Fraud and double financing. The same invoice or warehouse receipt can be pledged to several lenders, because no lender sees what the others have financed.
- Limited access for SMEs. High processing cost per deal makes small tickets unattractive for banks.
What Blockchain Promised and What Happened
A shared ledger looks like a natural answer: every party sees one version of the deal, documents are hashed so nobody can alter them, smart contracts release payment when conditions are met, and a pledged asset cannot be financed twice. Between 2017 and 2020, banks formed several consortia to build exactly that.
Most of them are gone or shrank to a fraction of their plans. we.trade, backed by a group of European banks, shut down in 2022 after failing to raise new funding. The holding company of the Marco Polo network entered insolvency in Ireland in February 2023. Maersk and IBM announced in November 2022 that they would take the TradeLens shipping platform offline by the end of the first quarter of 2023, saying the full global industry collaboration it needed had not been achieved. Contour, the letter of credit network backed by major trade banks, announced it would shut down at the end of November 2023 after its bank shareholders declined to fund it further; a fintech buyer revived it in 2024 in heavily restructured form, and XDC Ventures acquired it in October 2025 with only some clients still live on the platform.
The lesson is not that the technology failed. The networks did: each needed every bank, carrier and corporate on the same platform before it became useful, and none reached that scale. Paper also kept its legal advantage. In most countries, only a physical document could legally carry title, so a digital copy on a ledger did not change who owned the cargo.
What Changed: Laws and Standards Caught Up
Since then, the missing legal and standards layer has started to fall into place, and it is platform-neutral:
- Electronic transferable records laws. The UNCITRAL Model Law on Electronic Transferable Records (MLETR), adopted in 2017, lets an electronic record do what a paper bill of lading or bill of exchange does. UNCITRAL now lists legislation based on or influenced by it in 13 jurisdictions, including Singapore, the United Kingdom, France, Bahrain, Abu Dhabi Global Market and, for bills of lading only, China.
- The UK Electronic Trade Documents Act 2023. It received Royal Assent on 20 July 2023 and came into force two months later. It names bills of exchange, promissory notes, bills of lading, warehouse receipts and cargo insurance certificates among the documents that can now exist in electronic form.
- Electronic bills of lading. The CEOs of all member carriers of the Digital Container Shipping Association (DCSA) have committed to issue 50% of their bills of lading electronically within five years and 100% by 2030, on common DCSA standards.
These changes matter more than any single platform. A trade finance product built today can hold a legally valid electronic title document, not just a copy of a paper one.
Blockchain Use Cases in Trade Finance That Still Make Sense
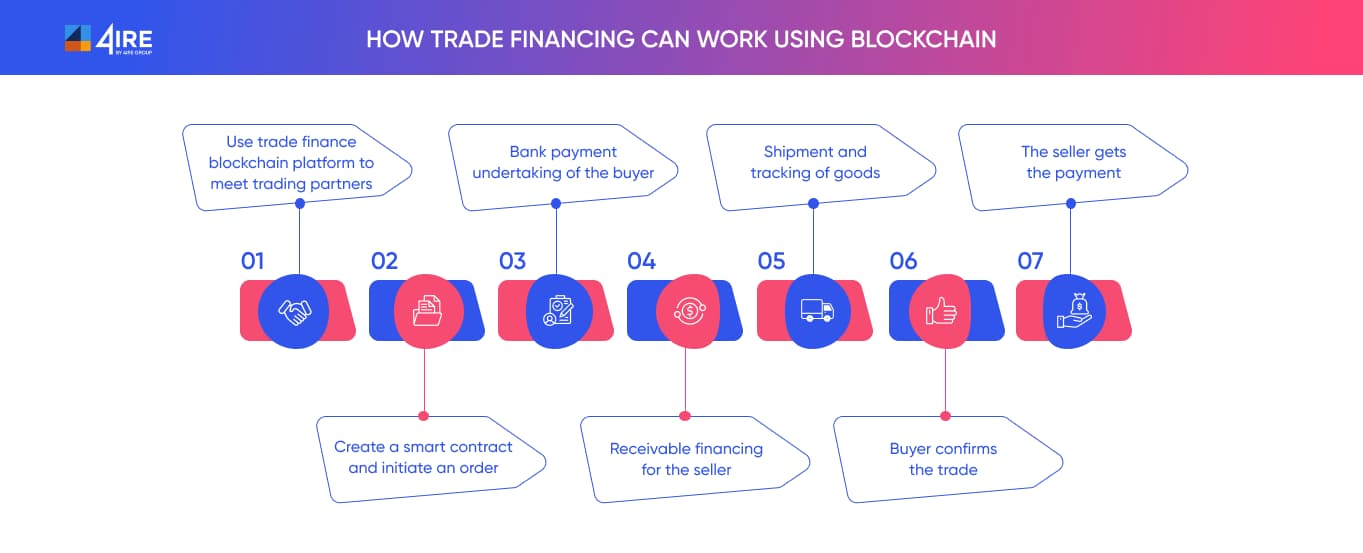
With the legal base in place, blockchain works best where it solves a specific problem between parties that do not share a system:
- Digital title and eBL registries. A ledger is one way to prove who controls an electronic transferable record at any moment, which is exactly what MLETR-style laws require of a "reliable system".
- Double-financing checks. Lenders can register a hash of each invoice or receivable in a shared registry and see whether it has already been financed, without revealing the underlying document.
- Receivables and supply chain finance. Invoices and payment undertakings can be issued as on-chain instruments, split and sold to investors. This overlaps with real-world asset tokenization, where trade receivables are one of the asset classes being brought on-chain.
- Programmable settlement. Payment can be released automatically when an eBL is transferred or a delivery is confirmed, in stablecoins or bank deposit tokens; our comparison of stablecoins vs deposit tokens covers which fits a regulated trade flow.
- Shared KYC and document trails. Verified counterparty data and document hashes can be reused across deals instead of being re-collected each time.
Supply chain data sits right next to this. Shipment events, certificates of origin and inspection results are the evidence that trade finance documents rely on, which is why the two areas keep converging; see our overview of blockchain use cases in supply chain management.
Choosing the Right Architecture
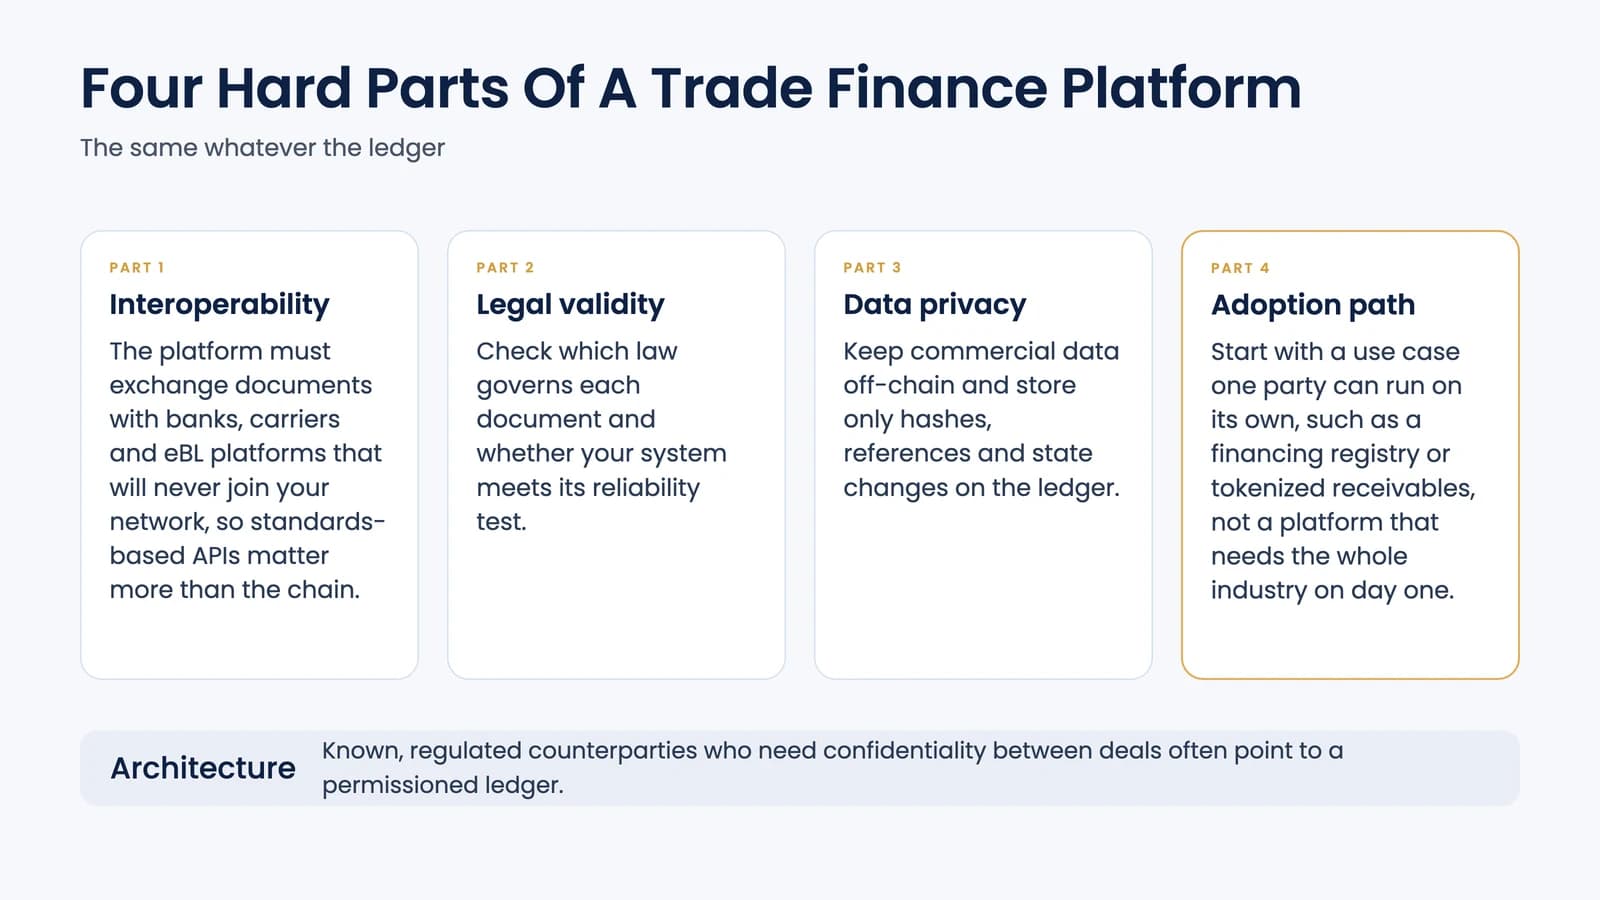
Trade finance participants are known, regulated counterparties who need confidentiality between deals, so a permissioned ledger is often the default. Corda was designed for exactly this kind of point-to-point sharing between banks; our case on why we chose Corda for a client project explains the trade-offs. Public chains become relevant when you want to sell tokenized receivables to outside investors or settle in widely held stablecoins.
Whatever the ledger, the hard parts are the same:
- Interoperability. The platform must exchange documents with banks, carriers and eBL platforms that will never join your network, so standards-based APIs matter more than the chain itself.
- Legal validity. Check which law governs each document and whether your system meets its reliability test.
- Data privacy. Keep commercial data off-chain and store only hashes, references and state changes on the ledger.
- Adoption path. Start with a use case one party can run on its own, such as a financing registry or tokenized receivables, rather than a platform that needs the whole industry on day one.
How 4IRE Builds Trade Finance Platforms
4IRE built Tradeleaf, a blockchain-based trade finance platform for a UAE-based client, built to move the client's existing trade finance operations online around deal, lending and trade finance marketplaces for traders and financiers. You can see this and related projects on our trade finance industry page.
If you are deciding whether a ledger belongs in your trade finance product at all, our blockchain consulting team can help you map the documents, parties and laws involved before you commit to a platform. The same consortium lessons apply in other industries too, including insurance.
Learn more from us
 Blockchain news28 Sept 2026
Real World Asset Tokenization in 2026: A Practical Guide to RWA
Real world asset tokenization explained: asset classes, how the stack works, 2026 RWA market data, US, EU, Singapore and UAE rules, and how to launch.
Olena Petrashchuk
 Stablecoin news16 Sept 2026
Stablecoins vs Deposit Tokens: How Banks Enter Blockchain in 2026
Forward-looking banks are actively exploring digital assets as the regulatory framework matures. Learn the nuances of bank-issued assets in this guide.
Olena Petrashchuk
 Blockchain Use Cases21 Apr 2026
Blockchain Use Cases in Supply Chain Management
Where blockchain adds value in supply chains: traceability, recalls, digital documents, procurement and payments, plus the lessons from failed networks.
Vladislav Malynovskyi
Building a Trade Finance Platform?
We can help you scope the ledger, document and payment layers of a digital trade finance product and build it end to end.
FAQs
It gives parties that do not share a system one tamper-evident record of documents, ownership and payment status. The clearest benefits today are digital title for electronic trade documents, registries that stop the same invoice being financed twice, and automated settlement once agreed conditions are met.
Smart contracts can hold the agreed terms of a deal and release payment, transfer a financed receivable or update a document status when a defined event happens, such as the transfer of an electronic bill of lading. Banks still carry credit risk and compliance duties; the smart contract automates the steps between them.
They needed most banks, carriers and corporates to join one platform before it became useful, and they ran out of funding before that happened. Contour, for example, announced its shutdown for November 2023 after its bank shareholders stopped funding it, and survives only as a much smaller platform under new owners. The technology worked; the network economics did not.
In a growing number of places, yes. The UK Electronic Trade Documents Act 2023 and other laws based on the UNCITRAL Model Law on Electronic Transferable Records give electronic trade documents the same effect as paper ones, provided they are held in a reliable system. Check the governing law for each document.
Start with one problem you control, such as a financing registry, tokenized receivables or electronic document exchange with a few partners, and connect to existing eBL and banking standards rather than building a closed network.