

Until recently, people could borrow money only from centralized financial institutions such as banks or accredited lenders, which lean on retrospective credit scores. That shuts out anyone without a prior credit history. DeFi lending offers a different model: you don't prove creditworthiness, you prove collateral.
Lending protocols have grown into a real part of the crypto economy. As of late September 2026, lending protocols held about $55 billion in total value locked, according to DefiLlama. This guide, from 4IRE's DeFi development team, explains how DeFi lending actually works, its benefits and risks, and the protocols that lead the sector today. If you're weighing whether to build one, see our companion guide on building a DeFi lending and borrowing platform.
DeFi Lending vs. Traditional Lending
People have lent and borrowed money for millennia, first as physical cash, then through banks crediting digital accounts. DeFi lending is the latest step: it gives unbanked and underbanked users access to credit without a bank relationship or a credit history.
Traditional lending
A traditional bank loan is priced from the principal, the interest rate, and the number of payment periods. For example: a $10,000 loan at a 25% interest rate adds $2,500 in interest, spread across the loan's term: over 20 months, that's $500 principal plus $125 interest each month. Loans without collateral usually carry a materially higher rate than secured ones.
DeFi lending
A DeFi loan works differently: the borrower posts collateral worth more than the loan itself, with the exact ratio set by the protocol. Sky (formerly MakerDAO) requires collateralization well above 100% on its lending vaults, varying by asset; Aave's loan-to-value ratios vary by asset too, typically higher for stablecoin collateral than for a volatile asset like ETH. There's usually no fixed loan term. Interest accrues daily, and the borrower can repay and reclaim their collateral whenever they choose, but must add funds or face liquidation if the collateral's value drops too far.
How Do DeFi Loans Work?
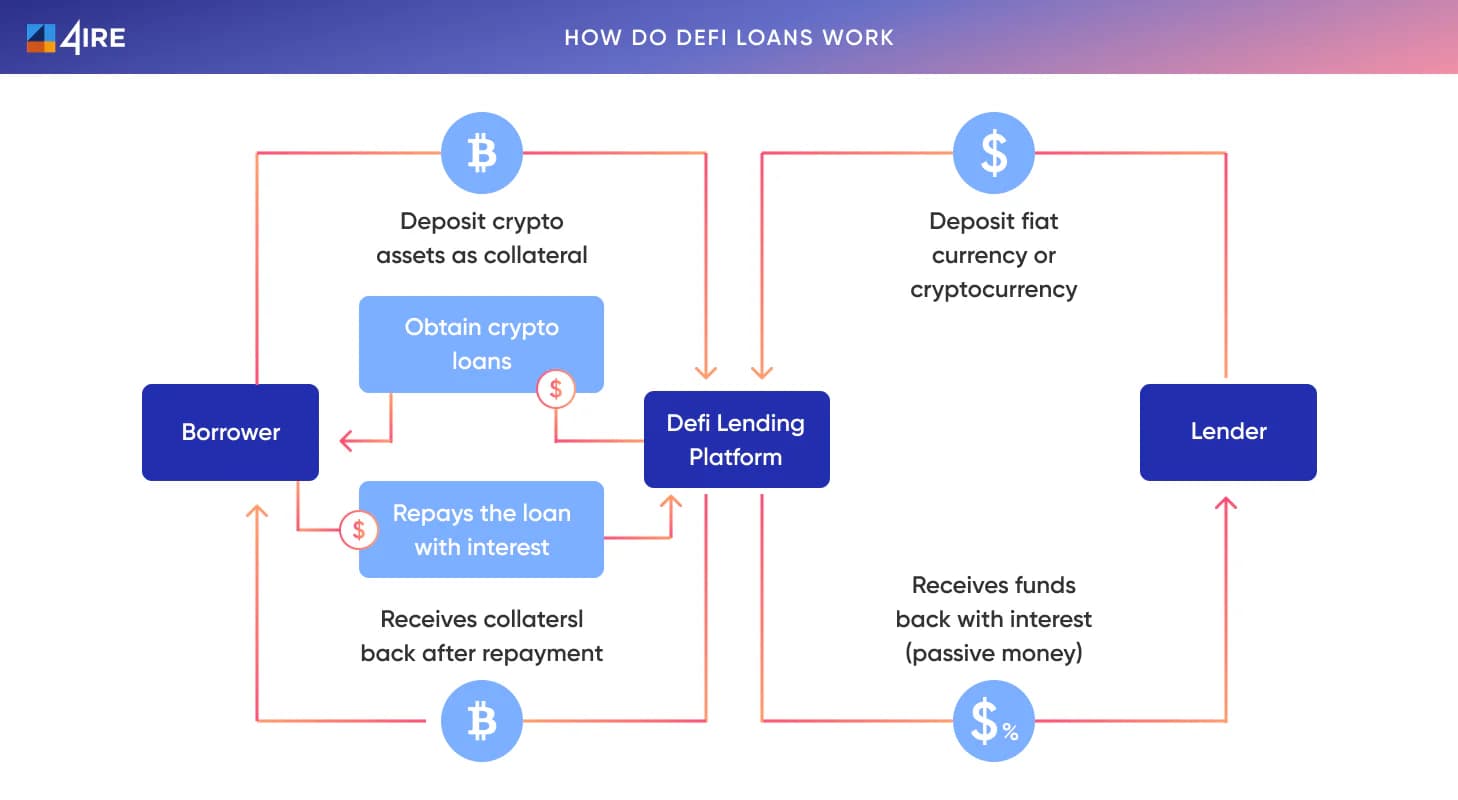
The mechanics, step by step:
- A lender with idle crypto deposits it into a DeFi lending pool.
- The deposit is locked and starts earning a variable or fixed annual percentage yield (APY), accrued daily.
- A borrower requests a loan, specifying the amount and, on some platforms, a preferred duration.
- The protocol calculates the required collateral based on the requested loan and the asset's risk parameters.
- The borrower posts the collateral and receives the loan; if the collateral's value falls, they must add more or risk automatic liquidation.
- Once the borrower repays the principal plus accrued interest in full, the protocol releases their collateral back to them.
Because protocols don't check identity or credit history, the loan is only as safe as the collateral behind it, which is why almost every DeFi loan is overcollateralized: to borrow $1,000 of stablecoins, a borrower typically deposits crypto worth noticeably more than $1,000.
What makes it different
- No intermediary oversees or approves individual lending and borrowing decisions.
- Anyone holding spare crypto can become a lender and earn yield.
- Loans require no identity check, only collateral.
- There's typically no fixed term, so interest scales with how long the loan is actually outstanding.
- Over-collateralization, not a credit score, is what protects lenders.
Benefits of DeFi Lending
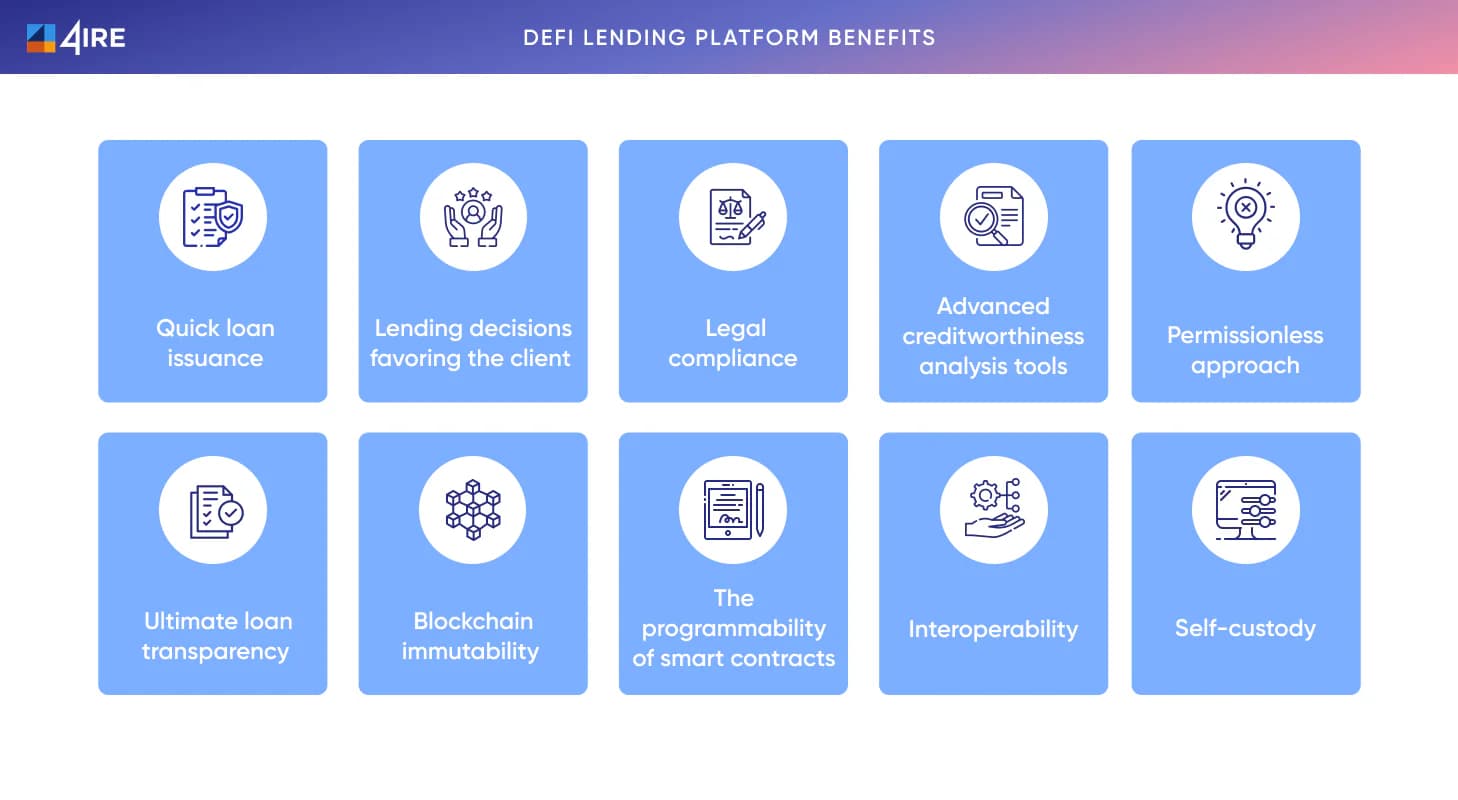
- Speed. Smart contracts replace manual underwriting, so a loan can go from application to funded in minutes rather than days.
- Rules-based decisions. If you have sufficient collateral, the protocol issues the loan; there's no opaque internal scoring model to satisfy, unlike a bank's proprietary credit scoring process.
- On-chain compliance trail. Even though identities aren't verified, every wallet's transaction history is public and traceable, which supports AML monitoring at the platform level.
- Adaptive rates. Interest rates on most protocols adjust automatically to pool supply and demand rather than being reset manually.
- Permissionless access. Anyone with a wallet and collateral can borrow or lend, regardless of location or financial history.
- Transparency and immutability. Loan terms live in an auditable smart contract, and settled transactions can't be altered after the fact.
- Self-custody. Lenders and borrowers keep control of their own keys throughout, with the added responsibility that implies.
How DeFi Lending Fits Into Financial Services
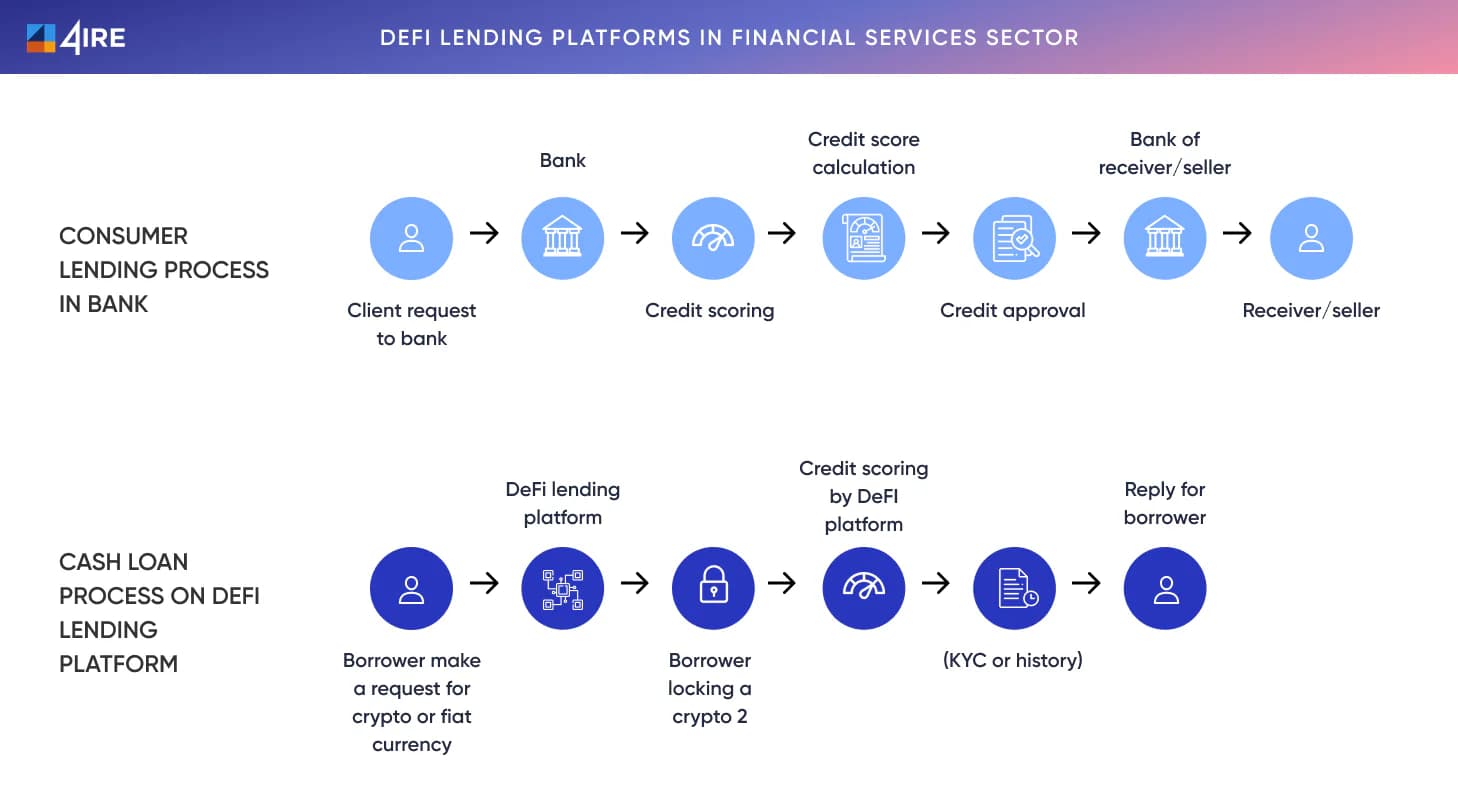
DeFi lending pulls some activity away from traditional banks, but it also extends credit to people a bank wouldn't serve, and gives crypto holders a way to put idle assets to work instead of leaving them dormant in a wallet. For product teams, that means three practical use cases: cheaper working-capital loans for underbanked users, a yield venue for long-term holders, and a building block other DeFi products (from stablecoin issuers to DEXs) can plug into for treasury management.
Risks to Understand
- Liquidation risk. If collateral drops in value faster than a borrower can react, the protocol liquidates it automatically, often with a penalty on top of the loss.
- Smart contract risk. A bug in the lending contract or its price oracle can drain a pool regardless of how well-collateralized individual loans are; an independent smart contract audit is the baseline defense, not a guarantee.
- Interest rate volatility. Rates that float with pool utilization can swing sharply during periods of high demand, changing the economics of an open loan or deposit with no notice.
- Oracle and market risk. Thin markets or a manipulated price feed can trigger liquidations that wouldn't happen on a deeper, better-priced market.
Popular DeFi Lending Protocols
A handful of protocols account for most of the sector's activity. See our roundup of top DeFi lending platforms for a closer comparison. As of late September 2026, per DefiLlama, Aave leads with about $19 billion in total value locked, followed by Morpho at about $11 billion, SparkLend (part of Sky, formerly MakerDAO) at about $5.7 billion, and Compound at about $1.6 billion, together most of the sector's roughly $55 billion in TVL.
Sky, the rebranded MakerDAO, pioneered the overcollateralized-vault model behind its USDS stablecoin (formerly DAI) and now also operates SparkLend as a dedicated lending market. Aave is a non-custodial money market where lenders deposit into shared pools and receive interest-bearing aTokens; its rates float with each asset's utilization. Compound popularized the same pooled-liquidity model on Ethereum and still runs an open, permissionless money market across several assets. Morpho takes a different approach, matching lenders and borrowers more directly on top of, or alongside, pools like Aave's and Compound's to improve rates for both sides.
How Much Does It Cost to Build a DeFi Lending Platform?
Cost depends on your specifications, your development partner's location, and feature complexity. As a rough range, 4IRE estimates a DeFi lending platform costs $70,000 to $300,000+, covering:
- Core lending and borrowing functionality
- UX/UI design
- Smart contract design and tokenomics
- QA testing and an independent smart contract audit
- Pre-launch marketing
- Post-launch maintenance
Conclusion
DeFi lending gives crypto holders a genuine, if not risk-free, way to earn yield, and gives borrowers a path to credit that doesn't depend on a traditional credit history. If you're evaluating whether to use an existing protocol or build your own DeFi lending and borrowing platform, weigh the volatility risk on both sides (for lenders and for borrowers whose collateral can be liquidated) against the returns and access it enables.
Learn more from us
 Fintech news28 Sept 2026
How to Build a DeFi Lending and Borrowing Platform
How DeFi lending works, how Aave, Compound and Morpho differ, and how to build a lending and borrowing platform: risk design, contracts and security.
Olena Petrashchuk
 Data science29 Sept 2026
Top 5 DeFi Lending Platforms in 2026
Aave, Morpho, SparkLend, Compound and Venus: the top DeFi lending platforms by TVL in 2026, how crypto lending works, and its risks.
Olena Petrashchuk
 DeFi28 Sept 2026
How to Build a DEX Like Uniswap: A Practical Guide
How to build a DEX like Uniswap: how the protocol works, what v2, v3 and v4 licenses allow, hooks, build steps, security, liquidity and cost.
Olena Petrashchuk
Build Your DeFi Lending Platform
Weighing over-collateralization models, chains and audit scope? Our team will help you scope a lending platform that fits your budget and risk model.
FAQ
DeFi lending is a segment of decentralized finance where crypto holders lend their assets to a smart contract-based pool and borrowers draw against it by posting collateral, without a bank or credit check involved. Interest accrues to lenders continuously; borrowers repay principal plus interest to reclaim their collateral.
It's protected by smart contracts rather than by a bank's balance sheet, which shifts the risk profile rather than removing it. Borrowers face liquidation if their collateral's value drops too far; lenders face smart contract risk and, on some platforms, the risk that a large share of borrowers default at once. Sticking to established, audited protocols reduces but does not eliminate these risks.
Connect a wallet to the protocol, choose the asset and amount to borrow, and deposit collateral valued above the required ratio for that asset. The loan is disbursed once the collateral is locked, and it stays open — with interest accruing — until you repay it or your collateral is liquidated.
If you're comfortable with the platform's smart contract risk and the volatility of the assets involved, lending idle crypto can generate a steady yield without active trading. Spreading deposits across more than one established protocol, rather than concentrating in one, is a common way to manage that risk.