


A few years ago, most talk about blockchain in business was about pilots. In 2026 the picture is clearer. Some uses run at real scale, such as stablecoin payments, tokenized funds and bank settlement networks. Others failed without fanfare, including several industry-wide consortia. The difference usually comes down to one question: does the business problem involve several parties who need to share a record that none of them fully controls?
This guide walks through the blockchain use cases in business that hold up today, with real examples, and ends with a simple test for deciding whether your own idea needs a ledger at all.
When Blockchain Makes Sense for a Business
A blockchain is a shared database that several organisations can write to, where records are signed, ordered and hard to change after the fact, and where rules can run as code in smart contracts. It earns its cost when most of these are true:
- Several parties need the same data, and none of them wants another to own it.
- Trust is expensive today, because of reconciliation, audits, intermediaries or fraud.
- Something of value moves between parties: money, title, a certificate, a claim.
- A permanent audit trail matters to regulators, partners or customers.
If one company owns every step of the process, a conventional database is usually cheaper and simpler.
Blockchain Use Cases in Banking and Payments
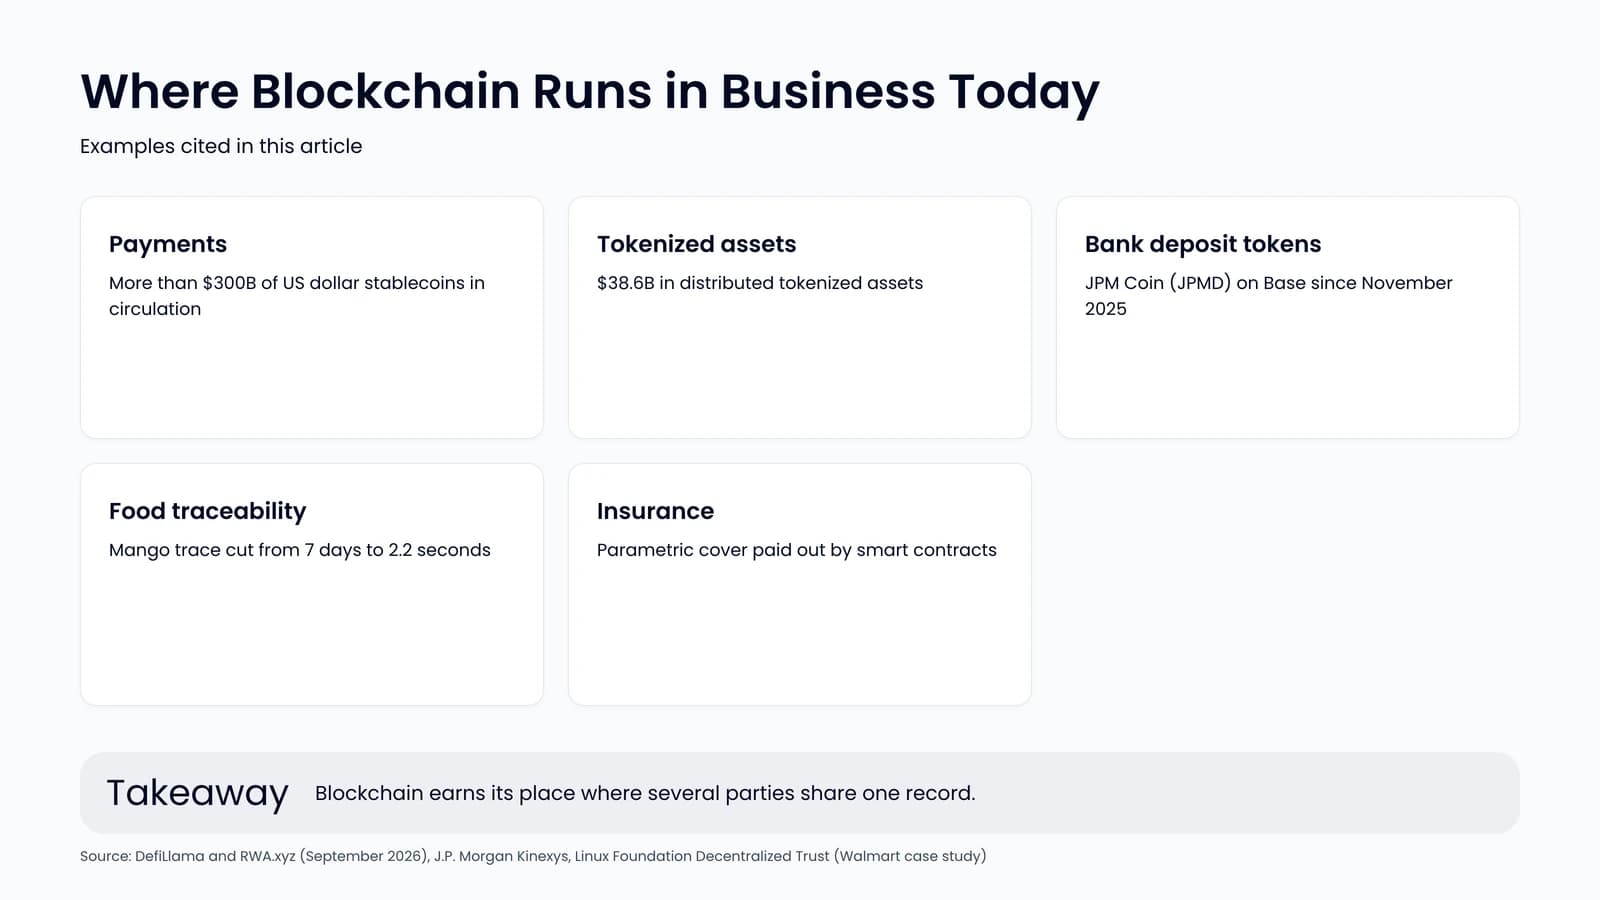
Payments are the largest use case by value. As of September 2026, more than $300 billion of US dollar stablecoins were in circulation, according to DefiLlama. Businesses use them to pay suppliers across borders, settle with exchanges and hold digital dollars outside banking hours. Our stablecoins guide explains how they work and how MiCA and the US GENIUS Act regulate them.
Banks are building their own versions. In November 2025, JPMorgan's Kinexys made JPM Coin (JPMD), a USD deposit token, available to institutional clients on the Base blockchain. Smaller banks are adding custody, trading and stablecoin services through ready-made modules, a trend we cover in why traditional banks adopt crypto modules.
Compliance is part of the same stack. Blockchain analytics tools screen wallets and trace transaction flows for anti-money laundering checks, and smart contracts can restrict transfers to verified wallets, which is how many regulated tokens enforce KYC rules.
Tokenization of Real-World Assets
Tokenization records ownership of an off-chain asset, such as a Treasury bill, a fund share, a loan, real estate or gold, as a token that can settle in minutes and move between approved wallets. As of 28 September 2026, RWA.xyz tracked $38.6 billion in distributed tokenized assets. Fund managers use tokenization to reach new investors and to make fund shares usable as collateral. Our guide to real-world asset tokenization covers the market, the legal structures and what it takes to launch.
Trade Finance
Trade finance is where blockchain's early hopes met reality. Bank-led networks for letters of credit and trade documents, including we.trade, Marco Polo and Contour, shut down or collapsed between 2022 and 2023 because too few banks and corporates joined; Contour survives only as a much smaller platform under new owners. What moved forward instead were laws that give electronic trade documents legal effect and industry standards for electronic bills of lading. Blockchain still fits narrower jobs such as registries that stop the same invoice from being financed twice, and tokenized receivables. Read more in our article on blockchain in trade finance.
Supply Chain and Food Traceability
In a supply chain, each hand-off between companies is a place where data gets lost or altered. A shared ledger gives every party the same history of a product. In Walmart's pilot with IBM on Hyperledger Fabric, tracing the origin of a package of mangoes took 7 days with the old process and 2.2 seconds on the blockchain system. Maersk and IBM's TradeLens, by contrast, closed in 2023 because it could not bring the whole shipping industry onto one platform. See blockchain use cases in supply chain management and, for food safety rules and restaurants, blockchain in the food industry.
Insurance
Parametric insurance is the most natural fit: a smart contract pays a fixed amount when an oracle reports a defined event, such as an earthquake above a set magnitude, with no claims assessment. Shared registries also help insurers spot duplicate claims and keep one record of premiums and claims with their reinsurers. The industry's best-known consortium, B3i, filed for insolvency in 2022, so the projects that work now start with a single product rather than a market-wide platform. More in blockchain in the insurance industry.
Other Industries
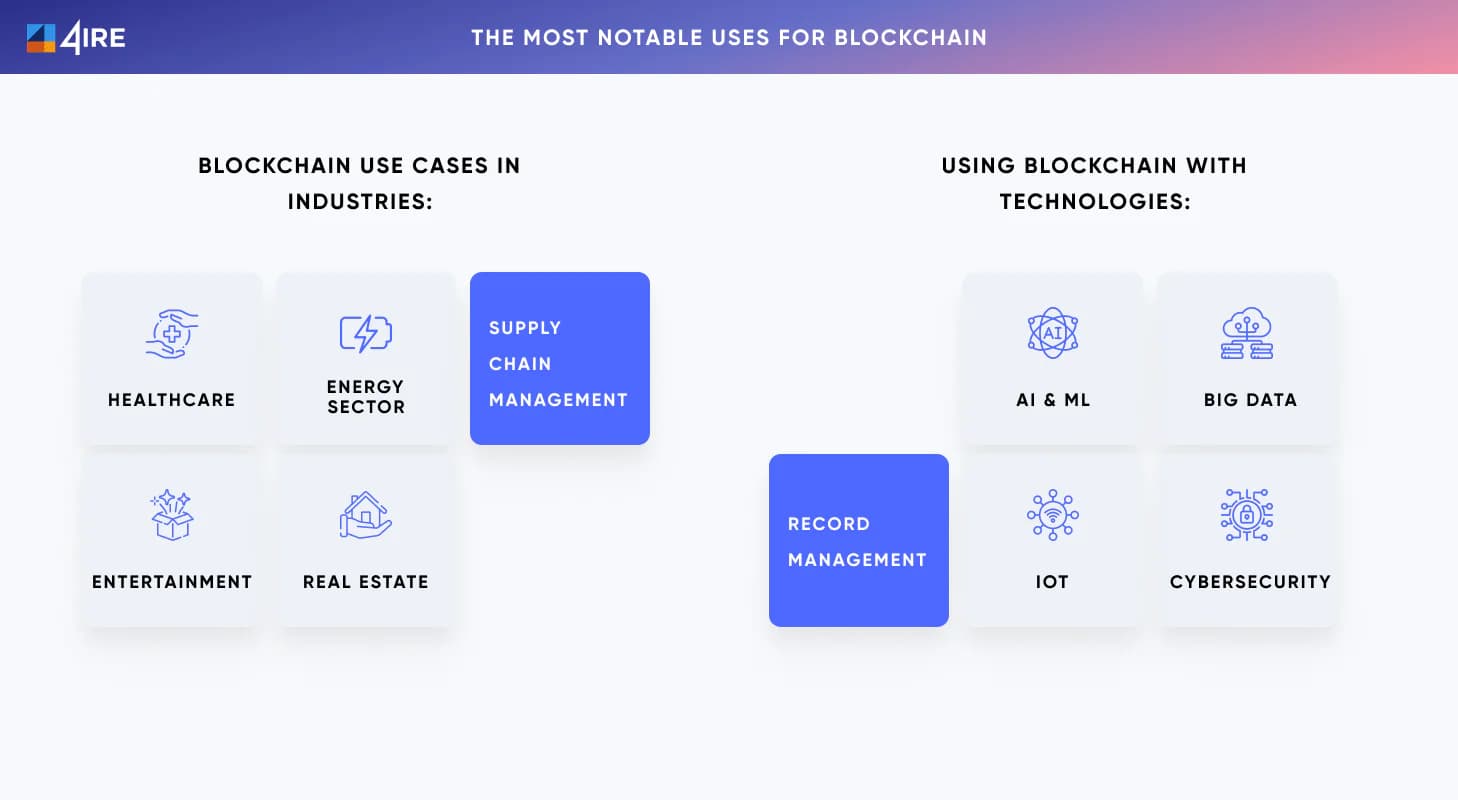
- Energy and carbon. Registries for renewable energy certificates and carbon credits use ledgers to stop one unit from being counted or sold twice.
- Healthcare. Hospitals and research networks use ledgers to log who accessed which records and with what consent, while the data itself stays in secure systems.
- Real estate. Tokenized property funds and fractional ownership let investors buy smaller stakes; title registries are slower to change because land law is local.
- Media and gaming. NFTs and on-chain items give players and creators ownership of digital goods and a record of royalties.
Blockchain with AI and IoT
Blockchain works best alongside other technologies. IoT sensors feed temperature, location or energy readings into the ledger at the source, which reduces the risk of manual entry errors. AI agents are starting to hold wallets and pay for services, and a ledger gives their actions an audit trail. In both cases, blockchain is the shared record, not the intelligence.
What Separates Live Systems from Failed Pilots
Looking across these industries, the projects that reached production share a few traits:
- One owner with a clear business case. A bank issuing a deposit token or a fund manager tokenizing a fund can launch without waiting for competitors to agree.
- Value that moves, not just data. Payments, fund shares and tokenized collateral give users a direct reason to be on-chain; shared data alone rarely does.
- Standards and law in place. Stablecoin rules, tokenized-securities guidance and electronic trade document laws gave these products a legal footing.
The failures mirror this. Most were industry-wide platforms that needed dozens of competitors to join, carried only data, and ran ahead of the law that would have made their records legally binding.
How to Decide Whether Your Use Case Needs Blockchain
Before you build, answer four questions:
- Who writes the data, and would they accept one of the others running the database?
- What does distrust cost today, in hours, fees, fraud or delays?
- Which regulation applies to the data or the asset, and does it recognise electronic records or tokens?
- Can you launch with a small group of partners, or does the idea only work once the whole industry joins?
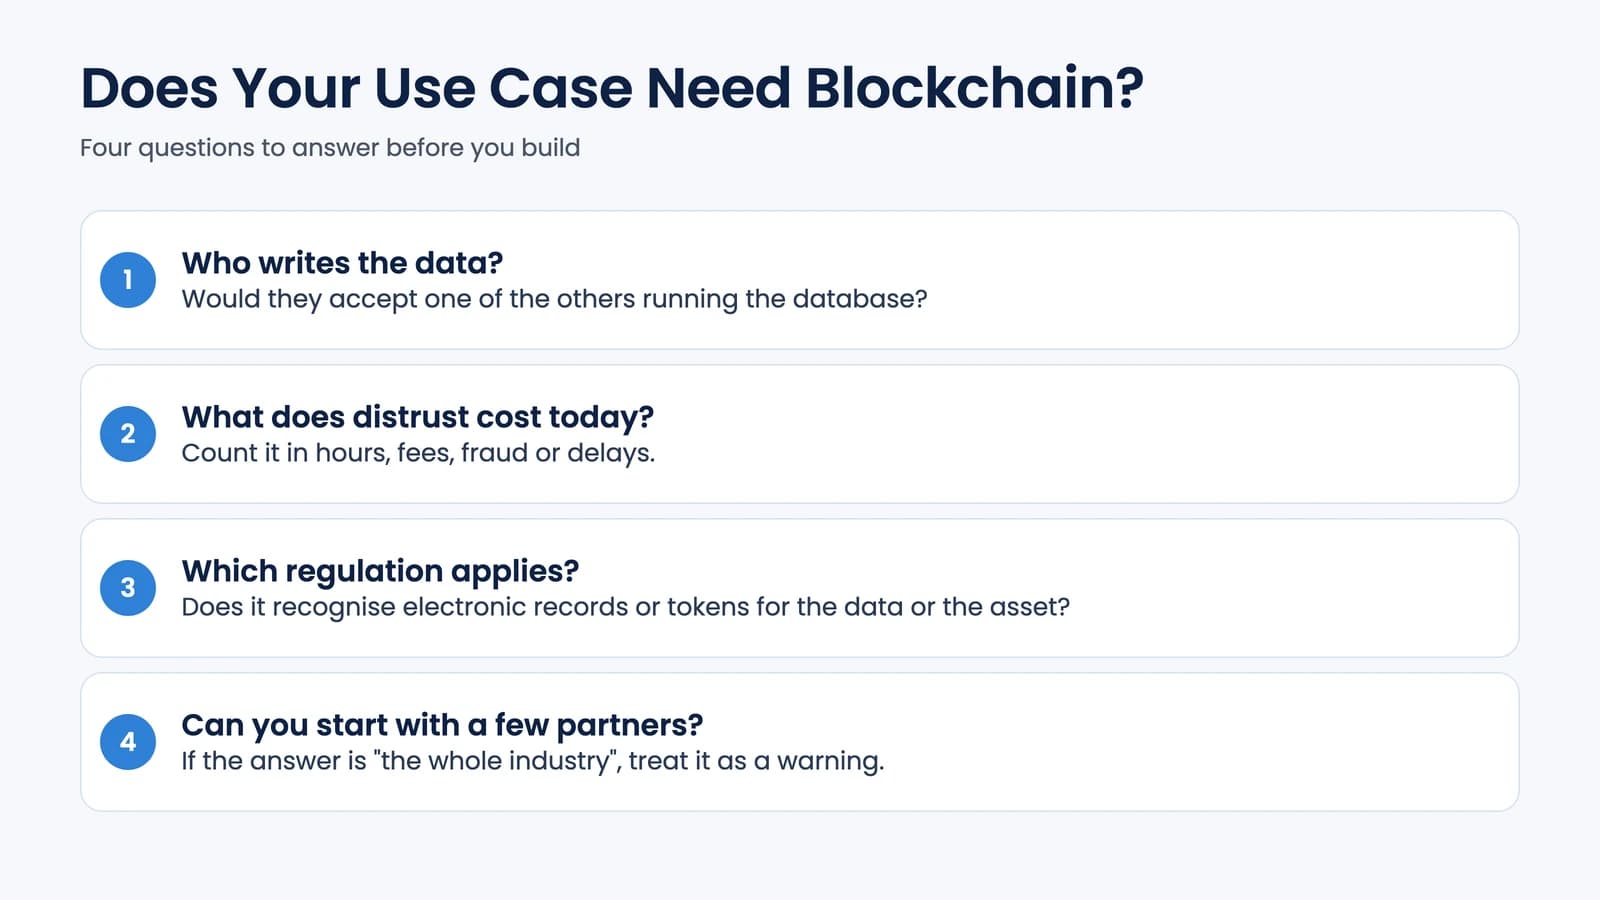
If the last answer is "the whole industry", treat that as a warning: that is the pattern behind most failed consortia.
How 4IRE Can Help
4IRE has built blockchain products since 2010, from payments and tokenization platforms to trade finance and insurance marketplaces. Our blockchain consulting team can help you test a use case against these questions and turn it into a scoped product.
Learn more from us
 Blockchain news28 Sept 2026
Real World Asset Tokenization in 2026: A Practical Guide to RWA
Real world asset tokenization explained: asset classes, how the stack works, 2026 RWA market data, US, EU, Singapore and UAE rules, and how to launch.
Olena Petrashchuk
 Stablecoin news28 Sept 2026
What Are Stablecoins? Types, Regulation and Risks in 2026
What are stablecoins? How fiat-backed, crypto-backed and synthetic stablecoins hold their peg, how they are regulated, and the risks to know.
Vladislav Malynovskyi
 01 Oct 2026
How to Choose a Distributed Ledger Technology
What DLT is, how it differs from blockchain, and how to decide between a public chain and a permissioned ledger for your project.
Vladislav Malynovskyi
Planning a Blockchain Use Case?
Tell us about the process you want to improve. We will help you check whether a ledger fits and scope the build.
FAQ
By value, payments and settlement: US dollar stablecoins, bank deposit tokens and tokenized funds. Outside finance, traceability in supply chains and food is the most widely documented use.
Yes. Smart contracts can hold funds in escrow, match buyers and sellers and settle trades without a central operator holding customer assets. Marketplaces for digital assets, tokenized securities and insurance policies already work this way, though regulated assets still need licensed operators.
Records are signed by their authors and linked, so any later change is visible, and the data is replicated across several nodes, so there is no single point of failure. Blockchain does not make the data confidential by itself; sensitive data should stay off-chain, with only hashes or references on the ledger.
Yes. Businesses can choose a public or permissioned network, decide who can run nodes and read data, and write smart contracts for their own rules, from supplier payments to parametric insurance payouts.