

We first asked this question in 2020, when DeFi meant yield-farming tokens with names nobody could explain and total value locked was a number that doubled every few months on momentum alone. Six years on, the honest answer has changed: DeFi is no longer a buzzword, but it is also not the thing 2020 imagined. It settled into a narrower, more regulated, more institutional shape than the early hype suggested, and it carries real, well-documented risks alongside real adoption.
What DeFi actually is
Decentralized finance replaces a bank, broker or exchange's internal ledger with a public smart contract that anyone can read, audit and transact against directly. Lending, trading, derivatives and asset management each have a DeFi version built this way: a protocol holds funds in a contract rather than a company's balance sheet, and code, not a back office, decides who can borrow, trade or redeem.
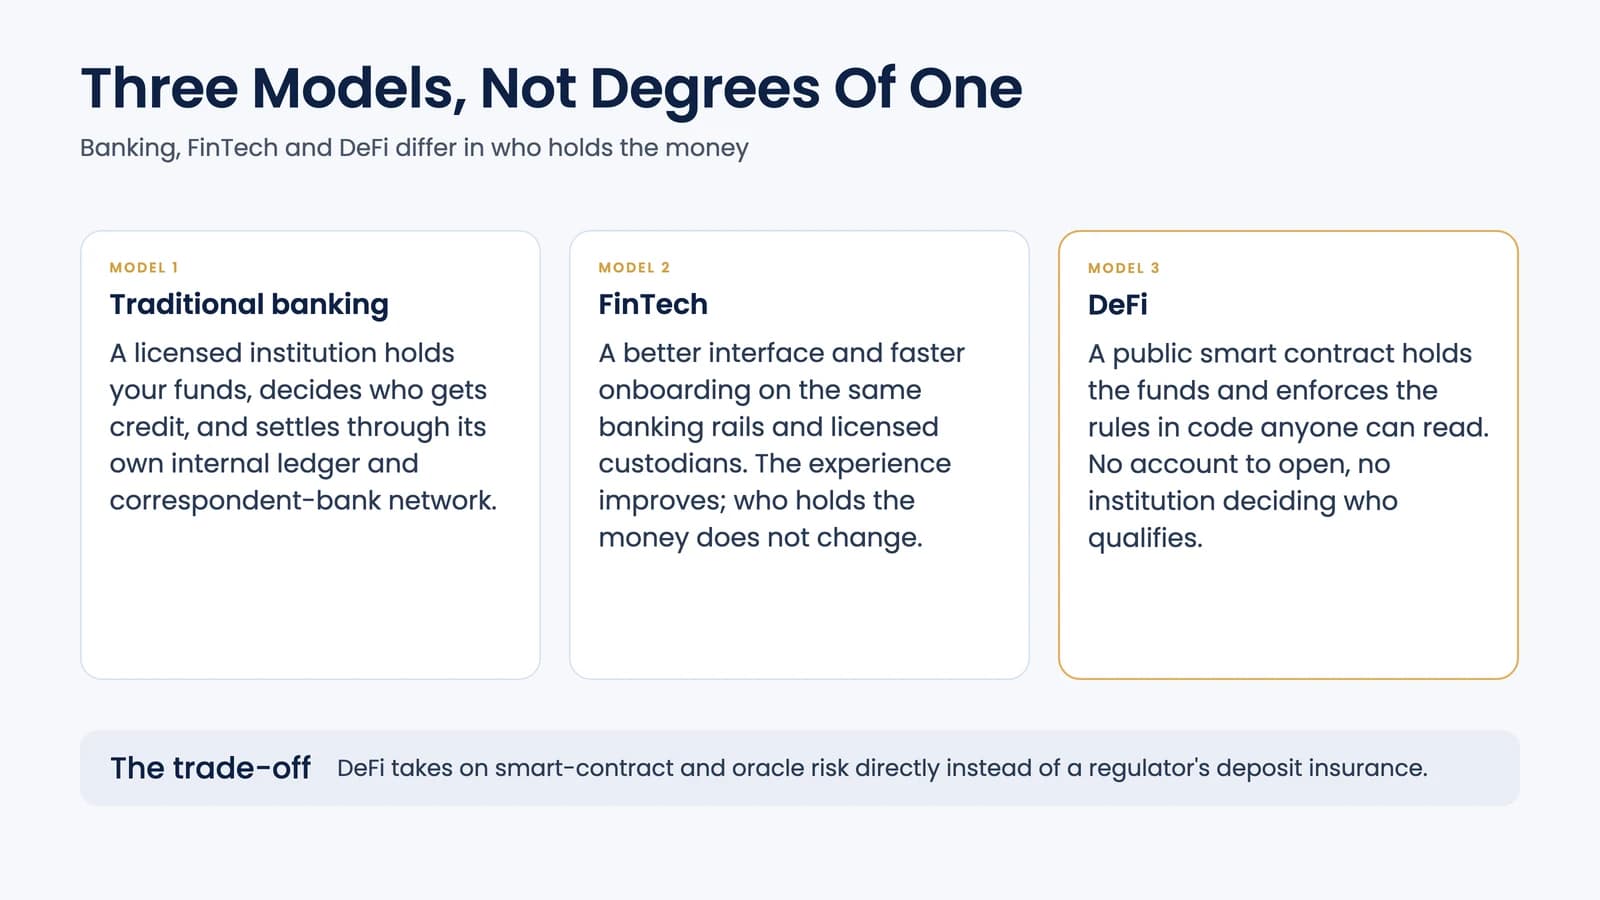
DeFi, traditional banking and FinTech are three different models, not degrees of the same thing
- Traditional banking: a licensed institution holds your funds, decides who gets credit, and settles transactions through its own internal ledger and correspondent-bank network.
- FinTech: a company builds a better interface and faster onboarding on top of the same banking rails and the same licensed custodians, improving the experience without changing who holds the money.
- DeFi: a public smart contract holds the funds and enforces the rules in code anyone can read, with no account to open and no institution deciding who qualifies, in exchange for taking on smart-contract and oracle risk directly instead of a regulator's deposit insurance.
A concrete example makes the difference clearer: Aave, currently the largest DeFi protocol by value locked, lets anyone deposit an asset as collateral and borrow another against it, with interest rates set by a formula reacting to supply and demand in the pool, not a loan officer. No application, no credit check, and no appeal if the contract's logic decides to liquidate a position that falls below its collateral ratio; the code is the agreement, published and auditable before you ever use it.
The number that matters: what's actually locked in DeFi now
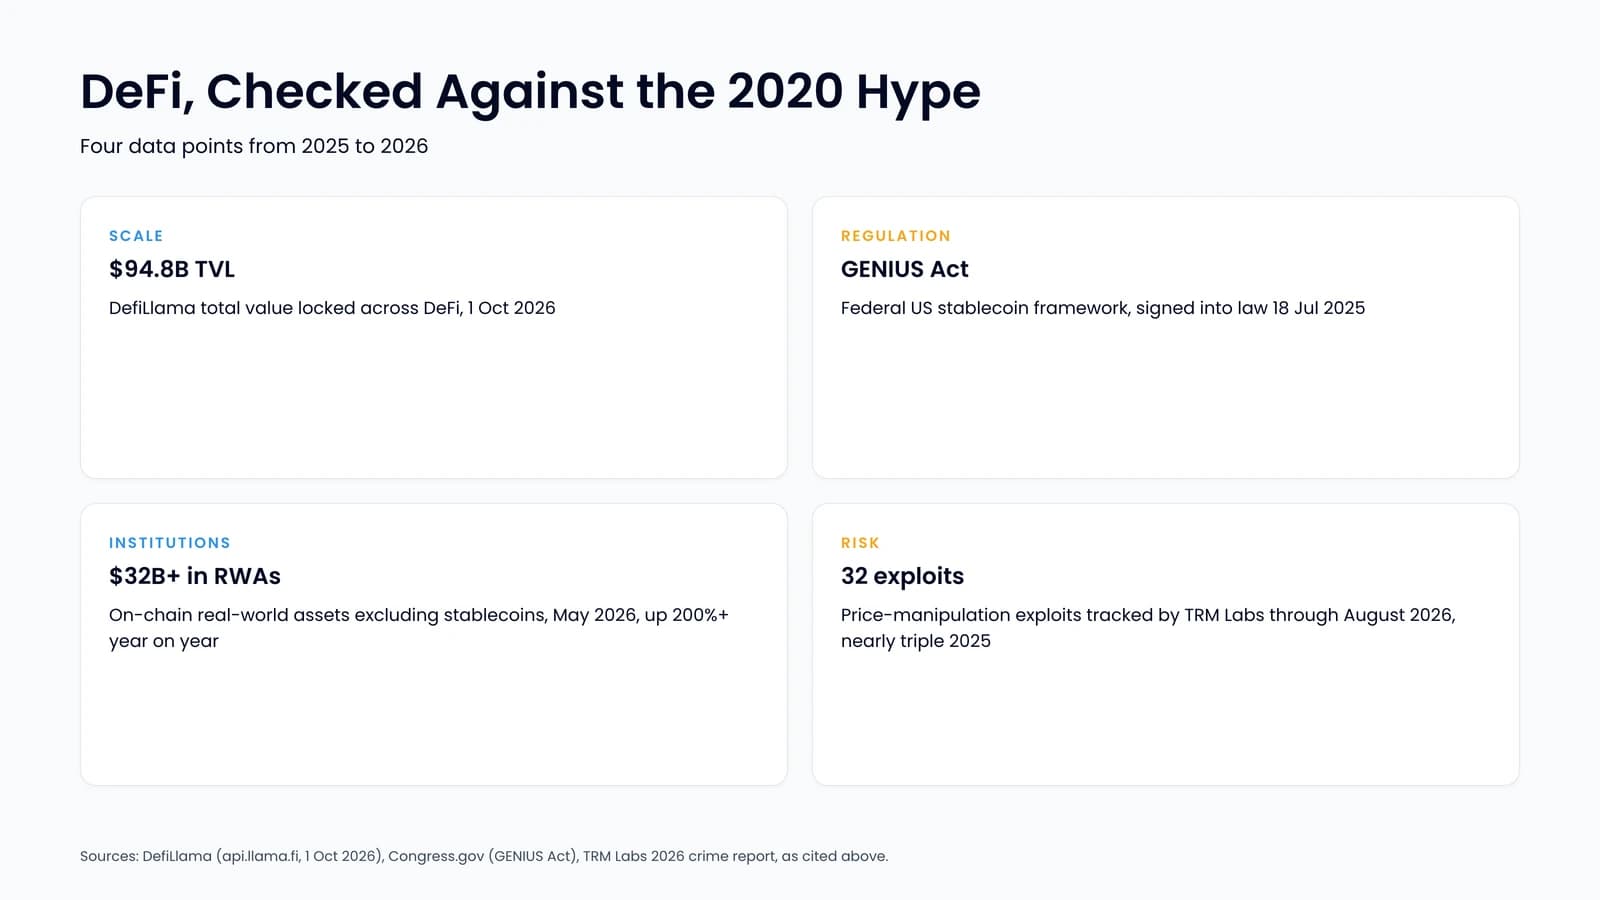
DefiLlama tracked $94.8 billion in total value locked across DeFi protocols on October 1, 2026. That is well below the roughly $180 billion peak of 2021's speculative run, and it fell about 39% at one point earlier in 2026 as yields cooled, but it has held in the tens of billions for years now, not collapsed to zero the way a pure hype cycle would. Ethereum carries the largest share of that figure, with Aave and Lido the two largest individual protocols by value locked. The composition changed more than the headline number: a growing share of that $94.8 billion is tokenized real-world assets and stablecoin-adjacent products, not the uncollateralized yield-farming tokens that defined the 2020 to 2021 cycle.
What made 2026 different: regulation caught up
The clearest sign DeFi stopped being a fringe experiment is that governments started writing rules for it. The GENIUS Act, signed into US law on July 18, 2025, created the first federal framework for dollar-backed stablecoins, covering issuer authorization, one-to-one reserves, redemption rights and sanctions compliance, the infrastructure most DeFi trading and lending runs on top of. A broader market-structure bill, the CLARITY Act, passed the House 294 to 134 in July 2026 and would split crypto oversight between the SEC and CFTC with a clear test for when a token counts as a commodity, but the Senate rejected a cloture vote 49 to 50 on September 15, 2026, eleven votes short, over unresolved ethics provisions; unless the Senate revisits it before Congress's October 5 recess, the bill likely slips to 2027. In the EU, MiCA already requires licensed crypto-asset service providers to run ongoing AML monitoring and has been in force since 2024.
Institutions moved in, and brought real money
The more concrete evidence against "it's just a buzzword" is who is using DeFi now. On-chain real-world-asset value, excluding stablecoins, passed $32 billion in May 2026, up more than 200% year on year, with tokenized US Treasuries the largest category at roughly $15 billion. BlackRock's BUIDL fund, issued through Securitize, grew to roughly $2.8 billion in assets under management and became usable as DeFi collateral after a Uniswap integration; it briefly lost the largest-tokenized-Treasury-fund title to Circle's USYC in March 2026, after USYC was wired into Binance as institutional derivatives collateral, before BUIDL's own AUM growth put it back in the lead by September 2026. JPMorgan and Goldman Sachs are both issuing or trading tokenized versions of traditional assets on public blockchains. None of that happens because a technology is a passing trend; it happens because the underlying infrastructure settles transactions and reports collateral value reliably enough for regulated institutions to depend on it.
The risk side is just as real, and just as current
None of this makes DeFi safe by default. TRM Labs tracked 32 price-manipulation exploits through August 2026, nearly triple the 12 recorded in all of 2025: an attacker drained about $18 million from Ostium's liquidity vault on Arbitrum in July 2026 by gaming its own oracle reporting, and Moonwell lost roughly $8.7 million in August 2026 after an attacker manipulated the price of a thinly traded token and borrowed against the inflated value. These are not scams or vaporware; they are real protocols with real users losing real money to specific, well-understood attack patterns. Evaluating a DeFi protocol in 2026 means checking its audit history, its oracle design and how its collateral is actually priced, the same diligence you would apply to any financial infrastructure handling other people's money.
Beyond oracle exploits: the risks that are specific to DeFi
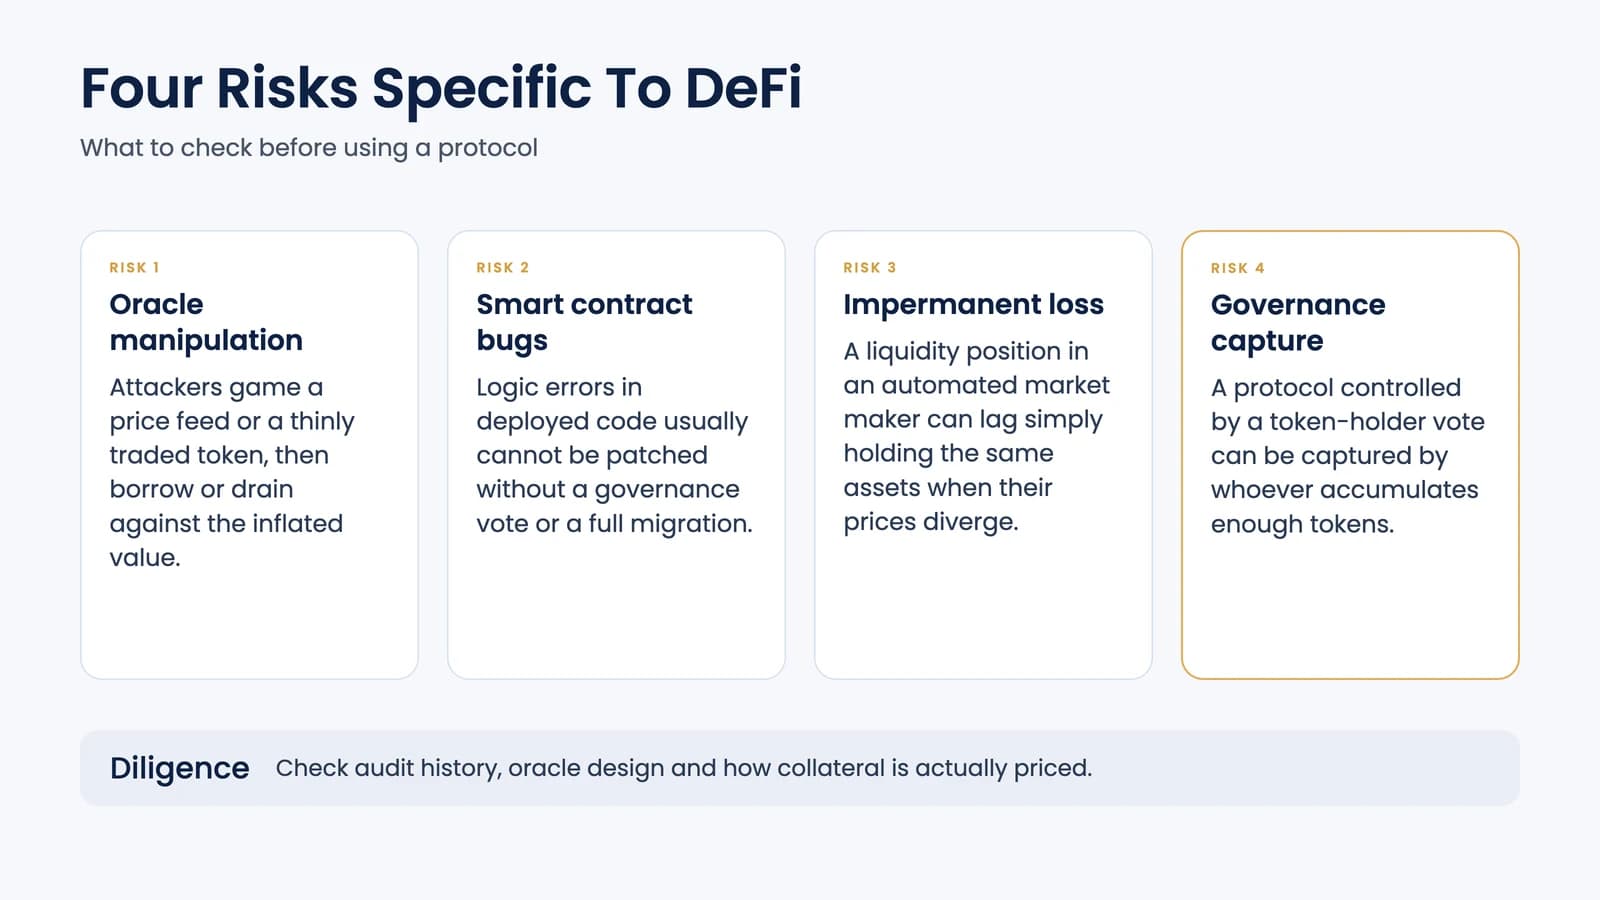
Oracle manipulation is not the only technical risk worth naming. Smart contract bugs, logic errors in code that, once deployed, usually cannot be patched without a governance vote or a full migration, have caused some of DeFi's largest single losses historically. Impermanent loss affects anyone providing liquidity to an automated market maker: the value of a liquidity position can lag simply holding the same assets when their prices diverge, a cost that is easy to underestimate before you have felt it. And governance itself is a risk surface: a protocol controlled by a token-holder vote can be captured by whoever accumulates enough tokens, a concentration risk that shows up differently from protocol to protocol depending on how its token is distributed.
So, is it a buzzword?
Not anymore, in the sense the question was asked in 2020: DeFi did not fade out, and it did not replace traditional finance either. It became a parallel settlement and lending layer that traditional institutions increasingly plug into for specific jobs, tokenized collateral, programmable settlement, cross-border transfers, while carrying the same obligation every other piece of financial infrastructure carries: get the security and the compliance right, or the losses are real and public.
4IRE builds DeFi lending, trading and tokenization platforms for clients evaluating this space; see our guide on how DeFi lending works and our roundup of where to hire DeFi developers for a closer look at what building here actually involves. Our DeFi development team can help you scope a specific product.
FAQ on DeFi in 2026
Yes. DefiLlama tracked $94.8 billion in total value locked across DeFi protocols as of October 1, 2026, and institutions including BlackRock, JPMorgan and Goldman Sachs now issue or trade tokenized assets on public blockchains, evidence of durable use rather than a passing trend.
The US GENIUS Act (July 2025) created a federal framework for dollar-backed stablecoins. A broader market-structure bill, the CLARITY Act, passed the House in 2026 but stalled in the Senate in September 2026. The EU's MiCA has required licensed crypto-asset service providers to run ongoing AML monitoring since 2024.
It carries real, documented risk: TRM Labs recorded 32 price-manipulation exploits through August 2026 alone, including losses in the tens of millions of dollars at individual protocols. Evaluating a protocol's audit history and oracle design before using it matters as much as evaluating any other financial service.
The uncollateralized yield-farming tokens that defined 2020's hype cycle gave way to a market increasingly built around tokenized real-world assets, stablecoins and institutional collateral, alongside a 2026 regulatory framework (the GENIUS Act, MiCA) that did not exist in 2020.