


Sustainable finance, meaning investment decisions made with environmental, social and governance (ESG) goals in mind, has moved from a niche mandate to a standard line item for banks, insurers and asset managers, pushed along by regulation like the EU's Corporate Sustainability Reporting Directive and by corporate net-zero commitments. Blockchain is one of the technologies GreenFi has adopted fastest, because the sector's core problem (proving that a claimed environmental benefit is real, and that it hasn't been counted twice) is exactly what a shared, tamper-evident ledger is good at. Here's where blockchain is actually earning its place in sustainable finance in 2026, and where the hype has outrun the evidence.
What sustainable finance covers
Sustainable finance spans banking, investment and insurance products built around ESG criteria: green bonds, sustainability-linked loans, green investment funds and climate-risk insurance. One of its most active subfields is carbon trading (the buying and selling of credits that let a company emit a defined amount of CO2), which has its own detailed market overview worth reading alongside this one.
Not everything marketed as "green" holds up to scrutiny. A credit card that donates to a conservation charity, an insurance product that responds to flood risk without addressing its causes, or a company that merely uses recycled paper are adjacent to sustainability without actually reducing anyone's footprint. That gap between marketing and measurable impact is the same gap blockchain-based tracking is meant to close.
Where blockchain fits in GreenFi
Supply chain transparency
A public ledger gives every participant in a supply chain the same view of price, origin, timestamp and custody data, which makes it harder to falsify a claim about where a product came from or how it was made. This is most valuable in sectors such as commodities, textiles and food, where sustainability claims have historically been hard to check independently.
Carbon footprint tracking and trading
This is where 4IRE has the most direct, hands-on experience, through our work on carbon credit trading platforms. Blockchain lets a registry or marketplace record every issuance, transfer and retirement of a carbon credit in a way anyone can audit, which matters because double-counting and weak verification are the most persistent complaints against the voluntary carbon market. The compliance side of carbon trading is dominated by the EU Emissions Trading System, where allowances traded at roughly €85 per tonne of CO2 as of late September 2026, by far the largest and most liquid carbon market in the world. On the blockchain-native side, Toucan Protocol has processed a cumulative $4 billion in carbon credit trading volume since launch, and AirCarbon Exchange (ACX), a licensed carbon and REC exchange, has settled more than 21 million tonnes of CO2e through tokenized instruments including its Carbon Emission Tokens (CET) and Gold Standard-linked tokens. Neither replaces a registry like Verra or Gold Standard. They sit on top of one, and after a 2021-2022 controversy over tokenizing older, lower-quality retired credits, Verra tightened its rules on how its credits can be bridged onto public chains. Registries themselves are part of this shift too, as we cover in why carbon credit registries are entering blockchain.
Renewable energy trading
Peer-to-peer energy trading lets households and businesses with distributed energy resources (rooftop solar, batteries) sell surplus power directly to neighbours on the same grid. Blockchain's role is recording who produced and consumed what, in near real time, without a utility having to reconcile every micro-transaction manually.
Circular economy tracking
Material-reuse and recycling programs use similar ledger-based tracking to follow a material from waste stream back into a new product, giving both regulators and buyers a way to verify recycled-content claims instead of taking a label at face value.
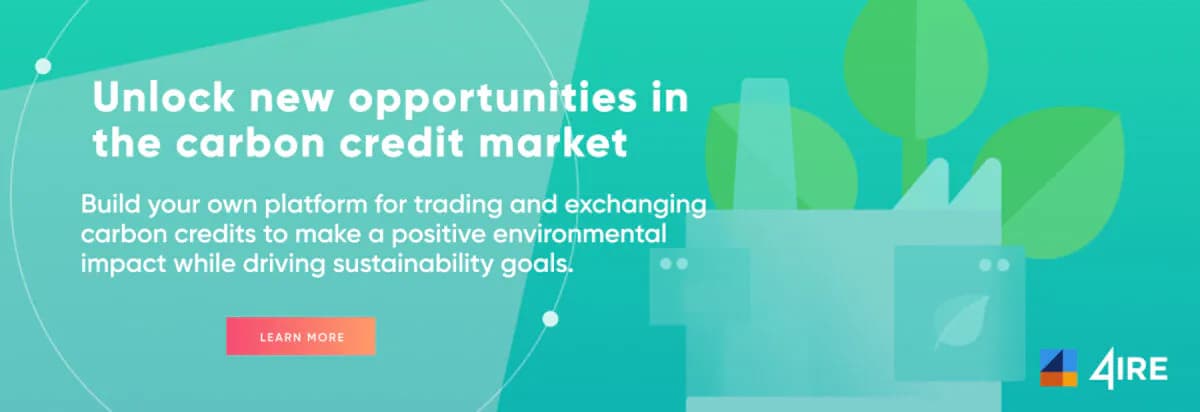
Challenges facing green investors
- Skewed demand and supply. Liquidity in GreenFi is thinner than in mainstream markets, so well-known projects get overvalued while smaller ones struggle to find buyers.
- High entry barriers. Green bonds are typically sold in large, indivisible units, pricing out smaller investors.
- Loose certification. GreenFi assets lack a single validation standard, which leaves room for greenwashing: funds raised for a sustainability claim that isn't real.
- High certification costs. Third-party certification improves trust but is expensive, and that cost usually lands on investors through lower net returns.
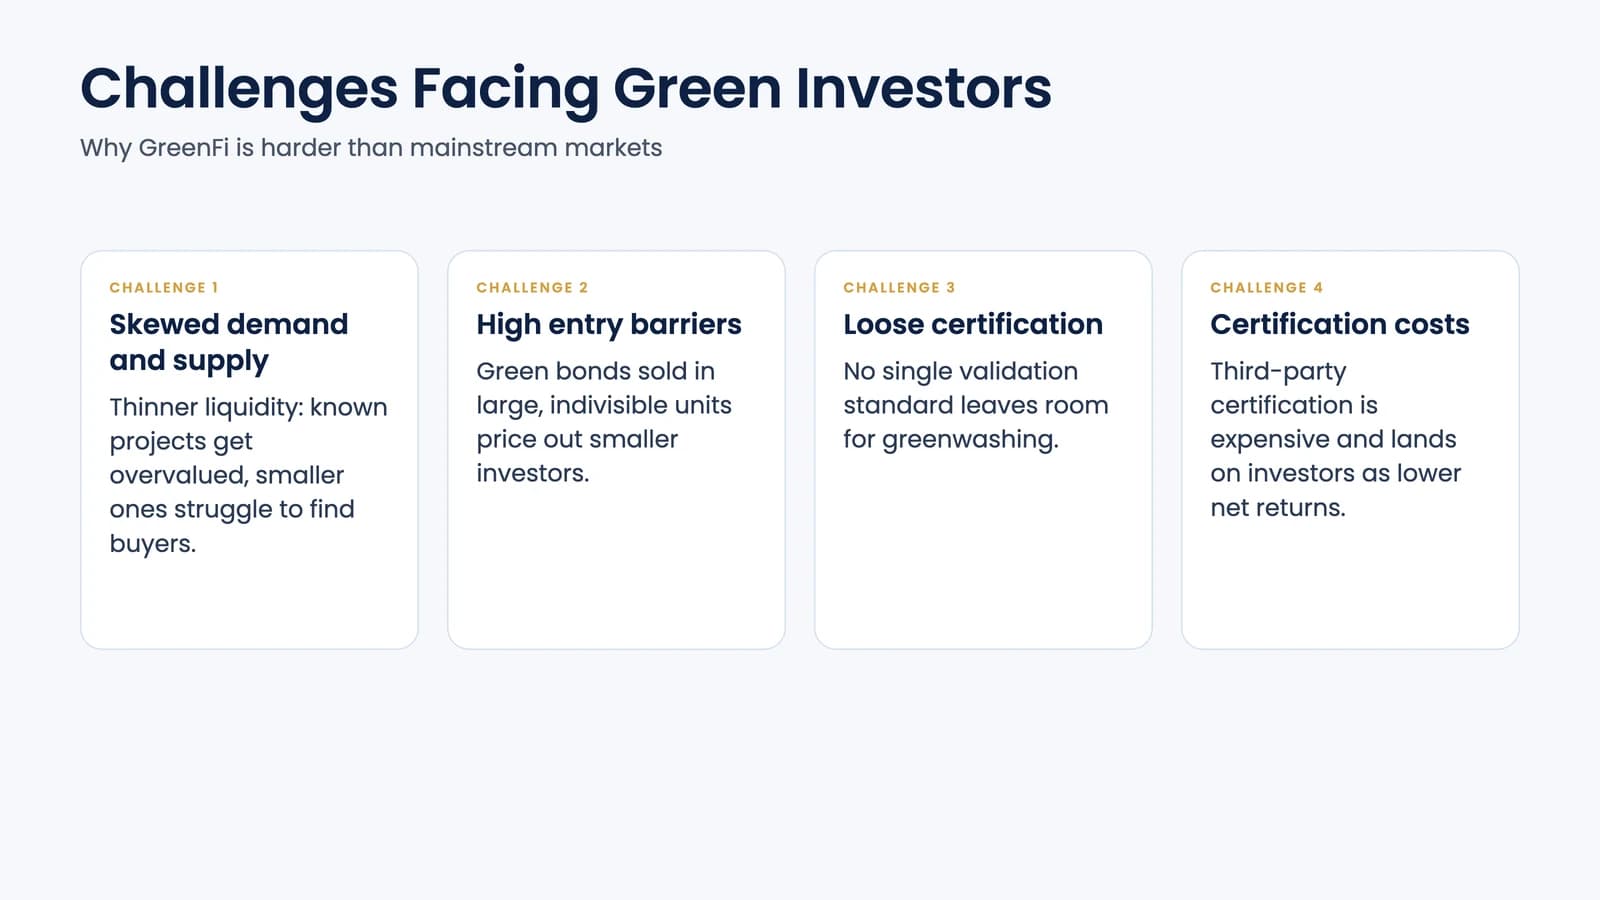
Tokenization as a partial fix
Turning a green bond or a carbon credit into a token doesn't fix weak underlying verification, but it does address several of the structural problems above: it lets investors buy fractional exposure instead of a full bond lot, it standardizes issuance and transfer so assets move faster between platforms, and it makes duplicate or fraudulent claims easier to catch because every transfer is visible on-chain. For a deeper look at how this plays out for carbon credits specifically, see our guide to carbon credit tokenization, and for the broader tokenization market beyond carbon, our real world asset tokenization guide.
Real-world examples
- Hong Kong's tokenized green bond. In February 2023, the Hong Kong government partnered with the Hong Kong Monetary Authority to issue a tokenized green bond (HKD 800 million, reported at 4.05% yield) under its Green Bond Programme, the first government-issued tokenized green bond globally at the time and aimed at reducing settlement friction and improving reporting transparency.
- Project Genesis. A prototype from the BIS Innovation Hub's Hong Kong Centre and the HKMA that used tokenization, smart contracts and IoT to make retail green bond issuance more transparent, letting investors track coupon payments and the CO2 impact of the projects a bond financed.
- Recycle Chain. A Hyperledger-family project that used a shared, synced ledger to coordinate waste-disposal logistics between municipalities and recyclers, aiming to cut the transportation and coordination costs that make recycling programs expensive to run.
- The Plastic Bank. A social enterprise that treats collected plastic waste as a form of currency, giving collectors in vulnerable communities a blockchain-tracked way to redeem their collection for cash, goods or services.
4IRE's GreenFi work
4IRE has spent over a decade in fintech and blockchain development, including hands-on work on carbon credit platforms and broader green finance development projects across GreenFi. If you're building a carbon trading marketplace, a green investment fund, or a tokenization layer for sustainability-linked assets, that's the kind of legal-plus-technical build our team scopes regularly.
The bottom line
Blockchain doesn't make an environmental claim true. It makes it checkable. That's a meaningful improvement for a sector whose biggest credibility problem has been unverifiable claims and double-counted credits, and it's why carbon registries, green bond issuers and renewable energy platforms keep adopting it even as the broader crypto market cycles through hype and correction. The projects that succeed treat blockchain as infrastructure for trust, not as the product itself.
Learn more from us
 GreenFi29 Sept 2026
Carbon Credit Market Overview: How Web3 Is Changing It
How the carbon credit market works, compliance vs. voluntary markets, and which blockchain-based carbon platforms have real 2026 trading volume.
Slava Malchenko
 Blockchain news28 Sept 2026
Real World Asset Tokenization in 2026: A Practical Guide to RWA
Real world asset tokenization explained: asset classes, how the stack works, 2026 RWA market data, US, EU, Singapore and UAE rules, and how to launch.
Olena Petrashchuk
 GreenFi23 Apr 2026
Carbon Credit Tokenization: ReFi's Potential and Limits in 2026
How ReFi and carbon credit tokenization actually work in 2026, what Toucan and KlimaDAO's history teaches, and what tokenization can't fix.
Olena Petrashchuk
Build Your GreenFi Platform
Whether it's a carbon marketplace, a green bond platform or a tokenized sustainability fund, our team can help you scope the legal and technical build together.
FAQ
It increases traceability and trust across green bond and carbon credit management, reducing room for double-counting and unverifiable claims. It also lowers cross-border transaction friction and, through tokenization, opens fractional access to assets that were previously sold in large, indivisible units.
Most GreenFi projects run on the same major networks (Ethereum, Polygon and similar) used elsewhere in crypto. Ethereum's own energy footprint dropped sharply after its 2022 move from proof-of-work to proof-of-stake, which removed one of the main objections to running sustainability projects on it.
Regulation is tightening steadily: corporate sustainability reporting rules in the EU, evolving carbon market rules tied to the Paris Agreement, and stricter national carbon pricing schemes all push businesses toward auditable, standardized reporting, which is exactly what a blockchain-based system is built to provide.
By giving every credit a unique, traceable record from issuance to retirement, blockchain reduces the risk of a credit being sold or claimed twice. It doesn't replace a registry's verification work (Verra, Gold Standard and similar bodies still certify that a project delivers the emissions reduction it claims), but it makes the trading and retirement layer harder to manipulate.