

Knowing that your fintech business needs a license is the first step; our article on when a fintech business needs licensing covers that. The next question is which license. The answer depends on whether you handle fiat, crypto or both, whether you hold customer funds, and where your customers are.
This guide focuses on Europe, where one authorization can be passported across the EEA, and adds the UK, the UAE and Canada for comparison. It covers electronic money institution (EMI) and payment institution (PSP) licenses, crypto licensing under the EU's Markets in Crypto-Assets Regulation (MiCA), and Canada's money services business (MSB) registration. Rules are current as of September 2026.
The Logic of Dividing Licenses: A Strategic Checklist
Before choosing a license, answer four questions about your business model:
- Currencies: will you work with fiat, crypto-assets, stablecoins, or a mix?
- Customer funds: will you hold customer money yourself, or will a licensed partner hold it?
- Services: e-money issuance, payment processing, crypto exchange, custody, transfers? List every service, because each one maps to a regulated activity.
- Jurisdictions: where are your users, and where do you plan to market or expand?
Budget matters too: initial capital, compliance staff and audit costs differ widely between license types. Answering these questions early also makes any legal consultation faster and cheaper, because advisers can work from a clear scope.
EMI License in the EU: Issuing E-Money and Running Accounts
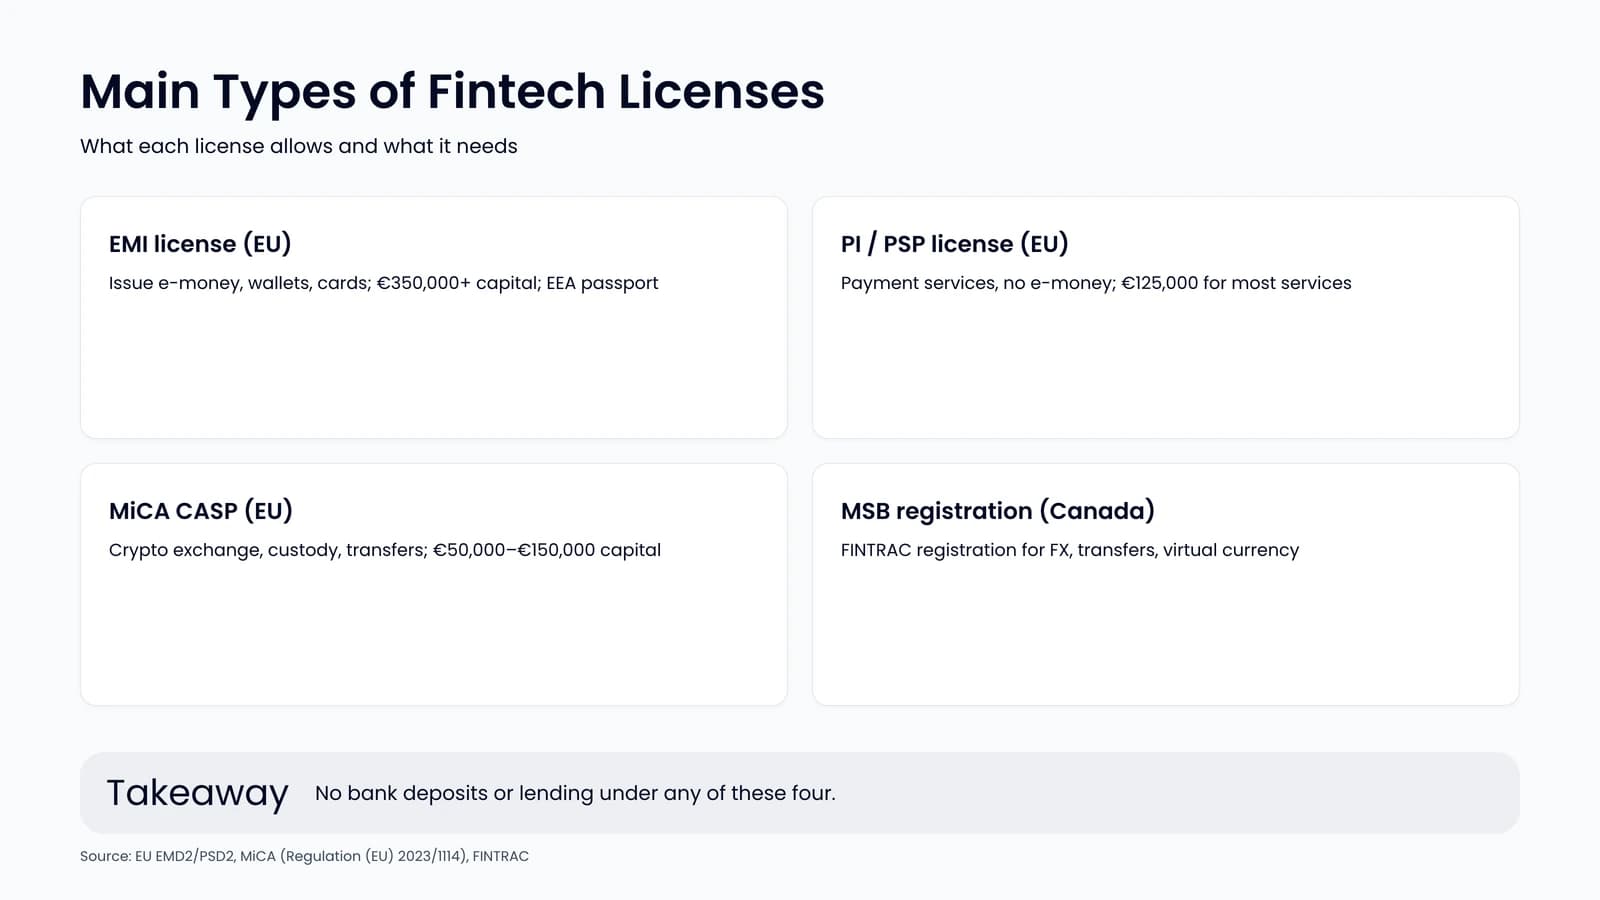
An EMI license lets a company issue electronic money and provide payment services: e-wallets, prepaid and debit cards, payment accounts and transfers. It is the usual license behind wallets and many neobanks.
An EMI is not a bank. It cannot take deposits or lend out customer money, and client funds must be safeguarded, either in a segregated account or in secure, low-risk assets, or covered by an insurance policy or bank guarantee. In return, the capital and prudential requirements are much lighter than for a credit institution.
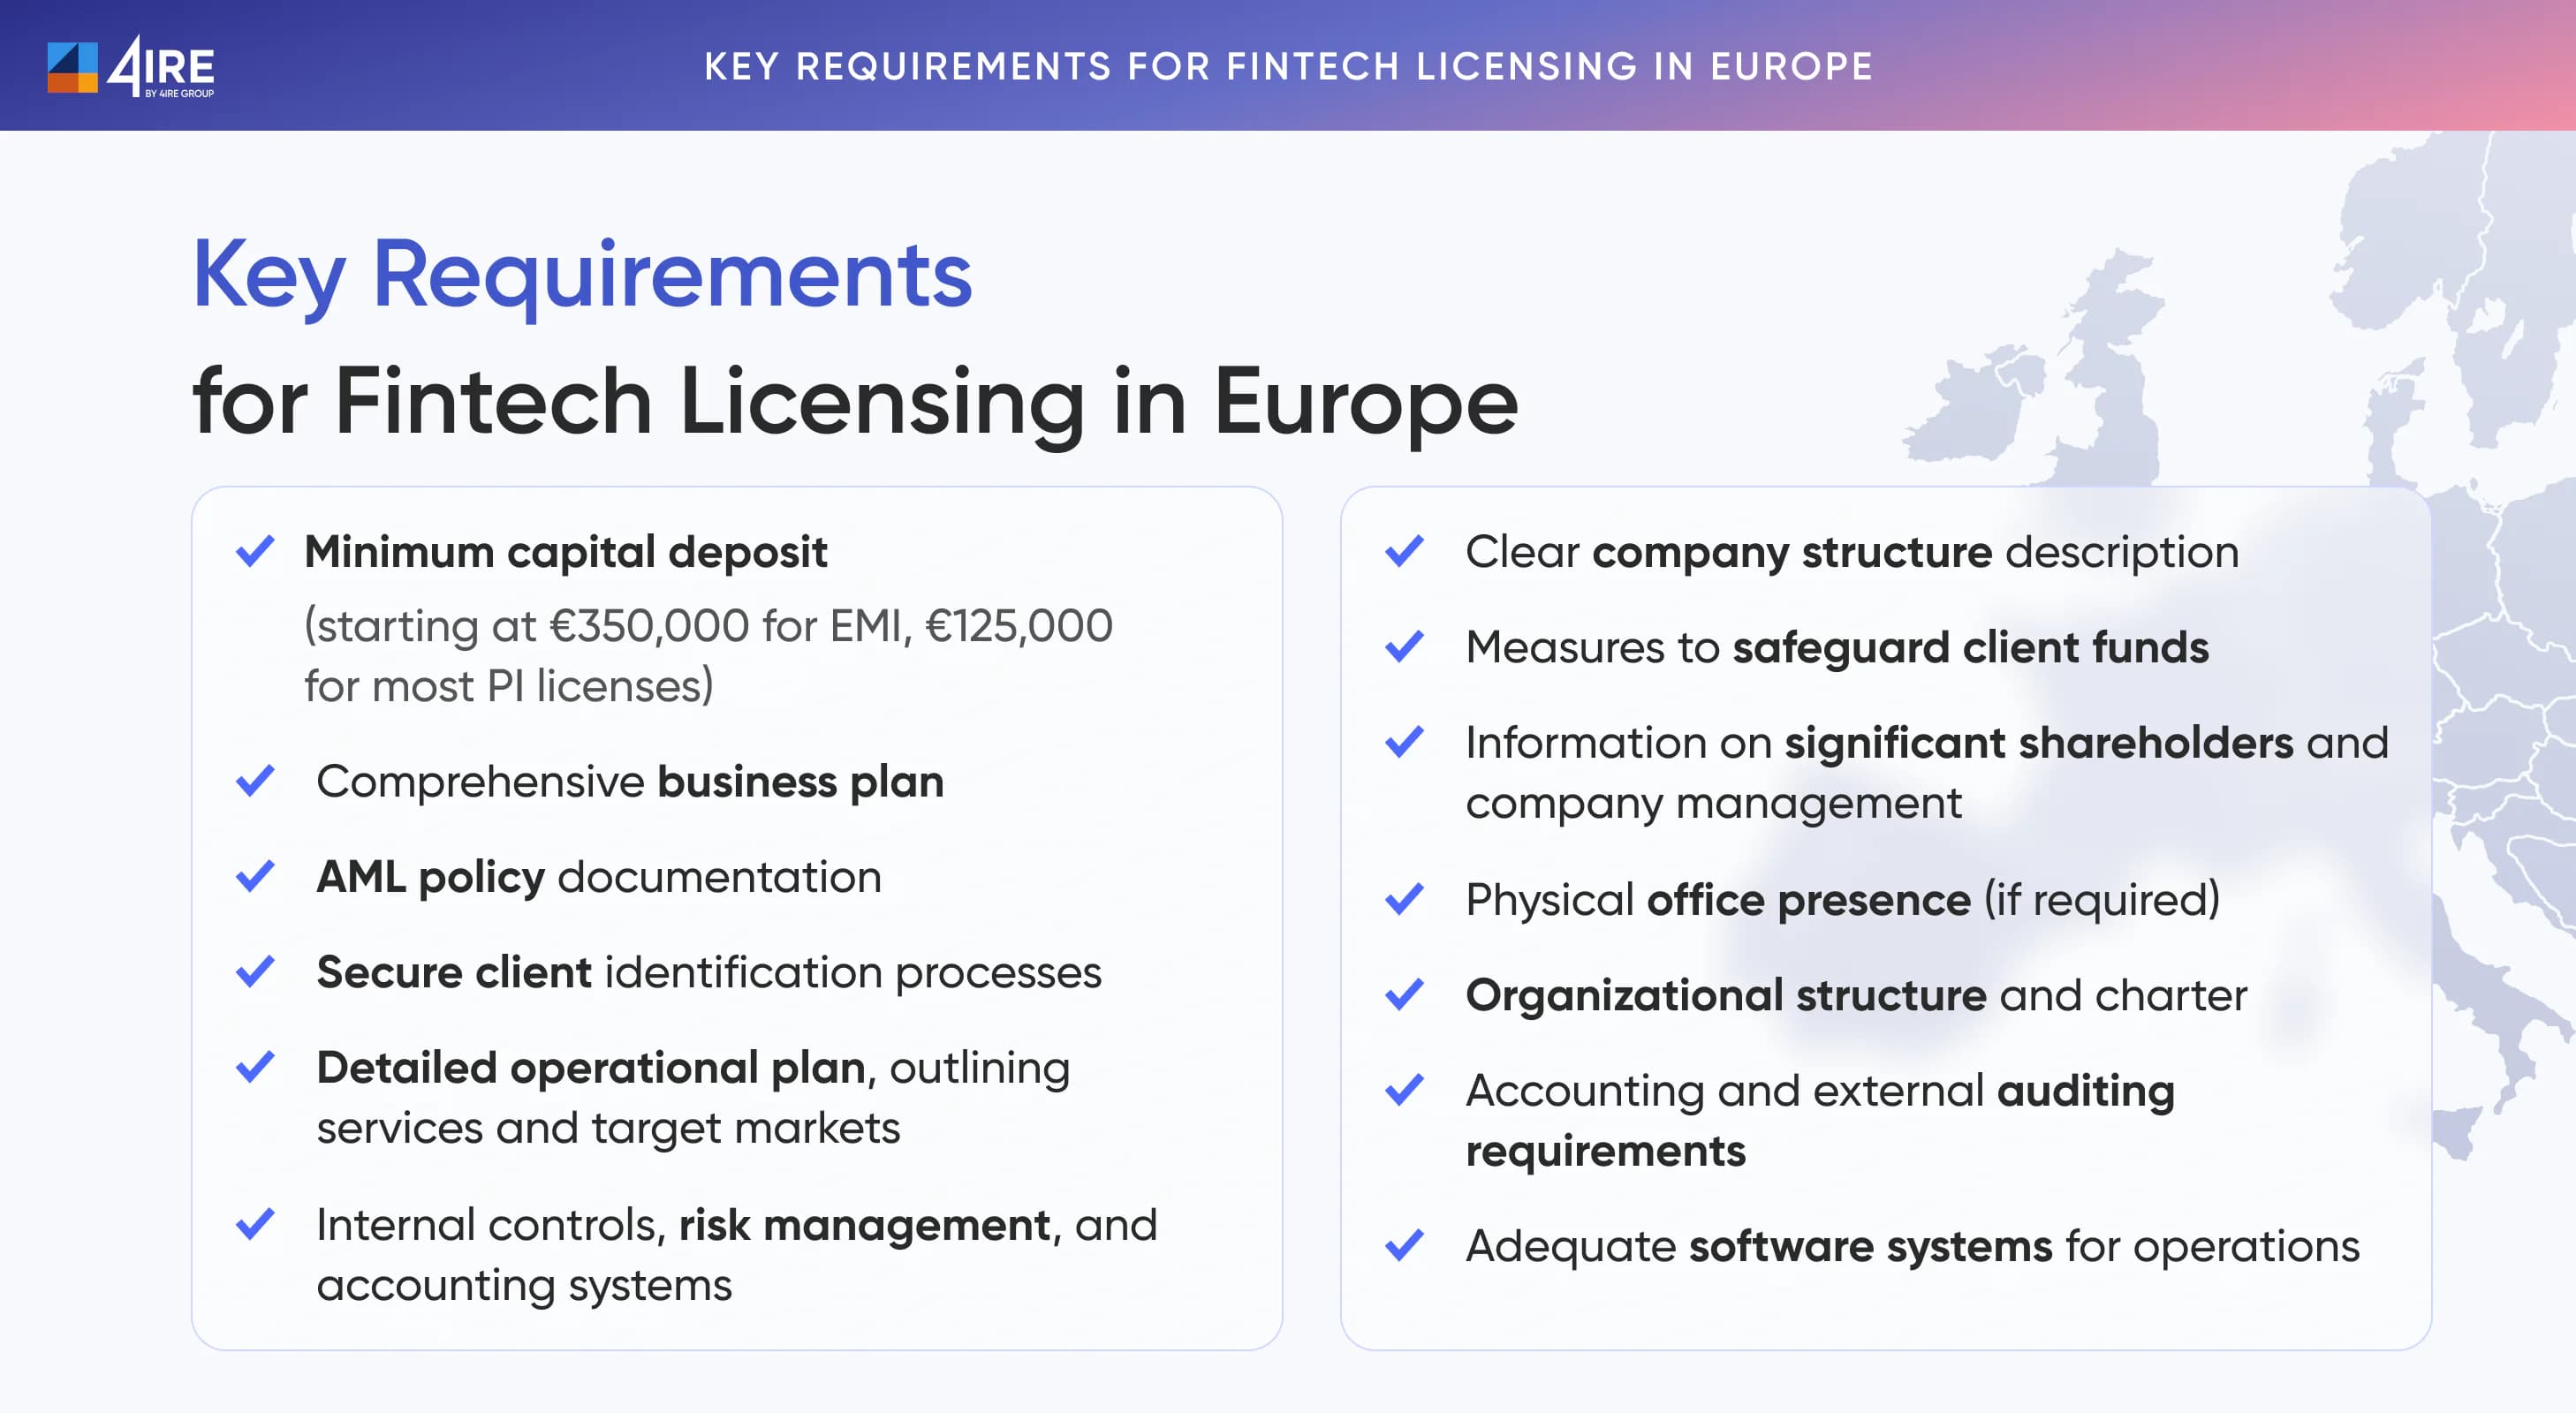
Key requirements in the EU include:
- initial capital of at least €350,000, plus ongoing own funds that grow with outstanding e-money;
- sound governance, fit and proper management and qualifying shareholders;
- an AML/CFT framework with KYC, transaction monitoring and reporting;
- IT security, operational resilience and outsourcing controls, including DORA, which has applied to EU financial entities since 17 January 2025;
- safeguarding arrangements and data protection.
Once authorized in one member state, an EMI can passport its services across the EEA. That is why hubs such as Lithuania, Ireland and Malta attract applicants, although supervisors have become noticeably stricter over the last few years.
PSD3 and UK Rule Changes
What changes next. The EU's third Payment Services Directive (PSD3) and the new Payment Services Regulation, politically agreed in November 2025 and still awaiting formal publication, merge the e-money rules into the payment services framework. Existing EMIs will need to review their authorization against the new regime once it applies, expected around 2028.
UK. Since Brexit, UK EMIs are authorized by the Financial Conduct Authority. The FCA has three months to decide on a complete application, although incomplete applications take longer. Since 7 May 2026, UK payment and e-money firms must also follow a stricter safeguarding regime with daily reconciliations, a monthly safeguarding return and, above a £100,000 threshold, an annual safeguarding audit.
PSP License in Europe: Facilitating Payment Services
A payment institution (PI) license, often called a PSP license, covers payment services such as money remittance, merchant acquiring, payment accounts and transfers, and payment initiation. Unlike an EMI, a PI cannot issue e-money, and any client money it receives must be tied to payment transactions and safeguarded.
Capital requirements are lower and scale with the services: €125,000 for most payment services, less for money remittance only or payment initiation only. Account information service providers need professional indemnity insurance rather than initial capital.
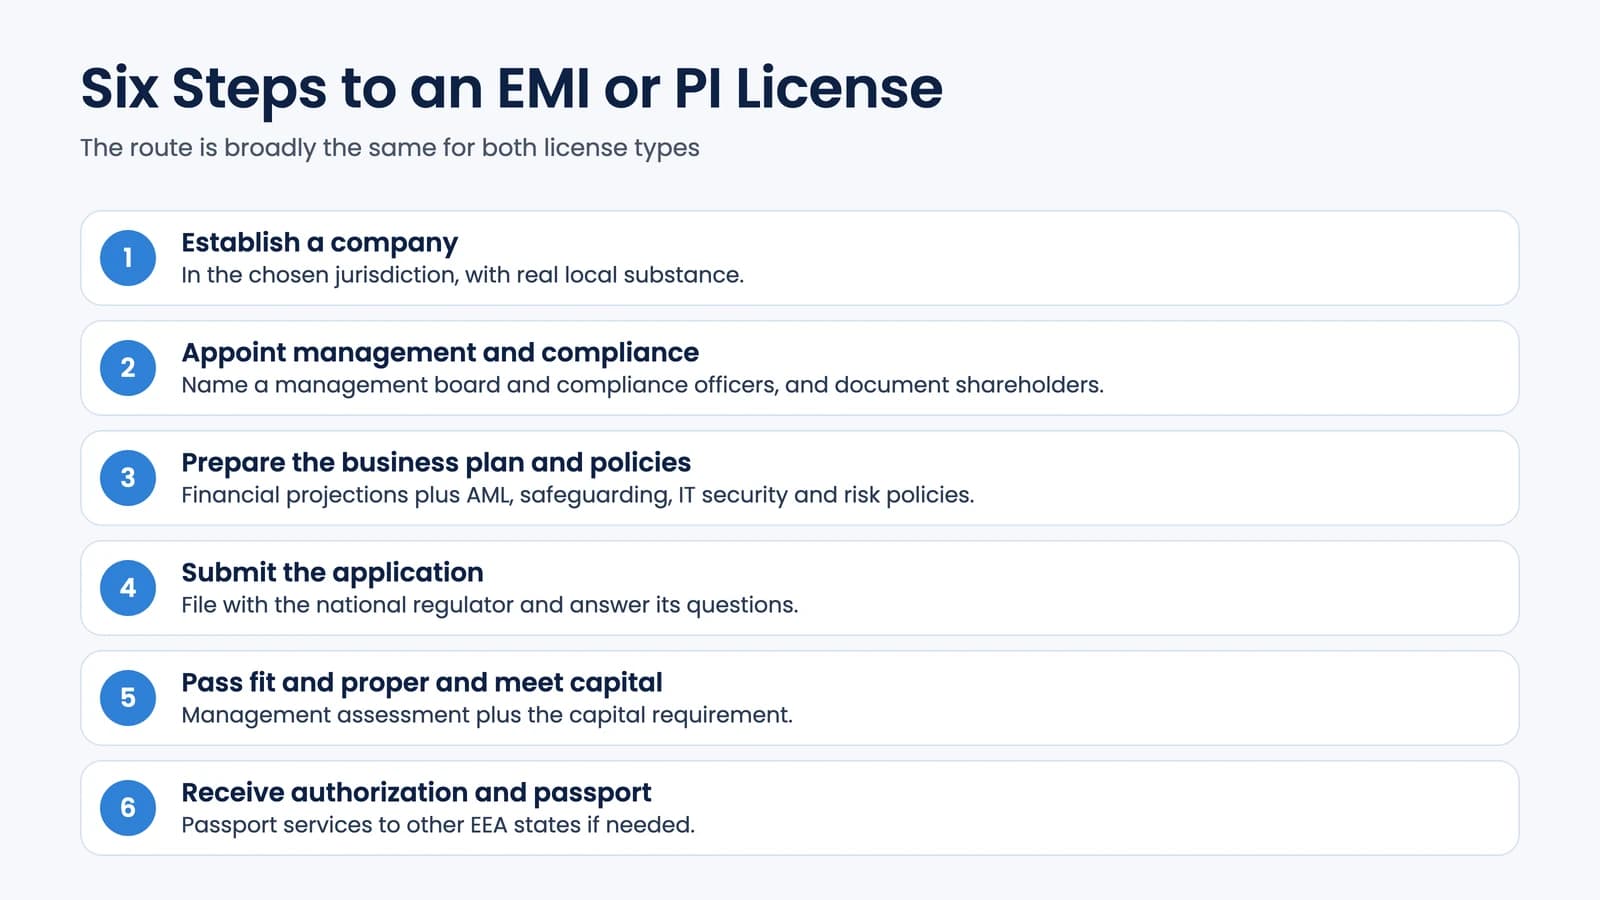
The steps to obtain an EMI or PI license are broadly the same:
- Establish a company in the chosen jurisdiction with real local substance.
- Appoint a management board and compliance officers, and document shareholders.
- Prepare the business plan, financial projections and policies (AML, safeguarding, IT security, risk).
- Submit the application to the national regulator and answer its questions.
- Pass the fit and proper assessment and meet the capital requirement.
- Receive authorization and passport services to other EEA states if needed.
Choosing between EMI and PI too late is a common and expensive mistake, because switching means a new application.
Crypto Licenses: From VASP Registration to MiCA CASP
Before MiCA, crypto businesses in the EU registered as virtual asset service providers (VASPs) under national AML rules, and countries such as Lithuania and Estonia were popular because registration was quick and cheap. That model has ended.
Under MiCA, crypto exchanges, brokers, custodians, transfer services and similar businesses need authorization as a crypto-asset service provider (CASP). A CASP license can be passported across the EU. Minimum capital ranges from €50,000 to €150,000 depending on the services, with trading platforms at the top of the range.
The transition is over. Member states could let existing VASPs keep operating for up to 18 months; several chose shorter periods (Lithuania chose 12 months). As ESMA confirmed, all transitional periods expired on 1 July 2026, and any firm providing crypto-asset services to EU clients without MiCA authorization is now in breach of EU law.
Issuing a euro or dollar stablecoin in the EU is a separate matter: e-money tokens can only be issued by a credit institution or an EMI. Our stablecoins guide explains the rules, and our article on how to build a crypto bank shows how fiat and crypto licenses combine in one product.
Beyond the EU:
- UK: crypto firms currently register with the FCA for anti-money laundering purposes. A full authorization regime starts on 25 October 2027, and the FCA opened its application gateway on 30 September 2026; firms should apply by 28 February 2027.
- UAE: in Dubai, the Virtual Assets Regulatory Authority (VARA) licenses virtual asset service providers everywhere except the DIFC financial free zone. Our podcast on getting a crypto license in the UAE covers the process.
MSB Registration in Canada: A Hybrid Approach
In Canada, businesses that exchange foreign currency, transfer funds or deal in virtual currency are money services businesses. They must register with FINTRAC, Canada's financial intelligence unit, before operating, and renew every two years. Registration covers both fiat and crypto activities, which makes it a hybrid option, but it is an AML registration, not a license to hold deposits or issue e-money. Provincial licensing may apply on top.
Since 8 September 2025, payment service providers in scope of the Retail Payment Activities Act must also be registered with the Bank of Canada and maintain risk management and funds safeguarding frameworks. A Canadian payments or crypto business may therefore need both registrations.
Conclusion
There is no universal fintech license. An EMI suits wallets, cards and accounts; a PI suits payment processing; a MiCA CASP license is now mandatory for crypto services in the EU; and Canada combines FINTRAC and Bank of Canada registrations. The right choice depends on your business model, markets and budget, so get specialist legal advice before you apply.
4IRE builds the platforms that run on these licenses, from crypto banking software to custodial and MPC crypto wallets and neobank platforms, and works with licensing partners who can support your application.
Learn more from us
 AI06 Oct 2026
Lovable AI App Builder in 2026: The Vibe Coding Risks Behind 1 Million Projects a Week
Lovable reports 1M new projects a week and $500M ARR. A CTO's view on what that means for startups, and the security risks of vibe coding to plan for.
Oleksandr Vlasenko
 Bank23 Apr 2026
How to Build a Mobile Wallet App in 2026: A Step-by-Step Guide
How to build a mobile wallet app: choose the wallet model and licence, plan core features, design the architecture, then secure, test and launch.
Olena Petrashchuk
 Fintech news28 Sept 2026
Best Open Banking APIs for Digital Banks: Top 7 Providers
Compare 7 open banking API providers for digital banks: coverage, products and licensing, plus where PSD3, UK and US 1033 rules stand in 2026.
Vladislav Malynovskyi
FAQ
Start with the services you will offer and whether you will hold customer funds, then decide on currencies (fiat, crypto or both) and target markets. Together these determine whether you need an EMI, a payment institution license, a MiCA CASP authorization or a combination.
An EMI can issue electronic money and store value for customers in e-wallets and prepaid cards, and needs at least €350,000 of initial capital. A payment institution can execute payments, run payment accounts and acquire card transactions but cannot issue e-money, and needs less capital, typically €125,000.
No. National VASP registrations stopped being a legal basis once MiCA's transitional periods expired, and 1 July 2026 was the last possible date anywhere in the EU. Crypto-asset services now require MiCA CASP authorization.
Within the EEA, one EMI, PI or CASP authorization can be passported to other member states. Outside it, such as in the UK, the UAE, Canada or the US, you generally need local authorization or registration.
Plan for several months to a year, depending on the regulator and how complete your application is. Statutory deadlines only start once the regulator considers the application complete.