

In-app payment is no longer a nice-to-have for e-commerce and m-commerce apps; it's table stakes. Customers expect to buy without leaving the app, and every extra step between "add to cart" and "paid" costs conversions. That makes the payment gateway one of the highest-impact integration decisions in a mobile app, and increasingly it's not just a choice between card processors: a growing number of businesses also want a crypto or stablecoin option alongside the usual cards and wallets.
This article explains what a payment gateway actually does, compares the leading fiat and crypto gateways you're likely to choose between in 2026, and walks through integrating one into a mobile app without creating a PCI DSS problem for yourself.
What Is a Payment Gateway?
A payment gateway is the software layer that encrypts a customer's card or bank details and passes them to a payment processor, which in turn talks to the customer's bank. In a mobile app, the flow looks like this: the customer picks a product, enters payment details, and taps "buy." The gateway forwards the request to the processor, the processor checks it with the issuing bank, and once approved, the funds move toward the merchant's account.
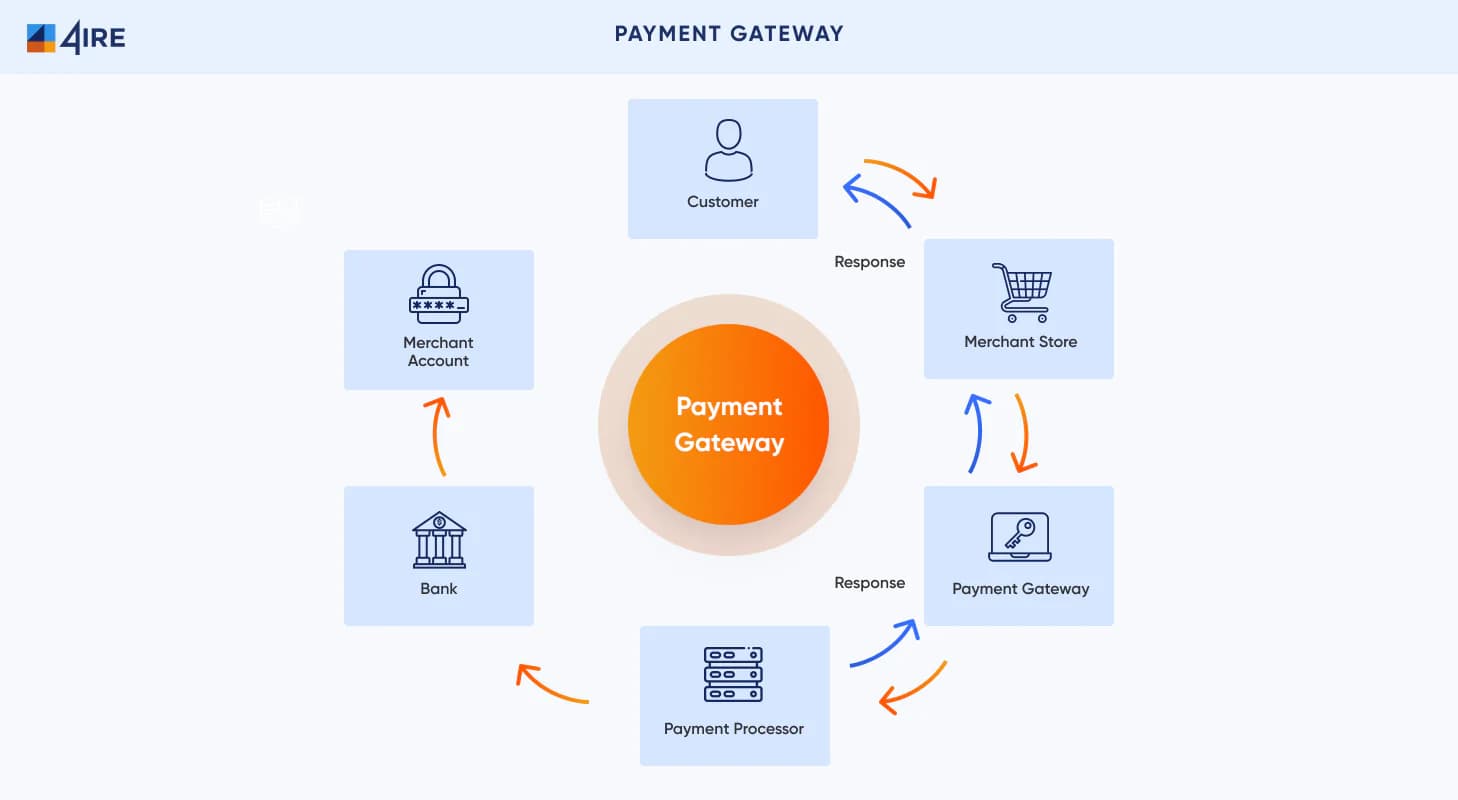
Gateways fall into two broad types. Self-hosted gateways keep the customer inside your app for the entire checkout, which gives you more control over the experience but usually means more PCI DSS scope and cost, so it tends to suit larger businesses. Hosted gateways send the customer to an external checkout page to enter their details and complete the transaction; it's less customizable but cheaper and faster to integrate, which is why most small and mid-sized apps choose it.
Merchant Accounts: Dedicated vs Aggregate
A merchant account is where customer payments land before they're transferred to your business bank account. There are two types worth knowing:
- Dedicated merchant account. Faster transfers and more control over individual transactions, including corrections, at the cost of a longer setup process.
- Aggregate merchant account. Cheaper and faster to set up because it pools funds for many merchants under one umbrella account; the usual choice for businesses that want to start accepting payments quickly.
Top Payment Gateways for Mobile Apps in 2026
- PayPal. Still the most recognized gateway worldwide, which can nudge conversion because customers already trust it. The trade-off is that customers need a PayPal account to use it, and PayPal can freeze a seller's account during a dispute, which is slow to resolve given its support process.
- Stripe. Developer-friendly, with no setup or monthly fees and support for a long list of local payment methods, including Alipay for merchants entering the Chinese market. Stripe dropped Bitcoin support in 2018, but it re-entered digital assets in 2024–2025 through its Bridge and Privy acquisitions, and now offers stablecoin payments, stablecoin-backed cards, and stablecoin payouts as part of its core product.
- Braintree. A PayPal company with a straightforward SDK and support for web wallets like Venmo, plus instant checkout across multiple sellers. Airbnb and Uber both use it, which is a reasonable proxy for scale and reliability.
- Square. Best suited to small and mid-sized businesses that want flexibility without PayPal- or Stripe-level complexity; it's part of Block, Inc. alongside Cash App.
- Adyen. A single platform for cards, wallets, and local payment methods across many countries in one integration, popular with apps that need to scale checkout internationally without stitching together several regional processors.
What If You Want to Accept Crypto?
If you want to accept crypto or stablecoins alongside cards, you'll typically use a dedicated crypto payment gateway rather than bolting crypto onto a card processor. Options with an active, verifiable track record include:
- CoinGate. A MiCA-licensed crypto payment gateway authorized by the Bank of Lithuania, with e-commerce plugins for WooCommerce, PrestaShop, OpenCart, and Magento.
- BitPay. One of the longest-running crypto payment processors, licensed by the New York State Department of Financial Services, offering merchant checkout, in-store payments, and crypto payouts.
- NOWPayments. Supports a wide range of cryptocurrencies with automatic fiat conversion, aimed at merchants who want a simple API rather than running their own custody.
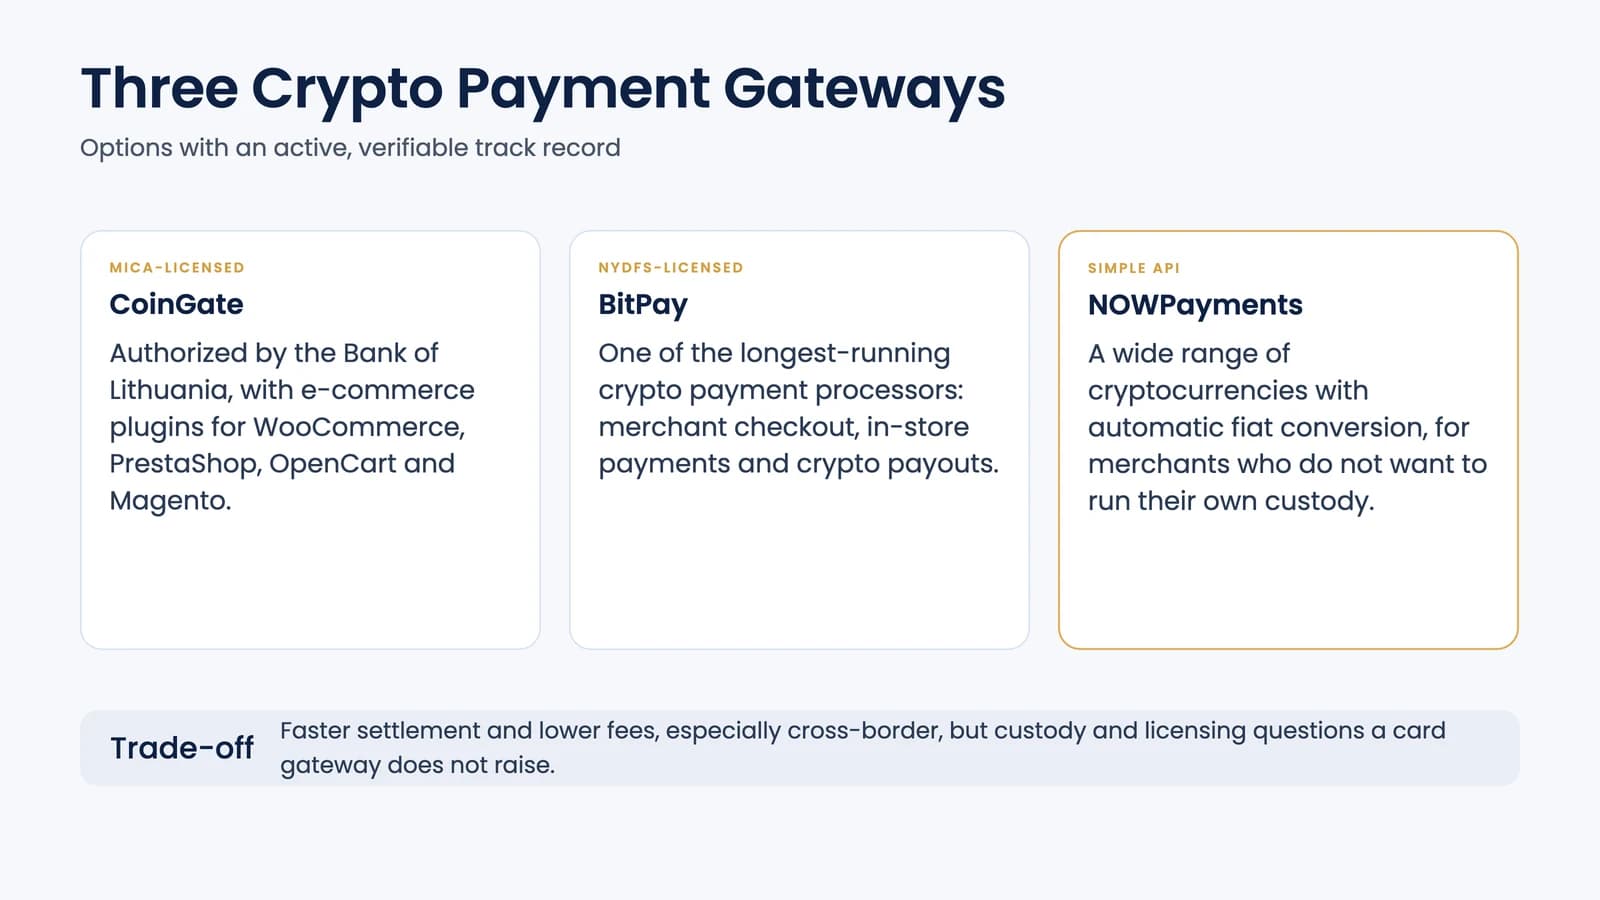
A crypto or stablecoin gateway can mean faster settlement and lower fees than card rails, particularly for cross-border payments, but it also brings custody and licensing questions a card gateway doesn't. If you're building this into a regulated product rather than a simple checkout button, it's worth reading how stablecoins are regulated before you commit to an architecture, and getting blockchain consulting input early if the payment flow touches asset custody or tokenization.
How to Integrate a Payment Gateway Into a Mobile App
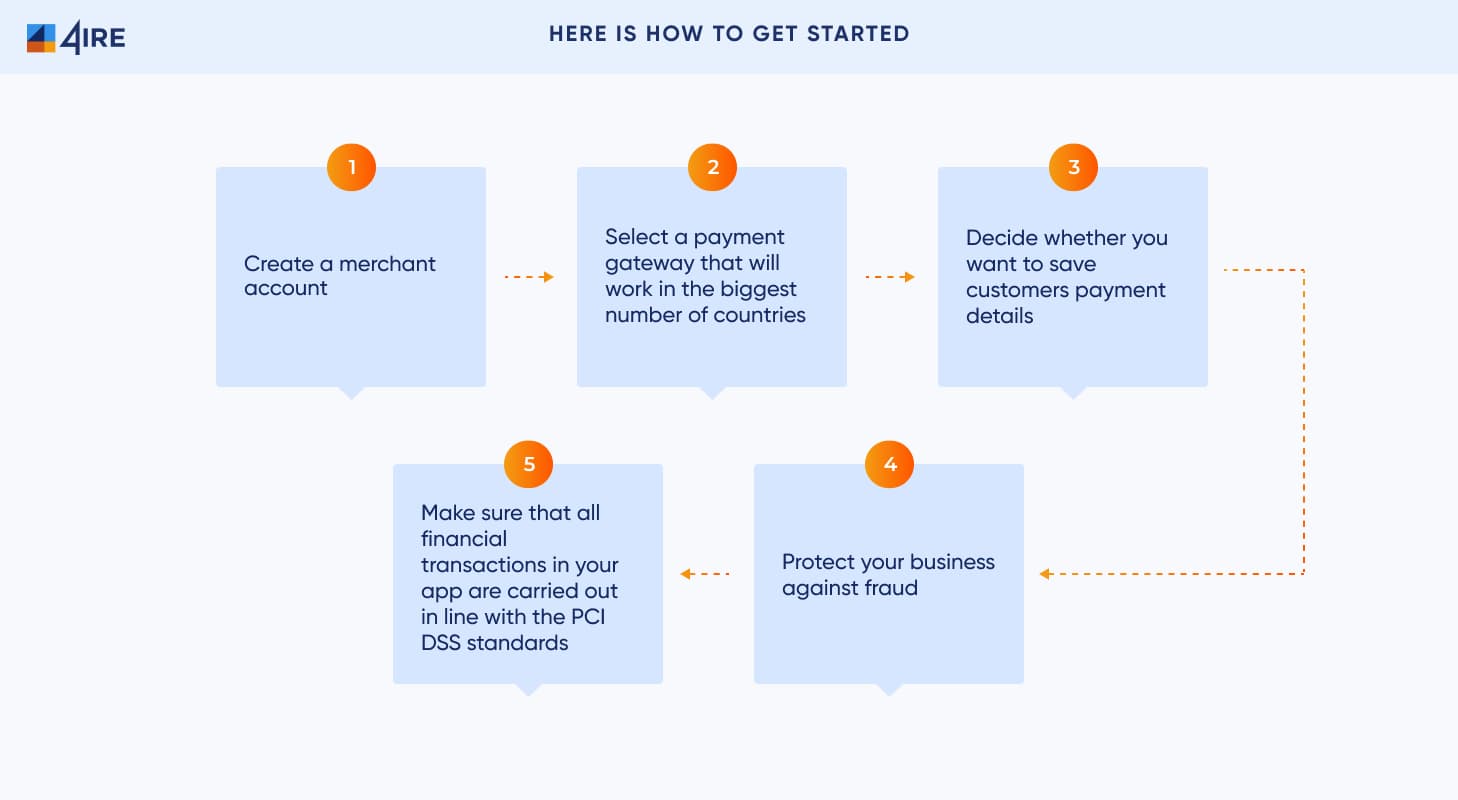
- Create a merchant account, dedicated or aggregate depending on your transaction volume and how much control you need.
- Pick a gateway that covers the countries and currencies your customers actually use, including crypto if that's part of your roadmap.
- Decide whether to store customer payment details for faster repeat checkout. It's convenient for customers, but it expands what you need to secure and usually means using the gateway's own tokenization rather than storing raw card data yourself.
- Build in fraud protection: device and behavioral checks, velocity limits, and 3D Secure where the gateway supports it, on top of whatever the processor already screens.
- Confirm every payment flow meets PCI DSS requirements: encryption in transit and at rest, restricted access to cardholder data, and regular security testing.
Integrating the SDK
Most major gateways ship a mobile SDK so you don't build the payment form from scratch. Using Stripe as an example, the typical flow is: drop in Stripe's pre-built UI elements, assemble a standardized payment form, generate a token that represents the card data without exposing it to your own servers, and submit that token to your backend to complete the charge. The pattern is similar across Braintree, Square, and most crypto gateways: the SDK handles the sensitive data, and your app only ever sees a token.
Getting It Right the First Time
Payment gateway integration is one of the few parts of a mobile app where a mistake shows up as lost revenue immediately, whether that's a checkout that fails silently, a PCI DSS gap that blocks your next audit, or a crypto flow that can't reconcile against your ledger. Our financial software development team builds both fiat and crypto payment flows, including custodial wallet infrastructure where a project needs to hold customer assets rather than just pass through a third-party gateway. If you're weighing a fiat-only checkout against one that also accepts crypto, talk to us about your target markets and compliance requirements before you lock in an architecture.
Build Your Payment Flow with 4IRE
Whether you need a fiat checkout, a crypto payment gateway, or both, our team can design and build it around your compliance requirements. Schedule a free consultation with our experts today.
FAQ
It depends heavily on scope: a basic hosted checkout with one or two payment methods costs far less to integrate than a self-hosted flow with multiple gateways, saved cards, and fraud tooling. Outsourced development teams are usually cheaper than an in-house hire for a one-off integration, but a growing product benefits from a team that can also support the flow long-term.
You'll need to demonstrate that your systems are secure across firewalls, data storage, encrypted transfer, secure coding, and logging. If you route card data through a gateway's hosted fields or tokenization rather than touching it yourself, your PCI DSS scope shrinks considerably and you may only need to complete a Self-Assessment Questionnaire rather than a full audit.
Yes, and it's common: many apps offer a card gateway alongside a wallet option like Apple Pay or Google Pay, and increasingly a crypto option on top. More choices at checkout tend to reduce abandonment, as long as the extra options don't slow down the page or add confusing steps.
It makes the most sense for apps with cross-border customers, high card-processing fees, or an existing crypto-native audience. It adds custody, compliance, and reconciliation work that a pure card checkout doesn't have, so it's worth scoping with a team that has built crypto payment flows before rather than treating it as a drop-in SDK.